

What are some areas we should review to start the year?
Question of the week: What are some areas we should review to start the year?
Answer: If the question of the week looks familiar, it is as it is we ask near the beginning of every year; because it is that important. Over the next few weeks, or months depending on your particular situation, you will be gathering statements, forms, and information to prepare your tax returns. While you have all this information in the same place it is a good time to also review various areas of your economic life to see what may need updating, or changing.
Here are some of the areas I suggest you review:
- Retirement Did you alter your retirement withholdings in 2024? Do you need to increase or decrease your deductions for your 401(k)? The maximum contribution for 2025 is $23,500, up $500 from 2024.
If you are over 50 the “catch up” contribution limits $7500 for a total contribution (pre-tax) of $31,000. If you are between 60 to 63 you can contribute an additional $11,250 in 2025 for a total of $34,750.
The combined total for employee and employer contributions is $70,000.
Note these limits include contributions to either traditional 401(k) account, or a Roth account that may, or may not, be administered by the same administrator.
Depending on your situation, you may want to review if you should make all your contributions into your 401(k) plan, or contribute some of the funds to a Roth, from which you may be able to withdraw funds tax free in the future.
Are you self-employed or work for an employer who does not have a retirement plan so you contribute to some type of IRA? Review your 2024 income and contributions and determine based on estimated income in 2025 whether you need to adjust your monthly or quarterly contributions to your IRA. If you do not make regular contributions to your IRA, I strongly recommend it so you can take advantage of “dollar cost averaging.”
- Insurance Is your hazard insurance policy current and accurately reflecting the replacement value of your home? Is your life insurance coverage adequate? Are you home, auto, life insurances with the same company allowing you to take advantage of bundled discounts?
As you are aware, many insurance companies have changed their homeowners’ insurance coverages, not issuing new policies, or dropping existing clients. Check in with your agent regarding your coverage and any expected changes that may occur from their side.
If you have significant equity in your property, consult with your property and casualty agent to see if you should consider earthquake insurance. Because the deductibles are extremely high for earthquake insurance, it is generally not recommended to get earthquake insurance if you do not have enough equity to protect when calculating premiums and deductible.
- Estate Planning Do you have an estate plan? Is it current and reflective of your current assets and wishes? Do you own property but do not think you need any family planning because you are single? Everyone with assets should have an estate plan, especially if they own real estate in California (or any other state with inheritance taxes). If you have an estate plan and family trust when was the last time you had it reviewed? Have your children become adults since the trust was last reviewed and amended? What about your wishes for you when you pass on to the next dimension, are they the same as they were when you initiated your trust?
- Debt Have you increased your debt in the past twelve months? Do you have a plan to pay it down and off? Can you restructure your debt to lower the overall interest rates being charged or the monthly cash flow required to manage the debt and keep payments current? Was your 2024 resolution to pay down/off debt but were unable to do so? Call me and we can discuss potential plans to help you achieve this goal in 2025.
- Mortgage Do you need a review of your current mortgage and options? Call me!
These are not fun or sexy issues for most people to be tackling, but like changing the batteries in your smoke detectors you need to regularly review and update these critical areas of your home economics. If you have any questions or looking for qualified professionals to assist you, please do not hesitate to contact me.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
As expected, the jobs market cooled in January. That said, it cooled more than expected. Going into today’s jobs report from the Department of Labor, the consensus was the economy added 169,000 new jobs in January, the data showed 143,000 new jobs for the month. The miss was not by much, and the number of new jobs showed that employment is still strong in our economy. Pushing that narrative was the announcement that the data for November and December was revised to show 100,000 more jobs were created in those months than previously reported. The unemployment rate dropped from 4.1% in December to 4.0% in January.
Key factors in determining the number of workers all have slowed over the last few months, hiring, quitting and layoffs, reflecting a stable employment market. The number of jobs added to the economy and the stability of the labor market are fairly interest rate neutral.
Not as neutral is the data on wages, which increased 0.5% for the month and are up 4.1% from last February, outpacing inflation by a fairly significant amount. With income adjusted for inflation increasing, enabling more discretionary spending, concerns are consumers will continue to spend and drive more economic growth, making it very hard to lower inflation. The wage data in the Labor Department’s report pretty much assures the Fed will not lower its benchmark interest rate at its next meeting, and put upward pressure on interest rates after the report was released.
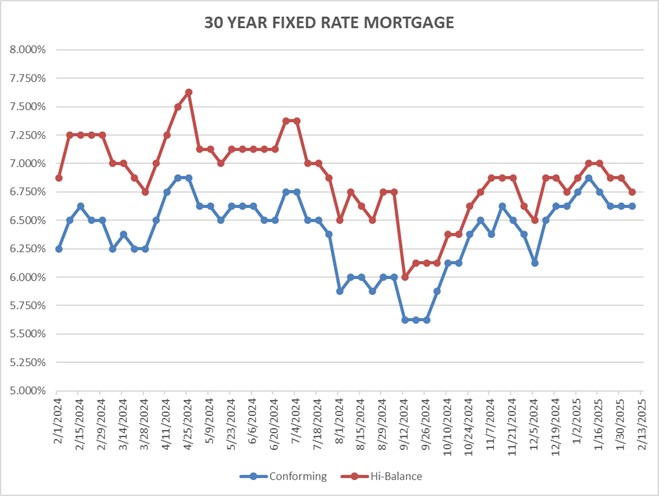
Rates for Friday February 7, 2024: Despite a bump up in rates today, due to rates dipping earlier in the week, we end the week with the conforming rate where it was last Friday with the high-balance rate dropping slightly.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.625% Flat
30-year high-balance conforming 6.75% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Our dog Sammy does not like the Philadelphia Eagles. Primarily because he does not like shouting and yelling, whooping and hollering, which are generally in abundance when I watch the universally beloved Eagles.
Sammy is in for a long afternoon on Sunday, hopefully ending with some major shouts of joy and a certain individual, who has been a faithful Eagles fan since his family moved to the Philadelphia area in 1970, singing the Eagles anthem, Fly Eagles Fly, loudly and off-key.
Go Birds!


