

How will election impact mortgage rates?
Question of the week: How will election impact mortgage rates?
Answer: Minimally.
Every four years the media for every sector of the economy runs articles on “what happens to _________ if X or Y is elected?” Automotive, travel and leisure, financial services, real estate, shoes, pets, toys and games…and mortgage.
Historically, going back many, many elections, there has been negligible movement in mortgage rates following an election. There have been some immediate responses in the days following the election as investors move money in or out of equities, bonds, cash, but very often rates revert to their pre-election range, waiting for economic data that foretells what rates may do in the future.
Looking past the short and medium term following the election, mortgage rates should move the same way regardless of which candidate wins.
Why? Because both have presented economic proposals that, if actually enacted, will increase the deficit. Higher deficits mean more borrowing by the government to fill the gap between spending and revenue. More borrowing means debt issued by the Treasury Department, that competes with mortgages for investors.
What happens when the government issues a lot of bonds to finance large spending packages? Rates go up. Unless… the Federal Reserve jumps into the market and buys an extremely large percentage of the government debt issues and funded mortgages.
Not only are the proposals presented deficit growers, but they are also inflationary. Tariffs, raise prices. Forgivable loans. Tax free income. Direct payments. All either limit supply or increase demand, depending on the sector of the economy affect is inflationary.
What happens when inflation increases? As we have seen, rates go up.
Most campaign promises from the very top of the ticket need help from lower on the ticket to become law and policy; which is why I have always been averse to one party controlling all three houses, both in Congress and the one on Pennsylvania Avenue. This limits the ability of one party to control all fiscal policy. If one party does have that ability, we can likely expect economic policy that will be more likely to keep rates relatively high, or higher.
Unless…policies, geopolitics, natural disasters, or other factors result in economy falling into recession. In which case rates would remain stable or decline depending on severity of recession and where rates are when it begins and ends.
More likely to impact rates than who is sworn in on January 20th are the decisions of the Federal Reserve. What movements, and how big, will they make? More importantly is the debt issued by Treasury, Fannie Mae and Freddie Mac.
Currently the Fed owns over $7 trillion of Treasury and mortgage debt, down from almost $9 trillion in 2022. If the Fed accelerates “unwinding” its balance sheet, i.e. selling assets, that increase supply and push rates higher. If the Fed buys more assets, sucking up available supply, rates will go lower. If the Fed does nothing, and lets their balance sheet decline as bonds and mortgage pay off, rates will be minimally impacted, if at all.
If you are making your decision on November 5th based on interest rates, you can flip a coin as whoever wins will likely have the same impact.
Schedule an appointment to discuss your options if you are considering purchasing a new home or property or refinancing an existing one and want to know the mortgage options available to you.
Have a question? Ask me!
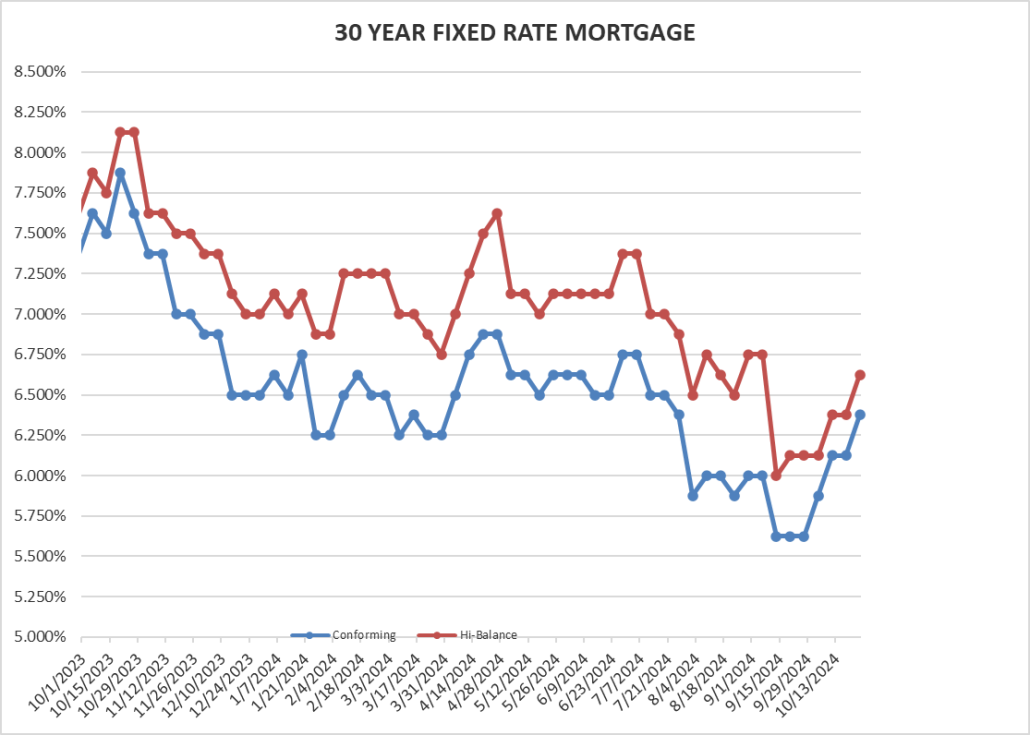
Rates for Friday October 18, 2024: Very little economic news this week, but rates are on the rise. As you may have noticed, we had no WR&MU as traveling home from our trip, but rates were stable from the Friday before. Not so much this week as investors jockey to try to predict November 5th. However, even more jockeying as they come to consensus that the Fed’s rate reduction program will likely be lower and slower in the coming months following the large cut last month. Rates spike this week, the conforming rate at its highest since the end of July.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.375% Up 0.25%
30-year high-balance conforming 6.625% Up 0.25%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
I. Love. Baseball.
Something long-time readers of the WR&MU are aware, but just in case wanted to affirm my affinity for America’s Past time. While disappointed (understatement) my Phillies couldn’t hit with runners on base and lost to the Mets, very happy the Dodgers are playing in the World Series in their stead. Also, very happy that they are matched up with the Yankees for the 12th time in World Series history.
The last time the two teams met in the Series was 1981, the third time in five years. That season was magical and historic for the Dodgers, and baseball. It was the season that Fernando Valenzuela made his debut in the major leagues. And what a debut it was.
Prior to Fernando became Fernandomania, there was not a lot of positive emotion in the Los Angeles Mexican and Latin American communities due to the Dodgers, and City of Los Angeles, displacing businesses and thousands of residents in Chavez Ravine and scraping their homes and stores to build Dodger Stadium. As you might have guessed, had you not known before, Chavez Ravine was a very heavily populated with Hispanic families.
Fernando’s exploits and success resulted in those communities becoming lifetime, generational, Dodger fans. As one tribute I heard said, for decades the soundtrack in Dodger Stadium was through hundreds, thousands, of transistor radios as fans listened to Vin Scully call the game (I was one when I went—I also kept a scorecard). In 1981 there was a dual soundtrack with Hall of Fame announcer Jaime Jarin providing the Spanish language broadcast.
In the spring of 1981, I was a freshman at Pitzer College in Claremont. Naturally I was following the Dodgers, and other teams, through spring training and was aware of Fernando, but not aware of what we were about to experience. My best memory is shortly before breaking training camp in Vero Beach, Florida, manager Tommy Lasorda announced his starting rotation. Pitching opening day was long time Dodger Jerry Reuss, making the rotation was Fernando. In those days teams had 5-man pitching rotations. I don’t recall where Fernando was in the rotation but because it was every fifth game fans could determine when he was pitching.
One morning my roommate Steve and I went to the Sears in Pomona, which was, and in part still is, a large Hispanic community. Old timers reading this will recall Ticketron, similar to today’s TicketMaster. Sears had a deal with Ticketron and they had a walk-up window outside the Sears store in Pomona.
We arrived around the opening of the store and there was a long line, fifteen, twenty, men in line, jeans, boots, cowboy hats on many, evident of Hispanic heritage. Most of them had the pocket Dodger season schedules handed out by Union 76. Walking by I could see some of the schedules and they had every 5th game circled, showing when Fernando would be pitching in Dodger Stadium. I have to believe that after Fernando filled in for Reuss on opening day at the last minute to start his amazing start to his career with a win and a complete game, that because that changed the rotation, many of those men, and others, were back in line at Ticketron with every fifth game circled so they could watch one of the greatest pitchers in Dodger history. Fernandomania was underway.
Very sad that Fernando will not be at Dodger Stadium tonight, my bet would be he would through out the ceremonial first pitch, as he did in the 1981 Series, beating the Yankees with a complete game. He will be there in spirit, and the tens of thousands of fans in attendance will show their appreciation with a long, and deserved, ovation for the man who change the fabric of the game in Southern California and everywhere else the game is played.


