

What is a “No Doc” loan?
Question of the week: What is a “No Doc” loan?
Answer: Back in the old days…. No documentation loans were somewhat prevalent in the market. Too prevalent in the early-2000’s which was a large factor in the mortgage and real estate industry melt down that dragged the economy into the Great Recession.
Today the number of no-doc programs available are increasing, but not to the extent of the early 2000’s, primarily because Fannie Mae and Freddie Mac are not offering the version of no-doc programs they were approving and then selling in the secondary market as the same risk as full documentation loans.
“No-doc” covers a wide set of programs that have one similarity, they do not require traditional methods of verifying an applicant’s income. In traditional, full documentation loans, borrowers are required to provide proof of income. Depending on your how you earn your income, documentation can be paystubs, W-2’s, federal tax returns, corporate tax returns, asset statements showing income from investments, award letter from Social Security Association or pension fund. Documentation that verifies you have history and consistency of income and its source.
Pricing on no-doc loans is determined as with all mortgage pricing, the two primary factors are your credit score and the loan-to-value of the mortgage (LTV is the percentage down payment from 100%; i.e. if you put down 20% the LTV is 80%). The higher your score the better the rate. The lower the LTV the better the rate.
No-doc programs have different ways of determining qualifying income to determine if you have the ability to repay your applied for mortgage.
Stated-income loans are as defined, you state your income. There is no verification of the source or amount reported to the IRS. You provide bank statements to show fund available for down payment and closing costs, typically reserves after close of escrow are require as well.
Bank statement loans look at one or two years of bank statements, either personal or business depending on if you are self-employed. The underwriting policy is to add up your deposits and then use a factor to determine your expenses, the result is qualifying income. This is a popular program for self-employed borrowers, especially if they have had a large growth in revenue, or have not yet filed tax returns for the prior year. Depending on programs, bank statement loans have better rates than stated income loans as gross income is being calculated using the deposits.
Not as prevalent, but available from a few lenders, are true no-doc loans that require large down payments, very high credit scores, and have higher rates. Often these loans require pledge of assets, such as a trust deed on another piece of real estate.
There are several no-doc loan programs currently available that offer rates that are very competitive with conventional mortgages, resulting in a substantial increase in volume for lenders.
Schedule an appointment to discuss your options if you are considering purchasing a new home or property, or refinancing an existing one and want to know the mortgage options available to you.
Have a question? Ask me!
Not nearly what was expected. Markets look forward to the first Friday of every month for job data for the prior month. With the Fed in rate cutting mode, today’s data was highly anticipated as an indicator of when and how much the Fed may next cut its benchmark rate. The consensus on Wall Street was an increase in 150,000 new jobs in September. The Department of Labor today announced that 254,000 new jobs were created last month. Not only did the September data come in much higher than expected, but the estimates for July and August. For the second month in a row the unemployment rate has declined, from 4.2% to 4.1%. A strong labor market is good for the economy, but not so good for those, the Fed, working to lower inflation. The news was not mortgage rate friendly.
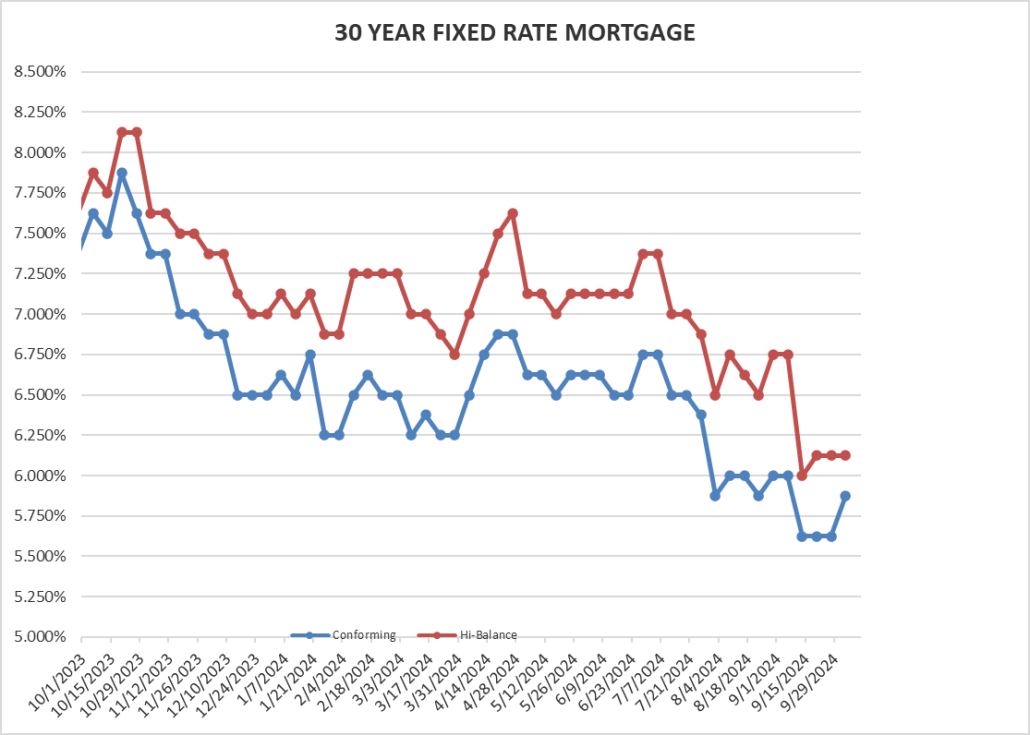
Rates for Friday October 4, 2024: The conforming rate jumps from last Friday, not only on the labor report, but also on concerns about the conflict between Israel and Iran escalating.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 5.875% Up 0.25%
30-year high-balance conforming 6.125% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
It is estimated that Hurricane Helene dropped approximately 40 trillion gallons of water across the South. That is enough water to fill Lake Tahoe, equivalent to over six hundred days of water flowing over Niagra Falls.
We have all seen the devastation to many areas, particularly western North Carolina and other parts of Appalachia. Leslie and I drove through the area two summers ago, going from Nashville to Asheville, North Carolina, where we spent several days. The town is completely unrecognizable, and we cannot imagine what certain parts of the area where we ate lunches or had a beer, must be like today.
There are many areas where people are completely isolated as rescue responders are still working to gain access and provide aid and relief.
The region needs a tremendous amount of assistance to recover, restore and rebuild their homes and communities—many of which will never be rebuilt.
Integral to these efforts, as always, is the American Red Cross. I implore you to make any size donation by clicking here.


