

How much is an area rug?
Question of the week: How much is an area rug?
Answer: Anywhere from twenty to thirty dollars to about $250,000.
Two-hundred fifty thousand dollars for an area rug? Were not buying a rare Persian carpet!
One of my favorite books to read to the girls when they were young was “If You Give a Pig a Pancake.” The story takes us through what happens when you give a pig a pancake, and syrup, she’ll get sticky and want a bath, and the bath with bubbles, the bubbles make a mess…By the end of the book the house is a mess.
Recently I told Leslie we should write a DIY book, “If you buy an area rug for your den….” The rug will make the couch, love seat and recliner look dated. The new furniture doesn’t match the book cases, end tables, entertainment center very well.
Since we are redoing the fixtures, what if we took out this wall and converted the bedroom behind it to a bar and entertainment room that opens to the patio….
Before you know it your fifty-dollar rug from Home Depot has resulted in meetings with designers and contractors and you have transitions from a little home improvement to a full-on remodel.
Our question of the week is follows up with, “how can we control a remodel?”
While it may sound cliché, the two biggest issues home remodel projects are they are always over-time and over-budget. Not all of the overs are on the contractors. Not infrequently when speaking with clients during, or after their remodel, they admit to responsibility for the extended time line and costs as once the project starts, they begin to make some changes to the original bid.
Something as small as wanting to change the hardware on drawers and cabinet, can lead to extended time to source the new materials; and while going from up twenty-dollars per piece may not seem like a lot per piece, if you need thirty pieces that adds $600. But…perhaps the appliances you chose do not match the new handles and nobs. And the cabinets need to be a bit lighter in color.
The $600 additional for nobs and handles has added $15,000 to your budget.
The above scenario is pretty close to what one of my clients went through last year during their remodel. Their kitchen, however, does look fantastic.
Before you buy the area rug, or look at new appliances, determine the very top end, non-negotiable budget.
Once your budget is established, determine how you will pay for it. The most popular, and suggested, method is to obtain a Home Equity Line of Credit (HELOC), with a limit a bit above your top end budget*. If you get a HELOC, or other financing, there must be a discussion on the cost and your monthly income and expenses, as well as plan to pay off the loan.
A general rule for your budget and bids, when meeting with contractors and they ask “what is your budget,” tell them it is about 10-15% below your top end budget. You budget $100,000, tell contractor $85,000-$90,000.
When getting bids, ask about the impact of inflation and supply on the products you will need for your remodel. Are the supplies readily available? If not, how long will they take to be available? Is the price locked in on those items when we pay our deposit for the work? If not, when will price be locked in so that we can adjust our cost expectations?
When going through the small details, make sure they match what your vision is. If possible, see the hardware and paint, tile, wood, appliance colors, patterns and designs together. Modern design programs are able to generate what your kitchen, room, will look like with the choices you made. If possible, print out pictures of from the program of different walls and areas and put them up in that room to get a bit of a feel for what it will look and feel like.
In your budget, take into consideration new furniture, appliances, floor covering, that may be need to complete your desired result.
Finally, avoid changes to your original bid for the work to be done that may result in costlier materials, hardware, rewiring or piping, etc.
*Over the years we have had my WR&MU that address HELOCs that may be of interest if you are considering a remodel, or accessing funds for any other purpose.
With the prime rate at 8.5% today, and likely to go lower in September when the Fed lowers its benchmark interest rate, the primary plan for many using HELOCs to remodel is to keep an eye on interest rates to determine when it will be advantageous to refinance their current low-rate mortgage and their HELOC into a new loan. The rate will very likely be somewhat higher than the current mortgage, however the math on payments and paying down the mortgages usually shows the new mortgage at a higher rate is more advantageous.
If you would like to discuss the options for financing your new, and very expensive, area rug, please click below to schedule a time for us to talk.
Schedule an appointment to discuss your options if you are considering purchasing a new home or property, or refinancing an existing one.
Have a question? Ask me!
Not economic news, but mortgage industry news that impacts those in process with a mortgage, or those looking to get pre-approvals. You may be aware of the major outages impacting airlines, hospitals, banks and other businesses around the world yesterday and today. Also impacted is the one of the primary software programs used by the mortgage industry. As a result, originators, processors, doc drawers, underwriters, funders are not able to access client files to move loans through the process—or fund. No one knows how long this issue will take to resolve, so for those in the process our counsel is patience, try not to stress and make sure everyone is communicating for extensions, etc as needed.
No advance notice. So said Jerome Powell, Chair of the Federal Reserve, to Congress on Monday when discussing a possible cut to the Fed’s benchmark rate and when it may occur. Not wanting to influence markets one way or the other, Powell made it clear the Fed was meeting-to-meeting as to when, and how much, it may cut rates. With that said, many who were speculating on a rate cut at the Fed’s September Federal Open Market Committee meeting (group that establishes the rates) are postulating that perhaps the cut will come at its meeting at the end of July.
Maybe putting September into play instead of July was the retail sales data for June. The total retail sales for June were flat from May’s sales. However, with gas prices down, and auto sales depressed due to a cyber attack on the industry’s primary software by a group looking for ransom, sales of non-gasoline and autos jumped. Taking away just auto sales, retail sales were up 0.4% strip away gasoline purchases as well and sales were up 0.8%. Since consumer spending is 65-70% of our economy, a large jump in sales generally does not lead to a slowing economy, slower inflation, or soft employment. All of which the Fed would like to see when lowering rates.
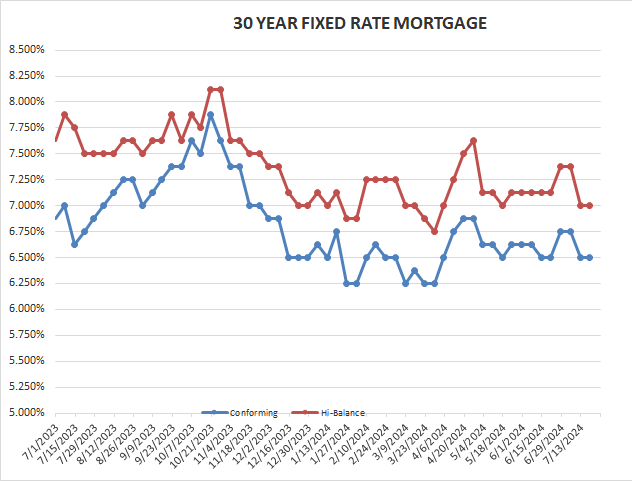
Rates for Friday July 19, 2024: Rates are flat from last Friday, the same may not be said next week as investors digest data on inflation and personal income and spending—that may be seen as creating environment for the Fed to make a move on rates.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.50% Flat
30-year high-balance conforming 7.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
A lot of famous people have passed away in the past week or so, Shelley Duvall, Richard Simmons, Dr. Ruth Westheimer, Shannon Doherty.
Of the recent passings, the one that had me going down memory lane the most was Bob Newhart dying yesterday. His original, eponymous, 1970’s television show broke some barriers, mainly the first time a husband and wife were seen sharing the same bed, and introduced him to millions of people who were not familiar with his stand-up comedy.
One of the best final episodes in television history was for his series “Newhart” in which he is an inn keeper in Vermont surrounded by bumpkins, including Darryl and his other brother Darryl. The final scene (spoiler alert 30+ years later) was Bob waking up in bed next to his co-star in his 1970’s sitcom, Suzanne Pleshette, letting us know the whole series was a dream he had. Genius comedy.
Reading his obituary in the Wall Street Journal I was amazed to learn that his first comedy album (remember those?), “The Button-Down Mind of Bob Newhart” released in 1960 was the first comedy record to be number one on the Billboard 200. It won the Grammy for best album, merely beating out Frank Sinatra, Nat “King” Cole and Harry Belafonte.
Also in 1960 he released a follow-up album, “the Button-Down Mind Strikes Back!” For two weeks both albums were one-two on the Billboard 200, a feat not accomplished again until Guns N’ Roses in 1991. At the same 3rd Annual Grammy Awards that his first record won Best Album Grammy, “Strikes Back!” won Grammys for Comedy Performance and Spoken Word.
Not the 30-second video, or reel, we have become accustomed to capturing our attention spans, here are two classic routines by Newhart, guaranteed to make you laugh:
Abe Lincoln vs. Madison Avenue
Thank you for all the laughs Bob.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


