

What is a seller credit?
Question of the week: What is a seller credit?
Answer: When purchasing a new home, the amount you need to close the transaction is more than just the down payment. In addition to the down payment there are closing costs.
Loan costs, escrow and title fees, inspection and appraisal, home owner’s insurance premium, if you are having an impound account funding taxes and insurance payments to establish the account.
Usually, the closing cost that is the largest are the “points” on the loan. Briefly, points are the cost of the loan for the interest rate you are getting, the higher the points the lower the rate and vice versa (a detailed look at points in the WR&MU from July 2021 here).
For many first-time buyers have enough for a minimum down payment, but come up short to cover all the closing costs. There are a few options to purchase the home with the amount of cash available.
More money in the form of a gift from a family member, or tapping a retirement account—such as a loan from your 401(k), are traditional methods to cover cash short falls, however if they are not available there are a couple of other options.
One is to have your lender run your ability to qualify for a higher interest rate that would reduce the amount of points you have to pay.
Another, is to put in your purchase offer having the seller credit you for a certain dollar amount to cover your closing costs.
Why would a seller do this?
To sell their home.
From data I have been looking at homes are staying on the market a bit longer than earlier in the year. Is it lack of buyers, abundance of sellers, or sellers having priced above the market for what buyers are willing to pay, or can afford.
How it works.
A home is listed for $700,000. You have about $45,000 for down payment and closing. Your down payment with 5% down is $35,000. Your estimated closing costs total about $25,000 for loan, escrow, title, impound account, etc.
You write your offer for $700,000 with request the seller pay $20,000 in closing costs.
If the seller accepts your offer, they are essentially selling the home for $680,000. They counter your offer saying they will pay the closing costs if you pay $720,000 for the home. You can counter the counter, but for simplicity of explanation, you accept the counter.
The impact for you is that your down payment has gone from $35,000 to $36,000, and your remaining closing costs are around $5000.
“But our loan payment will go up.”
True, but not significantly, if the loan rate and points are the same.
At $700,000 with 5% down with a rate of 6.75% your payment would be $4313.
At $720,000 with 5% down the payment is $4436; a difference of $23 to save $20,000.
However, you did not have the funds to close at $700,000 with 5% down, to cover the $15,000 shortage in cash you entered the transaction with (your $45,000 available less $35,000 down payment and $25,000 costs), would require you to have a higher rate to offset closing costs, about 2.5% of the loan amount. Currently, that rate is not available, if it was it would likely be close to 8%.
In essence, to purchase a home in the $700,000 price range, with $45,000, you will need financial assistance from either a gift or accessing retirement or other accounts, or having the seller contribute so they sell their home and you buy yours.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Some positive rate news the last two days, enough to counteract rates moving higher to start the week. Reminding that negative, or even not good, economic news puts pressure for rates to go lower, we had not good news yesterday and today. Yesterday GDP for the 1st quarter was revised from its initial estimate of 1.6% growth down to 1.3%. The revision was due in large part to lower the estimate of consumer spending for the quarter to 2% growth from prior estimate of spending increasing 2.5%.
Speaking of consumer spending, April’s estimate for consumer spending showed an increase of 0.2% from March, the lowest month to month increase in three months; portending that inflation is starting to strongly impact American consumers spending habits. Interesting to the spending increase is that it was lower than the increase in personal income, up 0.3% for the month, matching inflation for the month. Interesting because if incomes are higher and spending is lower the result should be an increase in savings.
The Personal Consumer Expenditures (PCE) is the preferred inflation index for the Federal Reserve. For April the PCE was up 0.3%, the core rate (the key data for the Fed as it strips out food and energy from the overall data) was up 0.2%, the lowest increase in the core rate since December. Year over year inflation was flat from April up 2.7% overall and 2.8% for the core.
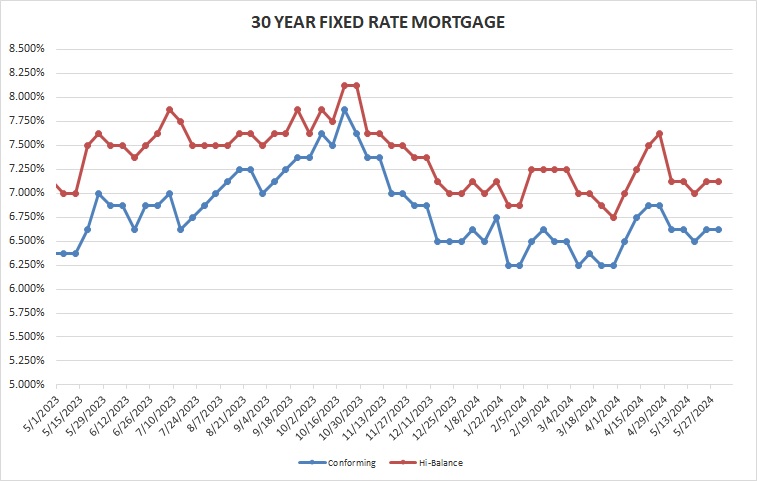
Rates for Friday May 31, 2024: The teeter then totter mortgage rate market resulted in rates being flat this Friday from last.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.625% Flat
30-year high-balance conforming 7.125% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
I felt like a teenager this week. No I wasn’t my 16-year old, heavily pimpled, scrawny kid in the middle of a one foot growth spurt in three years with a tendency to crack wise in class, self.
On Wednesday I told Leslie I could drive myself to my doctor’s appointment so the bone doc could check my progress four weeks after my right knee replacement. She said she would go along just in case I wasn’t able to safely get there and back once I had to move my foot between brake and accelerator.
I managed to make the round trip with no incidents. When we arrived home Leslie let me know I had passed my test, I could get my license and drive unaccompanied moving forward.
Able to drive a car in Southern California means freedom.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


