


Will change in real estate agent commissions impact mortgage industry?
Question of the week: Will change in real estate agent commissions impact mortgage industry?
Answer: Yes.
Before we get into the answer, some background. In November we wrote about the lawsuit that shook the real estate industry as a federal jury ruled against the National Association of Realtors and several real estate companies in an anti-trust suit that the industry over-charged sellers with listing agreements that included commissions being paid to selling agents (i.e. buyers’ agents). The ruling has shook up the industry as real estate companies come up with solutions as to how to retain an open market with buyers’ agents wanting to show other agent and company listings, get paid for representing buyers, and formulas that will satisfy both sides of the home buying transaction.
When taking a listing do agents ask sellers if they want to include compensation to the agent representing the buyer in the sales price? Do agents sign contracts with buyers to represent them at a flat fee based on how much work they will do; i.e. showing homes, writing contracts, referring other professionals such as inspectors and lenders? Or contract for percentage of sales prices?
The impact of these changes will be felt in a few different areas by those of us on the front line of the mortgage industry—loan originators who are with clients from pre-qualification through closing.
At the beginning of a transaction, the pre-qualification and pre-approval processes, the unknown of whether an agent will be paid to represent a buyer, and if so how and how much, impacts the results for the client of sales price and loan amount.
In December we covered the challenge of cash. If a buyer has to pay their agent themselves, the seller will not pay the buyer’s agent from sale proceeds, how do we account for paying the buyer’s agent by the buyer? Likely by reducing the amount of down payment, thereby increasing the loan amount, changing the debt-to-income ratios due to a higher payment, possibly adding mortgage insurance.
Likely two scenarios will be prepared, one if a seller will pay the selling agent (representing buyer, the agent who sells the home) through sales price, either increasing the price to accommodate the commission or accepting the agreement based on list price; and if the seller will not be paying commissions. Of course, the buyer may wish to have a higher loan amount and pay the commission themselves to have a lower sales price.
Buyers who have little cash to work with for their purchase, typical buyers using FHA with 3.5% down payment requirement, will be harder pressed to pay an agent as they simply do not have the cash to manipulate a down payment reduction to include an agent commission they will be paying.
More scenarios, more unknowns until a buyer finds a home, writes an offer, and the offer is accepted, leads to more up-front work for the mortgage originator to ensure that when that offer is written, either with the buyer paying their agent or it being included in the sales price, if accepted will close with a mortgage we said could be closed.
Depending on how the buyer decides to approach the use of an agent to represent them, could increase the responsibility of the mortgage professional through the transaction.
There is no rule, or law, the buyers have to have an agent to represent them in the purchase of their home. It is recommended, but not required. With the ability to search for homes on websites, many buyers are already finding homes they want to see and possibly purchase and then letting their agent know. Or they can set an appointment with the listing agent to see the home, and then write their own offer, negotiate for the price and terms and sign an agreement with the listing agent that they are not being represented by the agent and hold them harmless for any issues that come up.
Or they may pay an agent to write the offer and negotiate for them for a flat fee and then end the contractual relationship.
If we are working with a buyer that does not have an agent representing them the buyer, will come to us to with all the issues they would have worked with an agent to resolve. Who to use for a home inspection? What to do with the results of the home inspection? How can we get the seller to repair, or pay for repairs, that may be needed? Can you explain the escrow instructions? What is this title report we received? Should we close when the final walk-through shows damage to floor covering that was hidden by furniture?
There are a myriad of questions and issues that can, and do, come up that are typically handled by agents that will not be asked of the buyer’s lender. If we are acting ipso facto as the buyer’s agent, can we charge more for the extra responsibility? No.
Mortgage origination compensation laws were enacted following the mortgage and real estate market melt-down that limited the amount of compensation that could be charged. As well, there can be no change in compensation after initial disclosure of what the mortgage originator will be paid for the transaction.
As well, mortgage originators cannot be paid in advance for their services. No contract with an upfront retainer to be credited if and when a transaction closes, one strategy some agents may use for buyers. No compensation for pre-transaction consulting and strategy can be paid to a mortgage company or lender.
Depending on how the buyer’s agent compensation payment is applied to each transaction, the mortgage originator will be impacted from start to finish in some way.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Kaboom! Not referencing the earthquake that hit this morning that rattled buildings and nerves throughout New York City and beyond, but the “blowout” as the Wall Street Journal labelled today’s job report for March from the Labor Department. The consensus from WSJ reporters and sources was the economy adding around 200,000 jobs for the month; they were off by 50% as the data showed 303,000 additional workers getting paid for the month. It was the biggest increase in jobs for a month since last May. The data was not nice, not nice at all, for mortgage rates as the Fed watches the labor market as closely as inflation when determining what to do with its benchmark interest rate.
A bit nice for rates, was salary growth was 0.3% for the month and 4.1% from last March. The annual pay increase was the lowest year-over-year since June of 2021.
If, when, how much, are the questions regarding the Fed’s stated intent to lower its benchmark rate in 2024. Today’s data likely pushes the first rate cut, if there is one, later into the year.
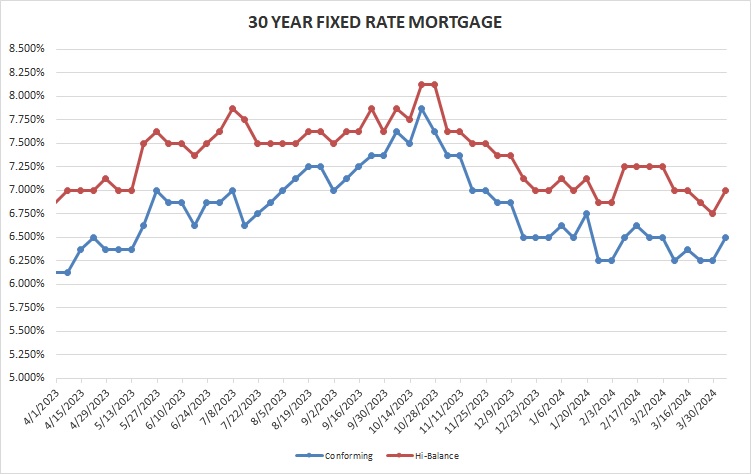
Rates for Friday April 5, 2024: After holding the course after last week’s economic data showing a strong economy, investors could not hold back on today’s news and rates climb back to where they were five weeks ago.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.50% Up 0.25%
30-year high-balance conforming 7.00% Up 0.25%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Anyone else become a women’s college basketball fan, or start to somewhat follow, this year in large part, full part?, due to Caitlin Clark at Iowa? She is trying to win her first national championship and certainly has much of the nation rooting for her and the Hawkeyes.
Under reported is that there are two chances for a college to have both their men’s and women’s basketball teams win the championship. This has only happened twice, in 2004 and 2014, when the University of Connecticut men’s and women’s teams both cut down the nets.
UConn has a chance to accomplish this again, the men’s team is the big favorite to win the men’s championship, the women’s team is not favored to win but there’s always a chance. Joining UConn with the opportunity to pull off the double championship is North Carolina State. The Wolfpack men won one of the most memorable championships in 1983, their only title, and the women’s team has never been to a NCAA final game much less won a title.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


