

What is happening in the housing market?
Question of the week: What is happening in the housing market?
Answer: This week’s question is a continuation/follow-up of three prior questions of the week:
How much more does it cost to buy a home this year?
When will we know when it is time to buy a home?
The first and last questions in this list dealt with home values and interest rates, which determine the cost side of the affordability equation; the other side of the equation is buyer’s qualifying price and mortgage amount.
This week we will present some housing data for February supplied by the California Association of Realtors.
Overall, February was a very good month for home sellers in California.
Statewide the median home price increased 2.2% from January and 9.7% from February 2022. The median price in February across the state was $806,490 compared to $789,480 in January and 735,300 in 2023. Those employed in real estate industries were happy as well with total sales increasing 12.8% for the month and up 1.3% for the year.
Locally, Los Angeles County home sellers as a group were a little less happy than those who sold in January and a lot happier than those who sold a year previously. The $817,100 median sales price was down 1.9% from January’s median of $833,000, but up 12.4% from last February. Sales were up significantly month over month, plus 8.4%, and year over year, up 6.3%.
In Orange County the median price reached $1.35 million last month, up from $1.32 million (2.3% higher) and $1.159 million (up 16.5%) from last February. Sales in the county surged 23.6% from January and 12.4% year over year.
With rates lower this February from January, and about the same as last February, even with the lower rate, because of the median price rise in Orange County buyers obtaining mortgages had higher costs and payments, a lot more given the price increases.
Last month’s Los Angeles County home buyers faired better on costs and payments than those who bought the previous month; but like the OC, those who waited a year to buy paid a lot more due to the increase in values.
Does the decline in prices in February mean we are heading to a decline in home values? No. One month doesn’t a cycle make. With inventory still at a somewhat low 3-month supply and the median days on the market low at 23 days, there is still an imbalance in the market favoring sellers.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Breath in and hold your breath…you may now breath out. That was what I heard about 5 times this morning during a CT scan for my next knee replacement. It is also what markets did this week ahead of the news from the Federal Reserve’s Open Market Committee (FOMC) meeting. The exhale was a big sigh of relief as the news was positive, double positive, for lower rates.
While not lowering its benchmark rate at the meeting, Fed Chair Jerome Powell did announce the Fed still expects to lower the rate three times this year. As well, the second positive from the meeting, was that the Fed would slow down its “unwinding” of its balance sheet; in layman’s terms, slow down the selling of Treasury and mortgage debt that it accumulated during its quantitative easing period during and after the pandemic (which increased liquidity causing rates to be very, very low). By not flooding the market with the rate baring instruments it owns, the Fed is reducing market supply, with increases prices on Treasury and mortgage bonds and securities, which lowers rates. If the Fed continued aggressively selling these holdings the effect is to put upward pressure on rates.
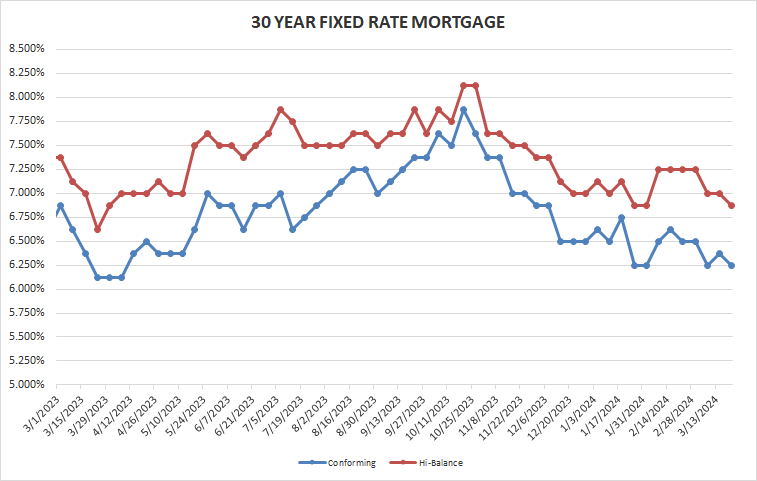
Rates for Friday March 22, 2024: Positive news from the Fed pushed rates lower from last Friday. As a result, rates are at the lowest they have been this year, and approaching rates last seen in March of last year.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.25% Down 0.125%
30-year high-balance conforming 6.875% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Cinderellas and powerhouses collide. It is that time of year when we find out that Golden Grizzlies can topple Wildcats and Bears maul Raiders.
Some friends and I started our first pool for the NCAA Men’s Basketball Tournament in 1982 when we were in college (for those who remember, the title game that year between the Hoyas and Tar Heels began with Patrick Ewing being called for goal tending on several shots by the Heels to start the game. It ended with Michael Jordan hitting winning shot with 17 seconds left, then Georgetown’s Freddie Brown mistakenly sending a pass to North Carolina’s James Worthy.).
I organized the pool, and 46 years later am still the organizer and of the seven players in our pool, three of us were in that first pool in 1982; five of us have been in it since 1985. We have gone from mailing picks that had to be postmarked the day before the tourney started, to fax machines, to emailing brackets, to texting pictures of our pics.
Our story is not that unique, as the NCCA tournament keeps friends in touch through the years, some gathering in person to watch the first rounds, others via email and zoom, to brag about some picks and get razzed for others.
While the tournament is known for many great upsets (see Oakland Golden Grizzlies beating the Kentucky Wildcats) and last minute shots to win games; what it is really about for most is that chance to get together once a year.
As soon as I get this sent, I’ll call my friend Laird who I met as a teammate on the lacrosse team, two years ahead me in school, and living in Dallas. I haven’t seen him since 1985, but we talk every year on this day. It always goes, “Hey LJ” “Hey DC”…..
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


