

How much more does it cost to buy a home this year?
Question of the Week: How much more is it to buy a home this year?
Answer: From the end of December in 2022 to end of December 2023 it will cost you 6.42% more to buy the median home in California if you are paying cash, and depending on various factors, 10.71% if using a mortgage.
Let’s crunch data supplied by the California Association of Realtors in their monthly Housing Market Update.
Median prices increased in all but five of California’s twenty-eight counties. With apologies to Lake and Calaveras Counties, the most prominent county with a year-to-year price drop is San Francisco, where the median price dropped 7.3%, over $110,000. Also notable is the 10.6% drop for Santa Cruz prices.
Statewide the media price finished the year with the median price dropping 0.3% from November, to $819,740; which was up 6.4% from December 2022’s median price of $770,490.
More local to most of the readers of the WR&MU, Los Angeles County’s median price of $853,340 was off 5% from November, but up 6.7% from last December’s $799,670 median. Orange County has the statistical anomaly of zero percent change in November’s $1.3 million median price in December; the December 2023 median is 14.9% higher than the prior year’s median $1,131,760, an almost $170,000 gain in twelve months.
Total sales are improving in various areas of the state. In Southern California, sales in LA County were up 3% from November, but down 5% from the start of the year. Orange County saw sales decline 8.1% for the month, contributing to the flat median price from month-to-month, and were off 7.6% for the year.
While sales measured on an annual basis declined for the thirtieth straight month after peaking during the pandemic in June 2021, the rate of decline is slowing. Does this portend a reversal in sales volume? Perhaps, but after so many months of declining sales it will not take too many to move into positive sales territory.
Where have the gains in prices been in the state? Higher price ranges, $1 million and higher, increased their share of the total market to 29% of all sales, while the lower end of the market, prices up to $499,999, saw market share fall to 28%. The middle market of $500,000 to $999,999 remained stable with 43% of market share. This growth in the upper price range and reduction in the lower price range is seen in the increase in the median price.
As for total sales volume in the state, the Southern California (LA, Orange, San Bernardino, Riverside and San Diego Counties) has unsold inventory of only 2.6 months, with average days on the market of 26 days. The tight SoCal market is seen in the sales-to-list price at 99.7% (meaning if home listed for $1 million the sale price would be $997,000).
Almost one out of every two homes sold in the state, 46%, were in the Southern California market.
Can you answer the question already? Okay, okay.
Rounding the median prices to the nearest $500, using the rates posted in the WR&MU for the last Friday in December 2022 and 2023 here is a look at the difference in down payment, monthly payment and income needed to qualify (note, using 35% DTI, depending on many factors the amount needed to qualify may be higher or lower—this is for comparative purposes only).
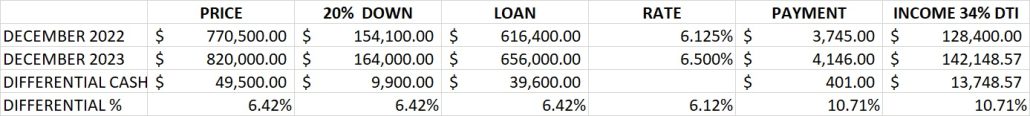
As you can see, while the median price was up 6.42%, the 30-year fixed rate increased 6.12%, increasing the payment and income needed to qualify by 10.71%. The Consumer Price Index in December was 3.4% on an annualized basis, less than a third of the increase in cost to purchase a home in California—let’s call it the housing inflation index—and the cost to purchase with a mortgage is more than twice the increase in average wages and salaries.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Not so fast…Federal Reserve Chairman Jerome Powell held a press conference on Wednesday after a Fed meeting and stunned the markets who were expecting the Chair to say something along the lines of “all signs point to lowering rates in March…”
Instead, Powell threw cold water on the low-rate fire.
Rather than paraphrase Mr. Powell, here is part of his statement, “Based on the meeting today, I would tell you that I don’t think it is likely that the committee will reach a level of confidence by the time of the March meeting to identify March as the time to do that…(lower rates).”
After several months of anticipation for the Fed to lower rates at the March meeting of its Federal Open Market Committee Meeting, the now likely pause in that action had markets reacting negatively.
Maxwell Smart…missed it by that much. Leading into today’s January job report from the Labor Department the consensus on Wall Street and amongst economists was that job growth would be 185,000 new jobs. The report this morning showed that there were 353,000 jobs added to the economy in January, missing the estimate by more than I can remember the estimate being missed. The number of new hires was the largest in over a year, adding to the strong labor market data was the revision of the December job report upward from 216,000 new jobs to 333,000.
One more factor showing the job market is incredibly strong was the wage report showing workers are getting paid 4.3% more in January 2024 than in January 2023, far outpacing inflation.
Not good news for interest rates from the Labor Department. The Fed looks very closely at the labor market when determining what to do with their benchmark interest rate; today’s data suggests they might be closer to increasing the rate than lowering it.
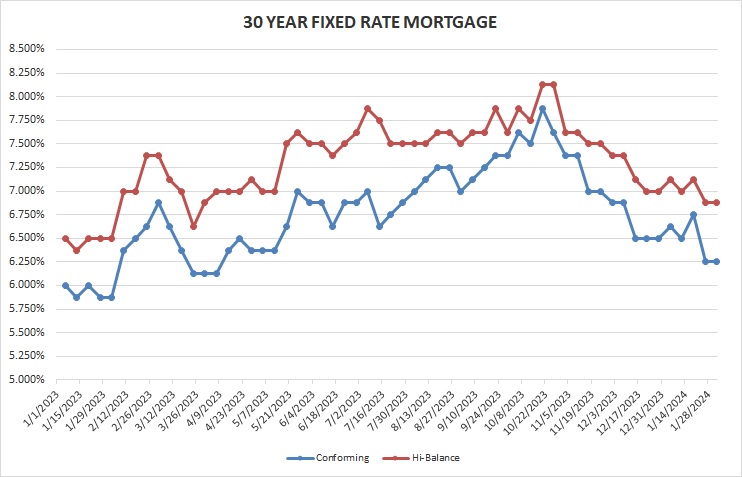
Rates for Friday February 2, 2024: As expected, bond markets reacted significantly today following the jobs report, with prices dropping and yields (rates) rising. However, yesterday the markets were very positive pushing rates lower. The result of the down then up in rates is that we are currently flat from last Friday.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.25% Flat
30-year high-balance conforming 6.875% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Growing up in areas of the country that experienced the fullness of each season, Groundhog Day meant something. Some February 2nds we would come in from shoveling the driveway so Dad could get out to the train station to see if we would be doing the same in April, or if we would be mowing the yard. Despite our current weather of “atmospheric rivers,” what Punxsutawney Phil does on the second day of the second month each day is pretty irrelevant to whether our weather is expected to be more winter or more spring for the next six weeks…we can almost guarantee that we will be able to entertain outside in the middle of March.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


