

Should we transfer property to our children this year?
Question of the Week: Should we transfer property to our children this year?
Answer: Perhaps. If not this year then possibly next.
In January 2018 the Tax Cuts and Jobs Act took effect. The Act had a tremendous on the tax codes for individuals, businesses, corporations, and estates.
One of the largest changes was the increase in the value of an estate that can be transferred tax-free as inheritance from $5.49 million in 2017 to $11.18 million in 2018. For 2024 the amount is $13.61 million.
The 2018 tax act had a sunset clause of December 31, 2025 for most of the provisions, including the increase in the value of estates that could be transferred as inheritance.
Unless Washington extends the current tax rates, the inheritance threshold will return to pre-2018 levels, $5.59 million.
I am not a tax preparer, CPA or estate attorney. Please consult with your tax and estate professionals before engaging in any transfers or sale of property that may have tax consequences.
Gifting an early inheritance to beneficiary(s) is a way to transfer assets while you are still living, and avoid paying taxes. A gift of assets in 2024 or 2025 will count against the $13.61 million threshold before inheritance taxes are payable. Should the taxable threshold drop in 2025, or the future, the threshold in the year you made the transfer takes precedent.
Because of the uncertainty with the tax code limits in 2026 for a myriad of taxable events, many families are consulting with their tax professionals and attorneys to determine if they should make early transfer of assets part of their 2024 financial objectives.
With the tremendous increase in property values that has resulted in many holding onto several properties to avoid capital gains taxes, many waiting to have the properties transfer to their children to avoid the capital gains pass the assets through via their estates.
In Southern California, it does not take too many properties to reach the $5.59 million possible inheritance threshold that may return in 2026 and beyond.
Consider a primary residence valued at $1.5 million, the first home you purchased in 1994 for $300,000 that is now worth $1.2 million, a duplex you purchased during the 1999 downturn for $550,000 now worth $1.8 million, the vacation home in the mountains you inherited from your parents in 2000, then valued at $250,000 that is worth $900,000, and the condo in the desert you purchased in 2009 when prices plummeted for $150,000 that is now worth $500,000.
These properties are generating income for you, and have expenses, and are also valued at over $5.59 million—with the values rising.
Presuming values in the region continue to climb through 2025, the total values may approach $6.2 million by the end of next year. If you still have these properties on January 1, 2025 and the inheritance threshold reverts to 2017 levels, your estate has taxable value.
If you were to transfer one or two, properties to your children, the value of the properties can be exempt from inheritance taxes.
It is important to note however, that the tax basis for any properties transferred early will likely have the same tax basis as they currently have; i.e. for the property purchased in 1994 will be $300,000. Whereas when the properties are transferred at death have a step-up in basis to the value at time of death.
One strategy to minimize, but not eliminate, taxes, would be to sell property in 2024, pay the capital gains taxes on the property* and then transfer the net proceeds to your children as an early inheritance.
*Consider the federal capital gains taxes currently in place are as low as they are ever likely to be, 15% if your joint income is $94,051-$583,750.
Federal estate tax rates are considerably higher than capital gains taxes, as high as 40% on amounts over $1 million.
To put some possible numbers together:
You sell your first home you purchased in 1994 for $300,000 at a price of $1.2 million, after eligible deductions your capital gains on the property are $750,000. Federal capital gains taxes are 15%, $112,500, California capital gains taxes are calculated as income, another $74,000, for a total of $186,000 in taxes. Your next proceeds are $563,500 you can distribute to your children tax free.
Consider you pass away in 2026 and the inheritance threshold is $5.59 million and your properties are worth $6.3 million. Federal taxes on the $710,000 over the $5.59 million inheritance threshold is $233,500.
By selling the property in 2024 or 2025, then transferring the net proceeds to your children in 2024, you can likely save close to $50,000 in taxes, provide your children with a liquid asset, and reduce the potential inheritance tax on your estate they will have to pay in the future.
That is one strategy, another to explore is transferring property to children as early inheritance and have them sell the property and have them pay capitol gains, which may be lower if gains are split between two or more children.
Once again, I am not a tax or estate law professional. These are examples for possible strategies to discuss with your advisors for 2024 planning.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Consumer spending is approximately 65-70% of our economy, and retail spending is approximately one-third of consumer spending. Because of this, retail sales data is a critical economic data point impacting mortgage rates. In December retails sales rose 0.6% from November, which had a strong increase of 0.3% from October. For the year, retail sales were up 5.6% from 2022; double the rate of inflation. The news is mortgage rate unfriendly as the ringing cash registers reflect a strong and growing economy, no slack on pressure on prices, a need for a strong labor market in the retail sector which can spread to other sectors. All of these factors support the Fed pushing out any rate cuts to their benchmark interest rate. The consensus has been a cut in March, however if next week’s GDP data show a strong 4th quarter to finish 2023, the initial rate cut may not be until the summer.
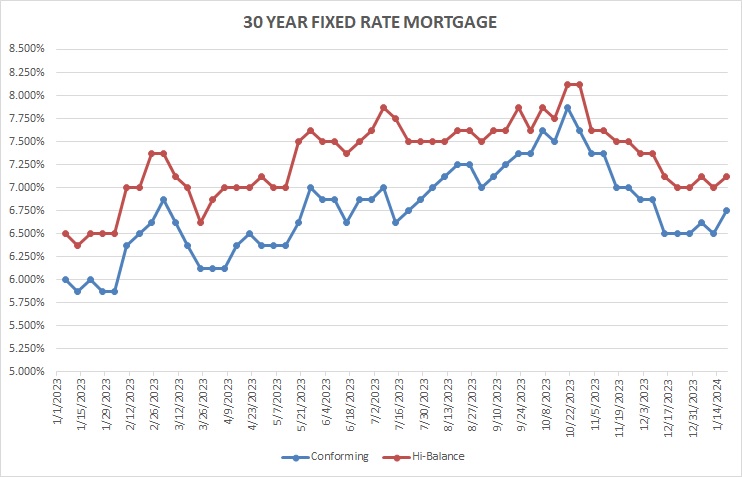
Rates for Friday January 19, 2024: After seeing the 30-year conforming fixed rate at 6.50% for four of the last five weeks, this Friday the rate jumps to its highest since early December.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.75% Up 0.25%
30-year high-balance conforming 7.125% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
It is Empty-Nest Day in the Smith household as our youngest heads back to New York to start her senior year after four weeks R&R at home. Always a bit tough for the SoCal kids who leave the sunny moderate temperature December-January weather for snow and freezing temps, and no more In-N-Out until they return.
We have a bit of a cushion in the empty-nesting as tomorrow we head to San Diego for the day to see our oldest who is there for a conference and flying back to Boston tomorrow evening.
Then it is back to Leslie, the dog, and I watching Jeopardy! and shows we want to watch.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


