

How do we deal with collections on our credit report?
Question of the week: What do we do with wrong items on credit report?
Answer: Like most questions of the week, this one has percolated naturally over the past several weeks as we have had clients with mistakes on their credit reports.
Most typically errant reporting is from collection companies, which compounds the error as collections push credit scores down significantly.
By far the source for most collection accounts we see are for unpaid medical bills. This is because while many credit card companies are willing to charge off unpaid balances due to the volume, and profit from high interest rates, of business, doctors and others in medical fields do not have either.
A number of the collections we see on reports are legitimately reporting, our client had some type of medical situation and from the event and several different medical service providers, billing to insurance, insurance denials or partial coverage of charges, multiple statements in the mail, confusing communications from insurance companies, bills that look like junk mail, and a myriad of other factors, not the least of which maybe stress from the medical event and recovery, it is not uncommon for a bill, or two, to slip through the cracks.
What is the process by which you end up with a collection account on your credit report?
I am having knee replacement surgery in the near future. We have PPO coverage with major national insurance company. Obviously, I have appointments with the orthopedic surgeon performing the surgery. A CT scan is necessary, that is another entity. The CT scan is read by another entity. It is required I have pre-operation clearance from primary care physician, and since I have been treated for high blood pressure for several years, with my cardiologist. That is two more entities.
When it is time for the surgery I will have to go to hospital or surgery center, another entity. An anesthesiologist will loop my up for the surgery, another entity. A medical device company will provide the parts, another entity.
A ninth entity enters the billing when I go to rehab.
Some of these medical billers will be in-network, a few may be out of network.
Beginning about a month after the surgery I will begin to receive numerous emails from our insurance company regarding claims coming in from the different medical providers, and bills from providers for amounts not covered, or not yet paid, by the insurance company.
Further confusing matters, some of the bills may be coming from billing companies, therefore the name on return section of the envelope will not be familiar and look like the multiple pieces of mail we get weekly from solicitors for everything from windows to insurance to solar to non-profits.
Pretty easy for a $250 bill for hospital’s recovery room personnel and pharmaceuticals to get missed.
Ideally, that biller will send an initial bill showing the amount of the services, the amount covered/not covered by our insurance company and the amount I need to pay. After 30-days they will send another bill. After 60-days they should send a “you’re 60-days late.” At 90-days they should send a “if you don’t pay us, we are selling your account to collections.”
I still don’t pay the bill as I think insurance will take care of it as they say they are still researching the bill. Or, in a different scenario I paid the bill and it wasn’t recorded. Still a third scenario, the balance does not exist and no amount should have been sent to collection.
The hospital sells my bill, with many others, to a collection company that in reviewing accounts offers $0.60 on the dollar for the accounts. The hospital closes my account with them for $150.00 from collection company.
The collection company sends communication to me that they have my account and that I owe them $250 plus a transaction fee and interest is being charged at 12% until paid.
At this point, if I contact them immediately there is a good chance I can pay them before the account is reported to the credit bureaus.
What happens not infrequently is there is an error in the records, or in inputting records, and my address, phone, email, are not correct and I never know the account has been sold to a collection company as any correspondence is going to the wrong place.
What is often more likely when I do not receive communication from the collection agency is that they do not send out any letters or emails, or make any calls, notifying me of the account and make an attempt to collect. In this case I do not know I have a collection account until I apply for a mortgage and am told my credit score that I think should be in the high 700’s is in the mid-600’s.
I don’t get mad. I don’t ignore all that has happened above, and pretend it has happened to someone else. With the exception of the part where the account is on my credit report because the hospital crossed records and sent my information instead of someone else’s.
Now what can I do? I never knew I had a collection and it is on my credit report. Whether the account is mine or someone else’s, it is on my credit report and I don’t want the rate I will get with a 670 score when I would otherwise have a 770 score.
First and foremost, I contact the collection company, contact information should be on your credit report. When speaking with them I take a conciliatory tone, the person on the other end of the line takes a lot of abuse from people mad about their accounts, and credit reports (I know, for a period of my life I took these calls with a finance company).
In my call I ascertain if the balance being reported as owed is legitimate, that it was a bill that you did not pay.
Keeping in mind that my objective is to remove the account from my credit records, if there is a balance due, I do not negotiate. Rather, I indicate I can pay the full amount due immediately, however I would like letter indicating not only is account paid in full but that it should not have been on my credit report. The company representative will likely push back that they cannot remove the record from the credit bureaus, this is not true, they can.
If they have sent me letters, had calls, etc with me, there is a slim chance that they will remove the account. However, if they say they have communicated with me, I ask them to provide evidence of the communications. If they cannot provide them, I can push hard, but nicely, to pay and remove the account from my credit records.
If the account was posted in error on my report, the issue should be quickly resolved with the company indicating they will remove the account from my credit records.
When anyone from the collection company says they will remove the account from credit records I get a name, extension, email, all the information from that person, note the time and date of the call, and request in writing that they are removing the record.
If I feel I am going in circles with my initial contact, I ask for a supervisor, “I’m sorry but I feel like we are going in circles, can I please speak with a supervisor.”
If the account is legitimately on my credit record, and they will not remove it, I pay off the balance. A paid collection on my credit report, while debilitating to my score, is less so than an unpaid account. As well, in the future I can continue to contest the account and it may get removed sooner than later.
Important points if trying to get a derogatory reporting removed from your credit report:
- Be polite, it can be tough as you are likely frustrated and possibly angry, use a calm voice, thank them for their assistance, create aura where they want to help you
- Be ready to pay, it is cheaper in the long run to pay an account than to pay higher interest rates for years because you leave the account outstanding
- Get contact information so the credit bureaus can confirm the agreement to remove the account when they call to confirm the account should not be on their reports
The top instances in order of frequency in which we see result in derogatory reporting on credit reports are:
- Medical collections from emergency room treatment, surgeries, non-primary person on health insurance (spouse, child) receiving medical care
- Credit derogatory reporting for late payments or charge offs as a result of marital/partner separation or divorce as one spouse/partner who is supposedly responsible for payments due not for various reasons, including just to harm the other person’s credit
- Student loan consolidations, especially from federal student loans through Sallie Mae, are not accurately reported as paid off, then report late payments as no payments being made to servicer after the consolidation
- For younger adults, utility, cable, or phone company collections for shared living space where individual co-signed for service(s) for an apartment or house and other roommate was paying the bills. After everyone moved out the last bill or two is not paid and results in collection account
Finally, and most importantly, monitor your credit reports! All of the credit bureaus must provide one free report per year to consumers, take advantage of this. As well, most banks and credit card companies offer credit score checks at no cost so you can see if your score suddenly plummets—triggering a check on your report to see why so you can resolve the issue as soon as possible.
The Consumer Financial Protection Bureau has enacted regulations on collection companies and credit bureaus to lessen the amount of misreporting on consumer accounts, however the misreporting has not been eliminated. As a resort if you are feeling that you are not being treated honestly and fairly you may contact the CFPB to find out what your rights are and what the credit or collection company must due to solve your dispute.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
End of the month economic data dump for us numbers nerds occurred this week. Quick summary:
- GDP for the 2nd quarter had its final revision, and it wasn’t revised, growth for the quarter was 2.1%. Data is mortgage rate neutral
- GDP forecast for the 3rd quarter is very strong growth of 4% or more. Forecast is mortgage rate negative
- Consumer spending data for August presented some mixed news. Overall spending increased 0.4% for the month, fairly strong and mortgage rate negative. However, most of the increase was due to gas and other energy related costs, taking considering the jump in gas prices lessened what would be a negative impact on rates
- Personal income rose 0.4% in August, keeping pace with inflation, the news is mortgage rate neutral
- Personal Consumption Expenditure (PCE) price index is the primary inflation gauge for the Federal Reserve when deciding what to do with its benchmark interest rate. In August PCE increased 0.4%, the highest in seven months. Year over year the PCE increased from 3.4% to 3.5%. This data is mortgage rate negative. However, he “core” PCE rate strips gas and food from the data and is the inflation number the Fed looks to for gauging inflation. The core PCE rate was a benign 0.1% increase in August and year over year core PCE dropped from 4.3% in July to 3.9% in August, the lowest in 2-years, this data is mortgage rate friendly
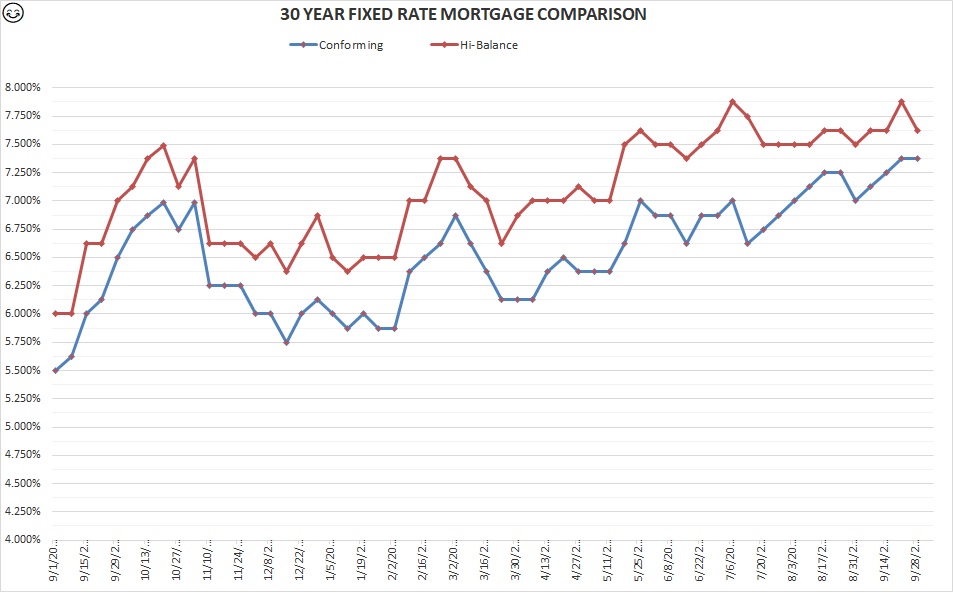
Rates for Friday September 29, 2023: A bouncy week for mortgage rates that result in the conforming rate being flat from last Friday, the high-balance rate declined the amount of last week’s increase for technical reasons.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 7.375% Flat
30-year high-balance conforming 7.625% Down 0.25%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Arrivederci!
The WR&MU will take a hiatus for the next two weeks as Leslie and I are headed to Italy for an extended vacation—the longest vacation we have taken since we got married in 1994.
Our biggest stress point was our dog, Sammy. Sammy was a rescue who doesn’t trust people not in his family. He loves going to his play-dates at Go Fetch in Long Beach, and we have boarded him there for prior trips. However, two weeks is too long to have him at the day-care. Thankfully one of our daughter’s close friends, who has stayed over many nights since high school, scored an A+ Labor Day weekend when Leslie and I went to San Diego for our anniversary and will be staying at our home.
When we took trips when our daughters were little we never stressed about leaving them as we knew one of the aunts would step up (fight over?) staying with them or having the girls and dog at the time stay with them.
Is it bad we stressed more about our dog for this trip than we ever stressed over our young daughters?
Have a great (few) week(s),
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


