

What’s going on with rates?
Question of the week: What’s going on with rates?
Answer: The are climbing with momentum.
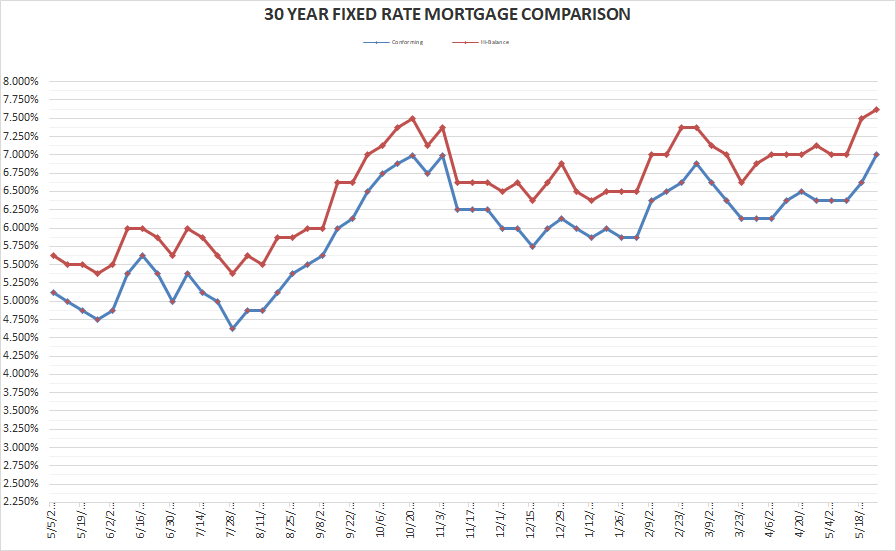
Conforming 30- year rates have increased over the past few weeks to the highest they have been since they peaked in November of last year, the high-balance rate is the highest it has been in the history of my rate charts going back to 2005.
A confluence of data, comments, and non-action have converged to push rates higher. A quick look at these factors.
Economic data for April shows that the Federal Reserve’s efforts to push inflation down to its 2.00% target are not working.
Consumer spending is estimated to be 65-70% of our economy. For inflation to drop our economy needs to slow down. For this to happen consumers need to slow their purchasing of goods and services.
In April consumer spending was up 0.8% from March, doubling expectations of a 0.4% increase. Increase purchases of a wide range of goods and services accounted for the increase, with automobiles seeing a large jump from the prior month. The increase is the largest in 3-months. Past increases in consumer spending data were mostly in line with inflation, however the April jump in ringing cash registers far outpaced the increases in prices for the month.
Wages increased 0.4% in the month, in line with inflation, supporting the April spending spree. Consumers have enough confidence in the economic future to dip into their savings for buying goods and services as evidenced by the personal savings rate declining for the first time in a year.
With the unemployment rate stuck at its lowest rate in decades, wages increasing, and employers still trying to fill vacancies, the economy has a very strong labor market. Fueling consumer confidence and spending.
The personal consumption index (PCE) is a measure of inflation that is the preferred gauge of prices for the Federal Reserve. Like the consumer spending data, PCE for April exceeded expectations, showing prices increasing 0.4% from March. Year over year the PCE has increased from 4.2% to 4.4%.
The “core rate” of inflation, taking energy and food prices out of the data, has been fixed in a tight range between four and five percent since the fall. This despite the Federal Reserve increasing its bench mark interest from a range of 2.25-2.50% in September to 5.00-5.25% today.
Despite significantly higher interest rates and rising prices, consumers are not following the traditional economic models of higher rates dampening inflation. Labor markets are also ignoring the economic models ingrained in several generations of economists, as higher borrowing costs and costs for labor and the goods and services they need to effectively run their businesses have not stopped them from hiring more employees and paying higher wages.
Earlier in the week minutes from the most recent meeting of the Federal Reserve’s Open Market Committee (FOMC) were released. The FOMC is the group that determines whether the Fed will increase rates or not. The minutes showed that there was a split among members to raise its benchmark rate in May or take a break from rate increases.
This news was positive for rates, but was negated by the economic data showing that there is no downward pressure on prices.
Underlying all this technical “stuff,” are the negotiations between the White House and Democrats and the Republican majority in the House of Representatives to increase the debt limit before June 1st, that is the date at which the Treasury says the American government will run out of money to pay its “bills,” including social security benefits, salaries to employees, payments to contractors providing goods and services, and possibly interest to debt holders.
Over the weekend one side or the other will blink, or perhaps both sides will wink, a one-eyed blink, and a deal will be made that will pass both houses of Congress and be signed by the President. That is what happens historically, both sides thump and roar and gin up their bases for donations and support and then quietly come to an agreement that upsets each of their most ardent supporters.
This year is a bit different as the wings on the far ideological side of each party have more seats, i.e. power, within both the Republican and Democratic parties. These factions have threatened to not vote for, i.e. kill, any agreement made that compromises their positions on government spending, whether if be less or more respectively.
Uncertainty, a long holiday weekend, a much stronger than expected economy, and broken economic models, have converged to show investors lower rates are not on the horizon.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Rates for Friday May 26, 2023 Perhaps we will see a floating down of rates next week as investors put money back into markets following the holiday weekend, and if a debt ceiling deal is reached in Washington. The first word in that sentence is the operative word.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 7.00% Up 0.375%
30-year high-balance conforming 7.625% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
We are enjoying the long weekend with a bit of a family reunion as Leslie and I, my brother and his wife, have travelled to Boise to stay with our older sister to celebrate her 65th birthday, and to spend time together.
On Monday our nation recognizes and expresses gratitude for the more than one million servicemen and women who have died while serving in the different branches of our military. Please take time from your gatherings with family and friends to pay tribute and honor these brave people who have sacrificed for our freedom.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


