

We are getting divorced, what our options for our home?
Question of the week: We are getting divorced, what are options for our home?
Answer: Unfortunately, or in some relationships fortunately, every year I work with several clients who are getting, or going through, a divorce. Not surprisingly the easiest transactions in a divorce are those where both parties are cooperative and focused on finalizing all the details of their agreement and have the divorce be finished so they can move on.
If the couple own a home, or other asset, it is likely the largest asset they own that needs to be divided. As such, it can be the most contentious and emotional point of negotiation between the spouses and/or their attorneys.
The quicker both parties can agree on how the equity in their home will be divided the easier, and cheaper, it will be. If one, or both parties, dig in and contest offers from the other party regarding the disposition of their home, the more expensive their divorce will be as the attorneys billable hours increase as they present offers and counter-offers, or file motions for the judge to decide.
There are two primary options for the disposition of a couple’s home when getting divorced.
For our purposes I will use Ann and Bill as the divorcing spouses in all examples below.
One party retains the home
Ann wants to retain the home. There are two ways this typically happens.
If there are sufficient assets in various accounts, checking, savings, investments, company, other real estate, retirement funds, Bill may agree to transfer his interest in the home to Ann in exchange for retaining other assets equal to his portion of the equity in the home.
If this option is not possible, Ann might be able to refinance and pull out enough equity to pay-out Bill in exchange for him transferring his interest in the home. This is the most common method used for one spouse to retain ownership.
Other than both parties agreeing to the value of the property to be used for calculating Bill’s portion of the income, this is transaction is very similar to most refinances.
As for agreeing to a value, if both parties have already obtained an appraisal showing different values, I can often have spouses to agree to the value from the appraisal that I will use for our transaction as it is performed by an appraisal assigned by an Appraisal Management Company, and is completely unbiased as I am prohibited by federal regulations from having any contact with the appraiser.
Differences from a “standard” refinance where cash is pulled out of the property are:
- Bill must sign a “Quit Claim Deed,” in which he quits his claim to ownership of the property. This must be signed, notarized and with escrow before I will fund the mortgage. The quit claim deed will be recorded at closing, after the loan funds.
- After the loan has funded and the deed recorded, funds can be disbursed. In this transaction, the proceeds from the refinance will be transferred directly to Bill, no proceeds can go to Ann. This is because even though we are pulling cash out of the refinance, the loan is priced as a rate-and-term refinancing (saving around 0.500% on the interest rate for Ann) since the funds are to settle a division of assets for a divorce.
One factor we face in divorce refinances is spousal and child support. If the spouse retaining the property is to receive support payments, the payments cannot be used for qualifying for the refinance mortgage unless the amount of the payments are stipulated in a separation agreement if divorce is not yet final, or the divorce decree. As well, and this is usually the sticking point, the payments must have been received for at least six months on a timely, monthly basis; i.e. no pre-paying a quarter or six months in advance.
One more note on support payments, the agreement must state that the payments must continue for at least three years after the date of the mortgage application. If you are to receive child support until your son is 18 years of age, and your son is 15 year 5 months at the time of the application, the support payments cannot be used for qualifying.
Because of the six months payments in a timely fashion requirement, there have been times when we have delayed the final approval and closing of the divorce refinance until after this condition can be met.
If neither party wishes to retain the home, or one spouse wishes to retain the home but is unable to qualify for a loan to pay-out the other spouse, the obvious option is to sell the home.
In this case I help one or both spouses with determining their purchasing power based on their share of the equity that can be used for a down payment, and their income and liabilities that determine the amount of a mortgage they can qualify for to purchase a new home. Note, frequently I go through qualifying and assisting the spouse not retaining the property if the above refinance scenario is used.
If you, or someone you know, is divorcing, I can help determine purchasing power before, or during, settlement negotiations to help determine support payments, and division of assets and obligations.
If I am working with the spouse to receive the support payments, we use qualifying support payments for income. If working with the spouse paying the support payments, the payments are considered a monthly obligation—unless the payments are to end within ten months.
Too often when a married couple begin divorce proceedings the wait until after they have engaged attorneys before contacting us to discuss options they may have with their home, equity, income and obligations. There have been several instances over the years where I have been contacted by past clients before they began the formal divorce process to discuss options for their current home, and the purchasing power of one or both spouses depending on what they decide to do with their current home.
If you know someone contemplating divorce or separation if they are unmarried but own a home together, have them contact me to discuss their options, and likely have a better separation experience.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Okay, but not significant. No, that’s not my view of the Phillies 3-day winning streak, which is okay but not that significant as that followed a 6-day losing streak. It is the markets’ view of Consumer Price Index data released earlier this week. Prices rose 0.4% in April, after a 0.1% increase in March, and are up 4.9% since last April. It is the first time in two years that CPI has increased less that 5% year over year. The slight decline in inflation from March’s 5.0% year over year increase did not cause markets to react with any jubilation or joy that inflation is showing significant slowing.
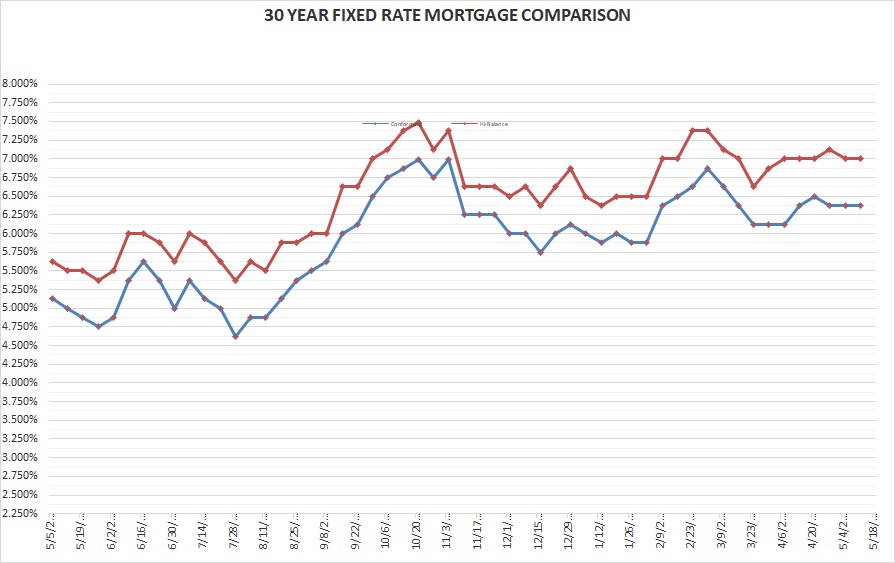
Rates for Friday May 12, 2023 After a brief bump in fixed rate markets (rates lower), on the CPI data, investors reversed course to bring rates back down to where we were last Friday. Looking back over the past two months, rates have floated in a tight range.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.375% Flat
30-year high-balance conforming 7.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Two happy’s today.
Happy birthday to my little big sister, or should I say shorter older sister. Since our mom passed when I was in high school and she was in college, she has provided advice, support and an ear when needed to her two little (younger) brothers.
Happy Mother’s Day to the moms. Being a dad with an incredible wife and mother, in retrospect I appreciate my mom a lot more now having seen Leslie in action over the past few decades as our daughters have grown from stage to stage to stage in their lives. Thank you moms for all you have done, do, and will do, to make our homes and communities better places.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


