

With prices dropping, should we sell our home ourselves?
Question of the week: With prices dropping, should we sell our home ourselves?
Answer: No.
This is a question I was asked recently by an acquaintance who is considering moving out of state. The obvious reason for the question is that he wanted to save money on paying commissions to real estate agents, thinking that would make up for the lower price he expects to get than if he sold a year ago.
There are several reasons to use a licensed real estate agent to represent you in the sale, or purchase, of your new home instead of being a FSBO (fizz-bo, ForSaleByOwner). Here are just a few.
An agent that has knowledge of your neighborhood and the local real estate activity will be able to price your home that reflects its value in the current market for the size, condition, and location of your home to generate a sale within a reasonable amount of time. How will you determine the asking price of your home?
Your home will be listed on the multiple listing service (MLS), exposing your property to thousands of agents and their clients. This increased exposure creates a tremendously larger market of buyers for your home than you will be able to generate. More potential buyers means more opportunities for multiple bidders to generate a higher price.
Potential buyers will want to see your home. A professional real estate agent, working other agents representing buyers, will be gatekeepers to who will be wandering through your home and when. Without an agent you will be letting unscreened strangers into your home when you are not at work, so evenings and weekends, often when not convenient for you.
Are you aware of all the disclosures you must provide potential buyers to comply with California law? A misstep with disclosures may result in your spending money on an attorney post-close to satisfy claims from the buyer of your home.
How will you determine which professional services to use for escrow and title insurance? Not all companies are the same, like all industries some are a lot better than others. Local real estate professionals know this and recommend the companies and professionals in various fields who will provide the best service and work hard to ensure a smoot transaction and closing.
Even with the best in the various real estate industries working with you on the closing of your home problems may arise that can jeopardize the closing. Some of these issues may be from the buyer’s side of the transaction, some may be from your side of the transaction. How will you solve the issues and/or make decisions in your best interest to determine whether to move forward or not. An experienced real estate professional will know who to communicate with and what information is needed to solve any problems and keep you informed of the options and repercussions of those options so you can make the decisions that are best for you and your family.
What if the buyer is not performing in a timely fashion? What recourse do you have? A professional agent will be in touch with the buyer’s agent and lender throughout the transaction and therefore will be aware of the status of the loan and timing for approval and closing.
Speaking of the buyer, are you sure that the pre-qualification letter you were provided from his lender is, let’s say legitimate? A professional agent will vet the lender and the pre-qualification, and requesting a pre-approval, to ensure the buyer is indeed qualified. If s/he feels unsure about the buyer’s ability to qualify to purchase your home s/he will ask a lender they know and trust to review the buyer’s financial information to confirm if they are qualified or not to purchase your home.
Through the years I have had a few clients who thought they would be able to sell their homes themselves, as well a few clients who have wanted to purchase a home from a seller representing themselves. What I have found is that FSBOs attract buyers who have been told by several lenders that they are not qualified to purchase the home they are wanting to buy.
I have had many potential clients call over the years and when I pull their credit report see multiple inquiries from other lenders. They are hoping to be told by the next lender the speak to, me, that they qualify after being told several times they cannot. After looking at their credit, income, funds for closing and coming to the same conclusion as the other lenders I let them know, and know they will try another lender.
A few times when I have assisted a client going the FSBO route I have come across potential buyers who have the same pattern on their credit report who are not qualified. Thankfully for my clients I was able to let them know and they have refused the offers.
What is very important to know if you are considering FSBO, is that once you open escrow with a buyer, as a seller you have lost almost all control of the transaction. The buyer holds the power as it is very hard for a seller to cancel an escrow without following strict guidelines and notices, and even then, a buyer may take to the courts to secure a judgment denying the seller the ability to cancel and giving the buyer time to perform and close.
Finally, studies have shown that home sale prices for properties listed with a professional real estate agent sell for significantly higher FSBOs, often more than if a commission has been paid.
Speaking of price, potential buyers know that you are not paying a commission on the sale, guess how much they want to discount your asking price?
Having an agent will get your home sold faster, and more than likely at a higher price, than if you try to sell it yourself. As well, you will have the support and knowledge of a licensed professional that will be in communication with escrow, title, lender, selling agent, appraiser, termite company, and others involved in the transaction. How much time do you have to communicate with all parties in a timely fashion?
Finally, from a cynical viewpoint, having an agent represent you also provides you with someone professionally accountable should something go very wrong that could have been prevented. Yes, commission is, in a way, also lawsuit insurance.
If you want a bunch of headaches, lost time from work, unnecessary risk, and the other issues above, go ahead and try to save some money and market your home yourself.
If you want reduced stress in an already stressful situation, professional advice and guidance, access to the biggest market of buyers, and a smoother transaction, call and make appointments to interview some local, professional agents to list your home.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Lots of data this week that can impact mortgage rates. Leading the week was the initial estimate of 1st quarter GDP which showed the economy limped along at 1.7% growth to start the year, down from 2.6% growth to end 2022. In our current high rates high inflation environment this news would be positive for mortgage rates. However…inside the data was that consumer spending for the quarter increased 3.7%, the biggest increase in two years. Leading the was the purchase of durable goods (items that last a long time, think appliances) and automobiles. Pulling down GDP to offset the consumer spending spree was a 2.3% drop in investment and production by companies. Because our economy is so dependent on consumer spending, approximately 65-70% of our economy, the spike in spending spooked markets negating the positive for rates of the slowing of the overall economy.
On a more micro level, micro being the month of March separated from the quarter’s data, consumer spending for the month was flat, which is a positive for interest rates. Personal spending increased for the sixth month in a row, up to 5.1%, indicating consumers are putting money away for the future and not spending as much, this is good news for rates as it supports a further slow down in the economy, which should cool inflation, which should cool the Fed’s rate increases, which should lead to lower mortgage rates.
Speaking of inflation and the Fed, the Personal Consumer Expenditures (PCE) index is the preferred index for inflation for the Federal Reserve, showed an increase of only 0.1% in prices in March. Year over year the overall index dropped from 5.1% to 4.2%, very positive news. That said the 4.2% increase in prices is still double the Fed’s target rate of 2.0%. Long time readers, in-depth readers, of the WR&MU know that of high importance to the Fed when reading inflation data is the “core” rate, which strips the overall index of prices for food and energy (they are taken out as they are more volatile and can cause large swings in data). In March the core rate increased a not too friendly 0.3% in March and dropped only 0.1% year over year from 4.7% to 4.6%. The stubbornness of the core rate supports the Fed maintaining its course of continued rate hikes.
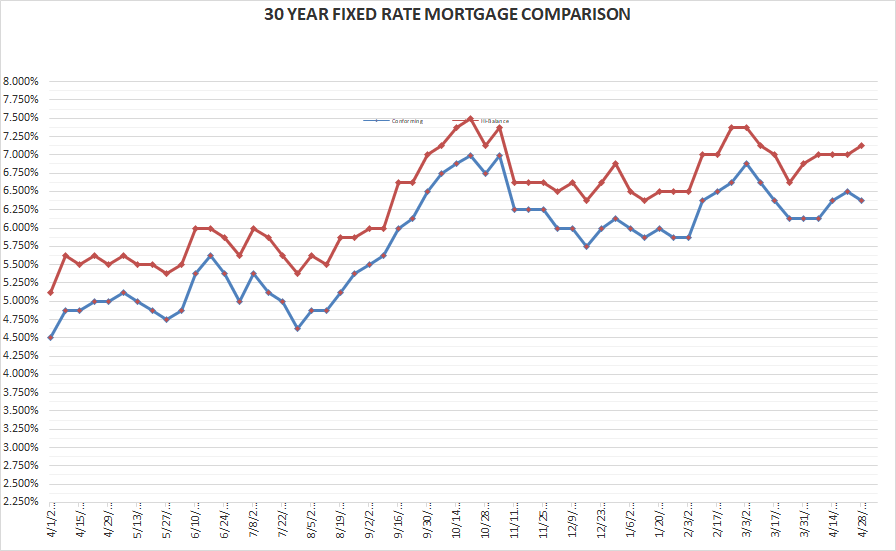
Rates for Friday April 28, 2023: Important reminder concerning weekly rates: In February we covered changes in pricing for conforming loans imposed by the FHFA. The rates presented every Friday in the WR&MU have always had the same factors in determining the rate (see the fine print below), most importantly a credit score of 740. With the changes made earlier this year, other parameters being the same the difference in rate for higher credit scores, for instance a score of 760 may lower the rate by 0.125% to 0.25%. I have maintained the 740 score for rates to be consistent with the rates that have been presented going back to 2005.
That disclaimer out of the way, overall markets reacted favorably this week for conforming rates dropping this week from last Friday, high-balance mortgage rates pop up a bit.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.375% Down 0.125%
30-year high-balance conforming 7.125% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
The WR&MU comes to you from the Best Western Plus in Capitola this week. I drove up yesterday for weekend based in San Francisco to see family and friends, with the first stop to see an “aunt” (mom’s cousin) who lives in this wonderful area.
A beautiful drive as I eschewed the I5, as always, heading west to Maricopa and then north and west to Paso Robles to join the 101 to Capitola. Hills are green, purple, yellow, orange as a result of the rain through the beginning of the year. We have such a beautiful state with a broad spectrum of flora, fauna, geology and geography. I encourage everyone to get off of planes and into cars to explore it!
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


