

Are rates going to drop?
Question of the week: Are rates going to drop?
Answer: Yes.
Interviewer’s tip, always ask an open-ended question to get a more detailed response.
2nd Question of the week: Are rates going to drop? If so, when?
Rates are going to drop, the when is a very difficult question to answer with specificity, however sooner than previously thought.
Because of the crisis, or perhaps great concern, with the banking industry globally, the Federal Reserve has appeared to soften its position on how aggressive it wants to be to still fight inflation.
This apparent pivot in the Fed’s game plan has investors starting to react with the expectation of lower rates.
Adding to the expectation for lower rates are the recent academic data showing inflation slowing and the labor markets cooling down a little bit, the two key factors the Fed has targeted since last year when it began pushing its benchmark interest rate higher.
Going into March, all indications were that the Fed would raise rates by 0.50% this week. After the FDIC takeover of the Silicon Valley Bank, followed by Signature Bank, challenges for First Republic, Credit Suisse being absorbed by UBS, and news today the Deutsche Bank is having difficulty, the Fed announced it was increasing its rate by only 0.25% on Wednesday.
With investors selling off holdings in many American and European banks, central banks and federal governments are moving quickly to pledge support for their banking systems to prevent further defaults, and most importantly depositors losing their funds. (How much protection depositors should receive from federal treasuries is another discussion.)
Since the Fed began its extremely aggressive plan to stop and turn inflation, a favorite talk show and editorial topic has been, “can the Fed engineer its suppression of inflation in such a way that the economy has a soft landing.” I.e., not a hard landing which would be a fairly deep and or long recession. By pivoting to a less aggressive stance, the Fed has those who prognosticate about Fed moves thinking not only with it stop raising its benchmark rate sooner than previously expected, but may actually begin to lower the rate before the end of 2023. This type of thinking seems to take into consideration not only where inflation will be by the end of the year, but the overall economy and the impact the banking crisis may have.
With banks under pressure, a message has been sent by the Fed to banks to slow down their lending, be more conservative in their loan-to-deposit ratios (what percentage of its deposits have out in loans. The higher the ratio the less cash on hand to be able to fulfill requests from depositors for their funds.). Should banks heed the message, fewer loans from banks to businesses and individuals will push bank rates higher, and also reduce funds for expansion, improvements and other capital investments, which will slow economic growth without the Fed needing to raise rates.
Yes, rates will be dropping. They will be dropping in the near to medium future. When they drop they will not go near the rates available from late 2019 through 2021. Optimistically, rates will approach the range of 2018, from mid-four to low five percent rates for mortgages. Realistically, we could have sustained rates in the low to mid five percent range by the end of this year.
Key word in that final sentence? “Could.”
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
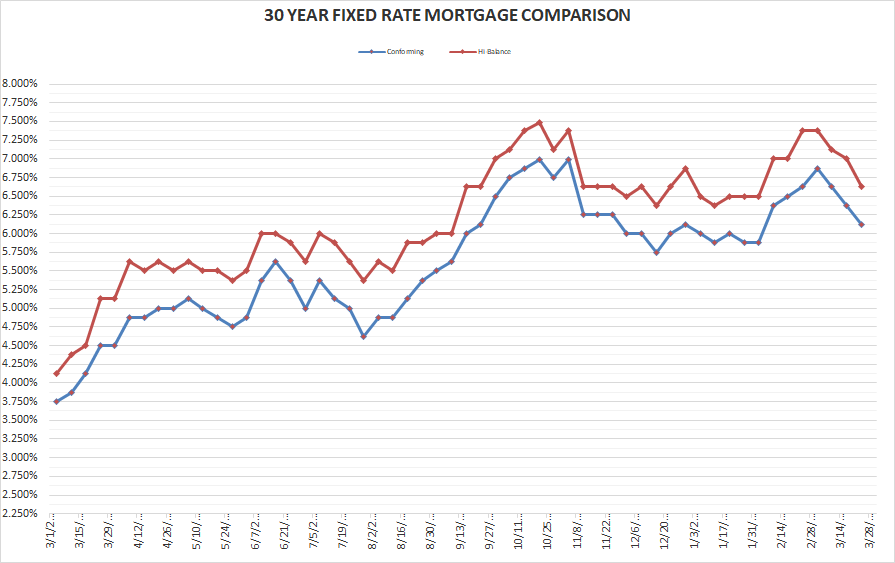
Rates for Friday March 24, 2023: A good week for mortgage rates as investors reacted to all the swirling data, moves by the Fed and U.S. Treasury in regards to backstopping bank depositors, and the Fed’s outlook for the near term. The conforming rate drops 0.25% (one-quarter of one percent) from last Friday, now at it’s lowest rate since early February.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.125% Down 0.250%
30-year high-balance conforming 6.625% Down 0.375%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
I’m still having challenges adjusting to the change to daylight savings time. Just when I was waking up in the morning twilight I’m back to waking up in the dark (my kids think I live in the dark when it comes to pop culture). While we are gaining a two more minutes of sunlight each day, or about one hour more per month, further north, Anchorage is gaining almost six minutes of sunlight a day, or three hours per month.
By the summer solstice Anchorage will have over nineteen hours of sunlight every day. At which point it heads to the winter solstice and about five and half hours daily. By contrast, here in Long Beach our maximum hours of sunlight in June is a little over fourteen hours per day, and in December, just below ten.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


