

Why are rates spiking so quickly?
Question of the week: Why are rates spiking so quickly?
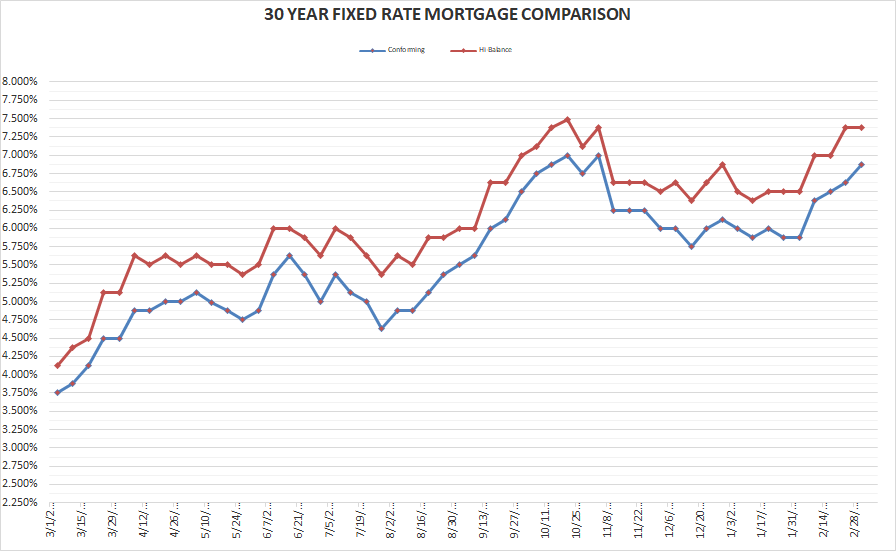
Answer: Conforming mortgage rates have increased one-percent (1.00%) in the past four weeks. They are at their highest point since early November, which at the time was the highest they had been in twenty years. The one-percent jump in the four week period is the second fastest increase in the conforming rate in the past year (in September we saw a 1.125% jump in four weeks). The conforming rate is over 3% higher than on the first Friday in March 2022.
Why the sharp increase after a four-month period when rates were slipping down?
There are two major reasons for the recent rate spike: Data and Federal agency regulations.
Data
As long-time readers of the WR&MU know, economic data is always a primary driver for interest rates. Of all the economic data to impact interest rates, the most important currently, and historically, is inflation. High inflation signals higher rates in the future, so investors in fixed rate investments, such as bonds and mortgages, will demand a higher rate on their investment. Mortgage rates most closely mirror the rates of the 10-year Treasury bond. When the 10-year rate goes up, mortgage rates are going to go up; when it drops mortgage rates drop.
The past month we have seen inflation data show a tick up in prices after a steady downward drop from last summer. As well, we have seen consumer spending jump higher earlier in the year, and wages continue to increase as employers still have more jobs available than applicants.
The Federal Reserve has been very clear that its decision to increase its benchmark rate is “data dependent.” The Fed has been very clear that it will continue to raise rates until inflation falls down to the 2% target the Fed has maintained as the optimal rate of inflation for several decades.
Investors know this. When economic data shows inflation is not dropping, or dropping fast enough. When economic data shows that employers are paying higher wages, which puts upward pressure on the cost they must charge for their goods and services. When economic data shows that instead of slowing their spending due to higher prices, consumers are spending more, therefore driving more economic growth. When all of these happen despite the Fed’s objective of lowering inflation, slowing consumer spending thereby slowing the economy thereby causing unemployment to increases and wages drop, investors react by demanding higher returns on fixed rate financial instruments, such as mortgages.
Data over the past several weeks have been a major factor in the rate spike.
Federal agency regulations.
A few weeks ago the Question of the Week was, “Is the Federal government making buying a home more expensive?”
The answer was “yes.” I will not go into the detail I did in February, but the short version is the FHFA, the federal agency that oversees Fannie Mae and Freddie Mac, who provide conventional mortgages, imposed a myriad of new fees on lenders for mortgages being sold to Fannie and Freddie.
Not surprising, and as expected by the FHFA, those fees are being passed through to borrowers. The fees will be charged to lenders on all mortgages sold to Fannie and Freddie after April 30th. Because of the lag time between loans being locked in, closed, purchased by the lender, packaged with other mortgages, and then sold to Fannie or Freddie, that fees have been added to rate sheets, thereby reflected in higher mortgage rates.
So a double-dip of negatives have converged to spike interest rates the last few weeks.
Looking forward, at this point there is little on the horizon that will cause rates to begin a steady and consistent drop towards 6.00% or below. I hope my vision is off and this is not the case, but I don’t like to rely on hope.
To schedule an initial meeting by phone or Zoom, click here for my calendar, please feel free to forward to a friend or family member!
Have a question? Ask me!
Rates for Friday March 3, 2023: Not a lot of specific rate moving news this week, beyond a bad inflation report from Europe. Mainly rates are riding the momentum of the past few weeks.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 6.875% Up 0.125%
30-year high-balance conforming 7.375% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
It’s here! My favorite background noise while I work, drive, garden, read, is back!
Major league baseball on the radio. Yes, I know it is pre-season and the games have no bearing on when the Phillies will lock up the National League East and their way to winning the World Series. But there are baseball games being played in Florida and Arizona between major league teams and I can listen to the play-by-play throughout the day as I go about my business.
One of my favorite bills to pay every year is my subscription to MLB.com so I can listen to any MLB game’s radio broadcast from any team, and watch the television broadcast of every game not involving the Dodgers or Angels.
Baseball is on the radio, that means spring is around the corner.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


