

Why is my credit score affected by my parent’s credit?
Question of the week: Why is my credit score affected by my parent’s credit?
Answer: In the summer of 2018 Leslie and I did what many parents have done for decades, we gave our daughter heading off to college a credit card from our account for emergencies and approved expenditures.
“Daddy, can I use the card for my room deposit?”
“Take your friends to dinner for your birthday and put it on the card.”
“Rental car needs a card for deposit, can I use the card and pay you back?”
“I want to make a donation to the 3-Legged Dog Society, can I put it on the card?”
Yes, yes, yes, NO!
Our daughter is an “authorized user” on our credit card account. She has no obligation to make any payments, if Leslie and I walk away from the account the credit card company cannot come after her for payments.
For many years we would see (A) designation next to American Express accounts on some of our clients’ credit reports. The client was put on the account by his or her parents in the past for the same reasons we gave a card to our daughter; or we see children going on an account for elderly parents so they can used for the parents account to pay for goods and services needed for their care.
Whatever the reason one is an authorized user, these accounts could often cause us issues in obtaining loan approvals.
The account balance and monthly payment would become part of our qualification process. As well, if the parents were prone to missing payments from time to time, the clients credit score would be negatively impacted.
In the last several years we have seen every major credit card company reporting accounts on the reports for authorized users. Even though there is no obligation, or control, of the account by the authorized user, their credit rating and ability to qualify is impacted by the actions, or non-actions, of the person(s) responsible for the account.
Note that parents putting children on credit card accounts are not the only instances of authorized users. You can add a spouse, a life partner, or a business partner to an account as an authorized user.
How impactful can this be? Suppose our daughter is applying for a loan and on our account for which she has a card we have run up a $45,000 balance with a minimum payment of $900 per month. On her income this is a significant percentage of her income. Because of this high minimum payment showing on her credit report, she does not qualify for the loan. Or suppose the account has a very low balance, but in the last year we have been late on two or three payments. Her credit report is lower by 50-60 points, and while she is approved for the loan her interest rate is higher.
What can be done if you have authorized user accounts on your credit report. Contact the credit card company and request that you be removed from the account and cancel your credit card on the account. Some companies may require the primary account user to cancel your ability to use the account.
If you are in process with a mortgage application and this issue comes up, once you are no longer an authorized user on an account, a new report can be obtained that omits the account and any monthly obligation and balances. As well, if need be, we can re-score the account.
Yes, your parents can impact your credit rating. And you can impact your children’s.
Have a question? Ask me!
Numbers keep climbing. A lot of economic data this week points to continuing inflation and higher interest rates. Consumer spending increased 0.2% in February and the Personal Consumption Expenditures Price Index (PCE) a primary index for the Federal Reserve, showed an increase in prices of 0.6% for the month and 6.2% since last February. As can be seen by the increase in spending being less than the increase in prices, taking inflation out of the spending data and while dollar sales were higher, transactions were lower.
Labor market data released today shows 431,000 jobs created in March and the unemployment rate slipping from 3.8% to 3.5%, approaching a pre-pandemic low. The numbers show that hourly wages were 5.6% higher this March than last, the highest increase in forty years.
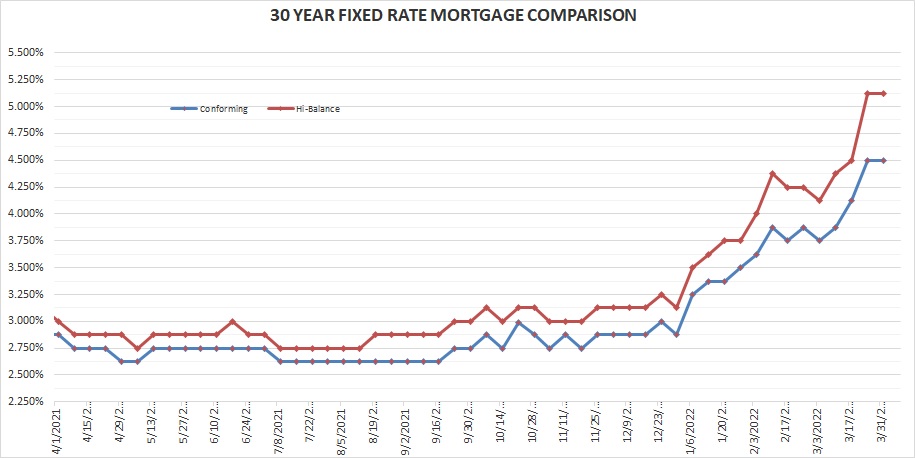
Rates for Friday April 1, 2022: Continuing tightness in labor markets, as seen by low unemployment and rapidly increasing costs, high fuel costs, the war in Ukraine not seeing any abatement, and lockdowns in China due to Covid impacting manufacturing, all support higher interest rates in the near and long-term. Despite all the news this week, rates are flat from last Friday.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30-year conforming 4.50% Flat
30-year high-balance conforming 5.125% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
The temptation when writing anything on April 1st is to put up something somewhat plausible, enough to create a stir, but not so plausible that it is not noticed or commented. Something like, after dodging for two years I have tested positive for Covid-19. Or, the Dodgers traded Clayton Kershaw to the Giants. Or, Gavin Newsom is resigning as Governor to become the U.S. Secretary of State.
One of these is true. All is well.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


