

How much has my purchasing power dropped since the beginning of the year?
Question of the week: How much has my purchasing power dropped since the beginning of the year?
Answer: About $90,000.
Mortgage qualifying is a series of math problems (tell your kids that Algebra matters, Algebra II and up not as much unless you are going into fields that require advance math for success).
The first calculation is to determine monthly income. After that we calculate the amount of monthly income we can use for your housing payment.
Part of the housing payment is property taxes and homeowner’s insurance, which for quick calculation we assume is 25% of the total housing payment. Note that the industry standard is to use 1.25% of the sales price for taxes and 0.30% of the loan amount for insurance.
Taking 75% of the monthly income that can be used for a housing payment for the mortgage payment, mortgage interest rate that is based on several factors (property type, credit score, loan-to-value, among others) and the term of the mortgage we can determine the size of a mortgage.
Add the amount of down payment to the mortgage calculation and we have a sales price.
Now some numbers. I ran calculations using household income of $100,000 per year, use 40% of income for total housing expense, can be lower depending on other debt, and a 20% down payment.
To avoid being too wonky, numbers are rounded for easier comparisons.
Monthly income for total monthly housing payment (PITI) is $100,000/12 months = $8333 per month, $8333 x 40% = $3333 for PITI.
Amount for mortgage payment is $3333 x 75% = $2500 per month.
Regardless of the rate environment we will calculate the mortgage payment using $2500 per month.
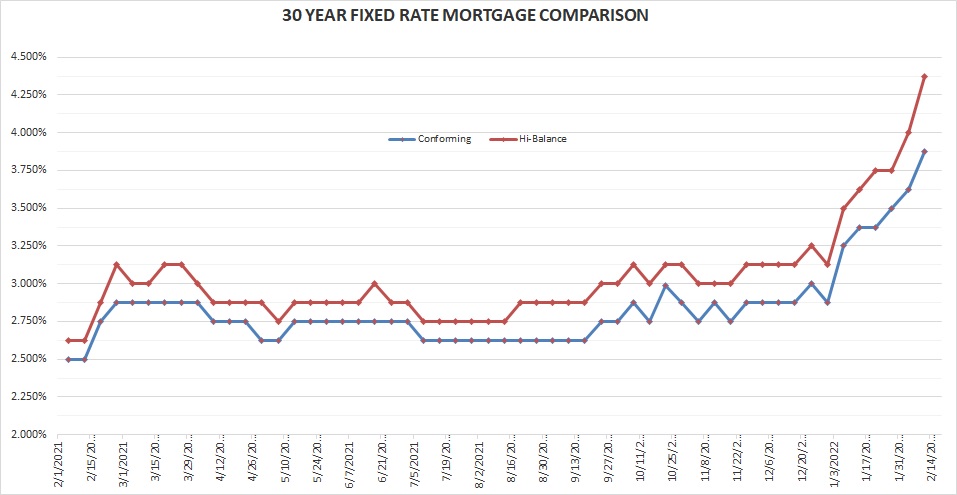
On Friday December 31st the 30-year conforming fixed rate was 2.875%, the loan amount with a $2500 payment is approximately $600,000, with 20% down payment, that is a purchase price of $750,000.
Today the 30-year conforming fixed rate is 3.875%, 1% higher in rate, and about 35% higher than the December rate (1% is 35% of 2.875%).
Using $2500 per month and a rate of 3.875%, we arrive at a loan amount of about $530,000 and a purchase price of $660,000 with 20% down.
The increase in mortgage rate since the beginning of the year has reduced your purchasing power of $100,000 in income by $90,000, or 12%.
For the number nerds like myself, in reality with the same resources, the purchase price today is $680,000 since you have saved $150,000 for down payment at the $750,000 price. But you get the idea!
In the how times have changed department, last May the QOTW was, “Is it better to purchase a home with a high price but a low interest rate or low price with a high interest rate?” As we saw, the lower price, higher interest rate was the better proposition due to the lower amount of cash needed.
What we have today compared to May 2021 is higher price and higher rate.
Have a question? Ask me!
I was a sophomore at Pitzer College, it was my second semester. Professor Gary Smith’s (no relation) class at Pomona College on monetary policy dealt with the Federal Reserve, money supply, inflation, liquidity and interest rates was to be the foundation for much of what I know, and continue to learn about, interest rates and their impact on the economy and consumers. Why do I bring this up? February 1982 was the last time the Consumer Price Index was as high as it was in January 2022 which clocked a 7.5% increase in prices over the prior twelve months.
Led by food, energy and rents, somewhat essential items for all families, prices in January rose 0.6%. Groceries were up 1% for the month. Year over year, new car prices had a historic increase of 12% from 2021.Those booking hotel rooms or engaging new wireless phone services benefited from lower prices.
How much, how often? Are the questions being asked. The is very little doubt that the Federal Reserve will increase its benchmark rate in March. How much will they increase the rate, 0.25% or 0.50%? Will they follow the March increase with another increase at the May meeting? Or will there be a surprise rate hike in April?
Mortgage and bond rates spiked yesterday when the CPI data was released. Evidently investors feel the answers to the above questions are 0.50% and often. It was not that long ago that Fed officials and the former Chair of the Federal Reserve and current Treasury Secretary were trying to calm inflation fears calling the rise in prices early in 2021, “transitory,” and prices would cool into 2022. Now there appears to be little chance that inflation will fall to near 3% before sometime in 2023, if then. Very tight labor markets creating higher wages, continuing supply chain issues creating scarcity of supply, have combined for sustained inflation in our economy. None of this is positive news for lower mortgage rates.
Rates for Friday February 11, 2022: Rates popped up yesterday after the CPI data was announced, they are coming back somewhat today but not enough to cover yesterday’s jump. Absent the 5-week spike and drop when the economy was shut down at the beginning of the pandemic, rates are at their highest since May 2019.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS FOR PURCHASE TRANSACTIONS:
30 year conforming 3.875% Up 0.25%
30 year high-balance conforming 4.375% Up 0.375%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Realizing you are likely tied up on Sunday, here is something fun for parents, or grandparents, of kids in the kindergarten to 5th grade range. The Long Beach Area Council of the Boys Scouts is having a Pinewood Derby clinic with free kits and instructions for kids in that age bracket tomorrow, and also on March 12th. Here is a link for LBAC Pinewood Derby Clinics and Race that includes a Pinewood Derby Card and Flyer: Pinewood Derby – Long Beach Area Council – Boy Scouts of America.
In regards to Sunday, I am rooting for Cincinnati. Not just the team but the city and region who have stuck with the Bengals through so many challenging seasons. Being an Eagles fan, I know the long haul it can be some (most) seasons staying faithful. The last time Cincinnati won a championship in any sport was in 1990 when the Reds won the World Series. In that time the LA/Orange County area has seen 17 championships in major sports (Lakers-9, Dodgers-1, Kings-2, Angels-1, Ducks-1, USC Football-2, UCLA Basketball-1).
I’d like the Bengals fans to experience what I and millions of other Eagles fans experienced in 2018 when they won their first championship since 1960.
Also, being a former Rams season ticket holder, they lost me with the move to St. Louis, where they won a Super Bowl in 2000.
Have a great week and enjoy the game,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog


