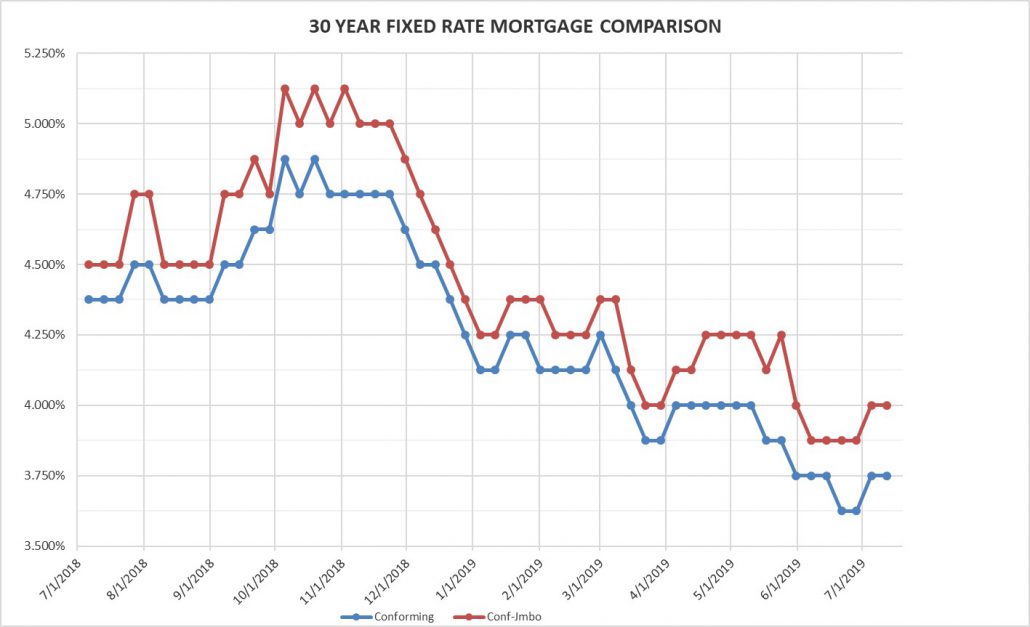
Question of
the week: How does the impeachment process in Washington
impact mortgage rates?
Answer: Directly there should be no impact. Indirectly, as economists like to
say, that depends…
On September 24, 2019
Speaker of the House Nancy Pelosi announced that six committees of the House of
Representatives would begin formal impeachment inquiries of President Trump.
Long time readers of the
WR&MU know that disruption, uncertainty and crisis that harm the economy effect
investors, who react by “flight to safety;” in other words they will sell
riskier investments, meaning stocks, and purchase relatively safe investments,
meaning bonds and other fixed rate investments. An alternative to what are
considered the safest investment available, bonds issued by the United States
Treasury, are Mortgage Backed Securities (MBS), in other words residential
mortgages.
As investors sell stocks
prices in the stock market will drop. As investors purchase bonds and other
fixed rate investments like MBS those prices will rise. For interest bearing
investments like mortgages and bonds as the prices rise the rates drop.
Back to our question. If
investors consider the impeachment process, and actual impeachment, a
disruption that would impact the economy negatively they would flee to safety,
selling stocks and buying bonds and mortgages.
For the past two and a
half months investors have ignored what is happening in the hearings in various
committee rooms in the Capitol. Since mid-September the Dow Jones has gone up
about 1000 points, 3.7%, and mortgage rates are about the same this Friday as
they were on September 27th—actually the conforming high-balance
rate is a tick lower.
Politics impact investors
decisions only as much as they feel they will disrupt or benefit the economy.
Should President Trump be impeached what will be the significant impacts to the
economy as a result in any change in policies that effect businesses and
markets? That is the question investors answer as they place their bets in the
equity and fixed rate markets. From their reaction so far it appears they believe
that if Trump is impeached the policies and actions of the new Pence
Administration in regards to business, trade, taxes and markets will not be
much different.
While individual investors
may have personal political bias when making donations and punching ballots,
investors as a group however are concerned only with the politics that impact
the bottom line. It appears that the charts on the business pages are paying no
concern to the news on the front pages.
Big news for those seeking mortgages. The Federal Housing Finance Agency
announced the new loan limits for conforming (Fannie Mae and Freddie Mac) for
2020. The new limits are $510,400 for conforming loans and $765,600 for
high-balance loans in eligible areas (Los Angeles and Orange Counties are
eligible). The loan limits are based on median home prices nationwide, the
fairly significant increases from 2019 reflect a strong increase in prices
across the country.
Investors are not the only ones. It appears that businesses are not
concerned about a potential change in administrations in Washington. The Labor
Department today announced that the economy added 266,000 jobs in November,
well beyond the expectation of 180,000. Part of the increase was due to 50,000
striking workers at GM went back to work, absent those numbers the new jobs
created still exceeded expectations. The unemployment rate dipped back down to
its 50 year low in November, to 3.5%, and the average hourly wage rose to
annualized rate of 3.1%–well above the rate of inflation which is below 2%.
Overall the news is mortgage rate unfriendly as more workers means more wages
means more consumer spending means more economic growth. As seen above, if bad
news pushes stocks and rates down, good news pushes stocks and rates up.
Rates for
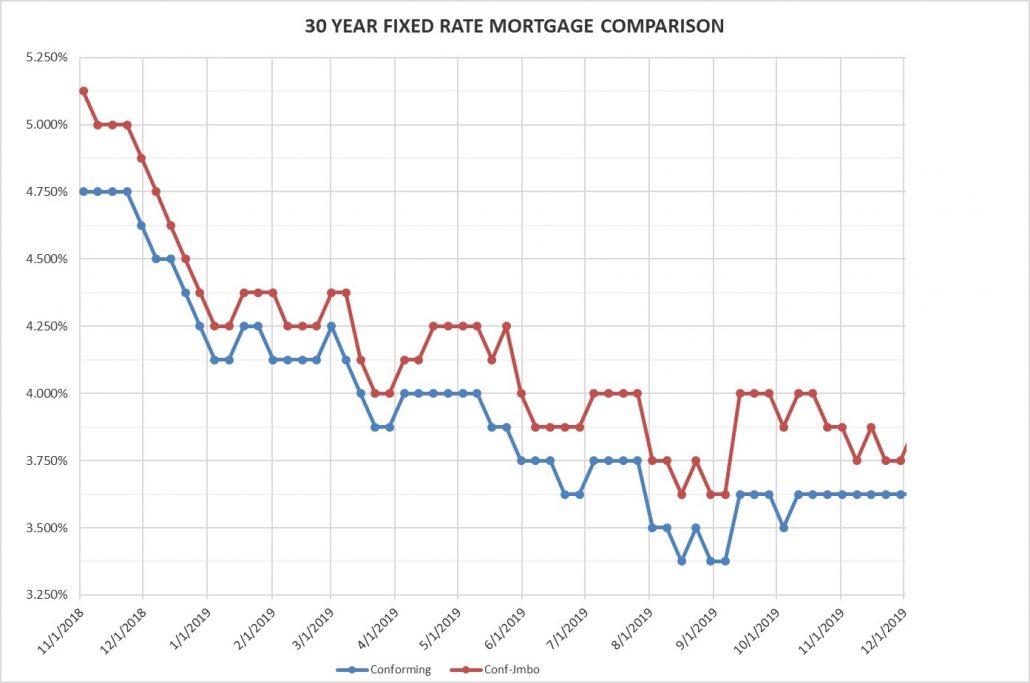
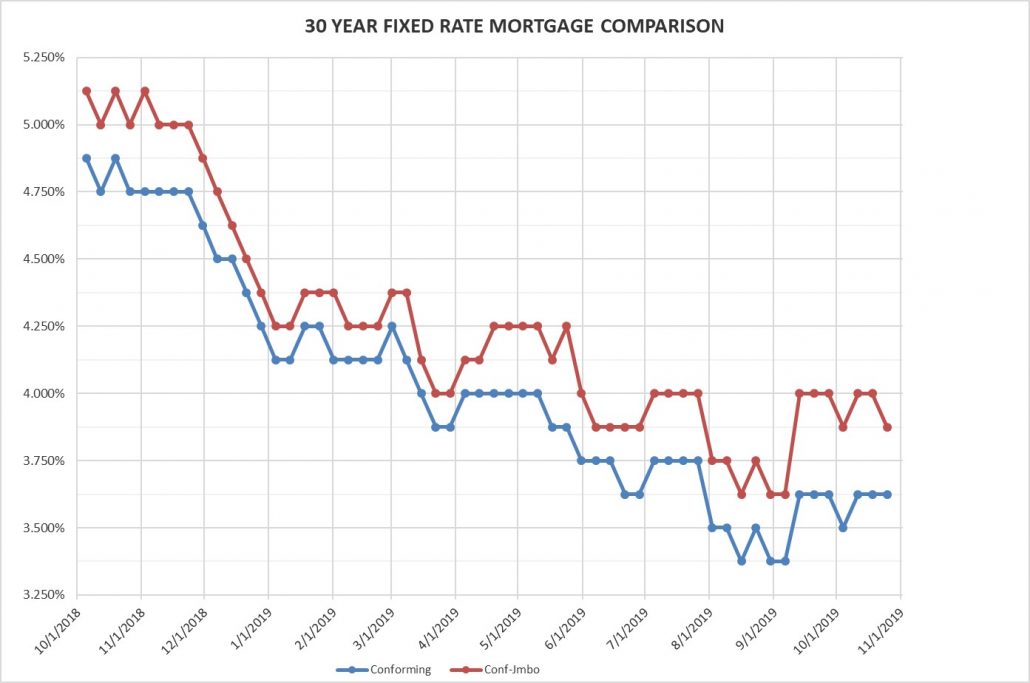
Friday December 6, 2019: The conforming rate has been the same every Friday
since in increased from October 4th to October 11th. That
is eight weeks in a row, the longest streak since February 9th to
April 13th 2018 when the streak was nine weeks. The high-balance
rate drifted up slightly from last Friday.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.625% Flat
30 year high-balance conforming 3.875% Up 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
It’s here.
December filling our weekends with parades, parties, get togethers and music. This
is the last month of the decade, a lot different than the first month of the
decade when housing markets were still dropping in prices and our topics of discussion
were foreclosures and short sales.
I hope you have
a great month enjoying the opportunity to see family and friends and create
wonderful memories with both.
https://www.denniscsmith.com/wp-content/uploads/2018/10/legal_DennisCSmith.png800800Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-12-06 14:18:482019-12-06 14:18:51How does the impeachment process in Washington impact mortgage rates?
This week’s question of the week is a repeat from last
October, however the topic is one I feel should be addressed every year for
homeowners in California.
Question of
the week: We just received our property tax bill…
Answer: Okay, okay this is not a
question; it is the start of a question. There are several phrases to make it a
question I will quickly go through this week:
…why is it lower than you
estimated when we purchased our home earlier this year?
…why is it higher than
last year since we are under Proposition 13?
…how much should we pay?
…why is it lower than you estimated when
we purchased our home earlier this year?
If
your property tax bill is significantly less than my estimates when we funded
the loan to purchase your home then you will very likely receive a supplemental
tax bill, if you have not received one already and the two bills added
together, the tax bill you have just received from the County where your
property is located and the supplemental tax bill, should be close to the
estimate we used when you purchased your home.
In
California, the fiscal year is from July 1st to June 30th.
The tax bill property owners have received in the past week from their County
Assessor has an option of paying half the bill by December 10th covering
first half taxes from July 1st to December 31st and the
other half by April 10th covering the second half taxes from January
1st to June 30th. The tax bill mailed in September or
October is based on the prior tax bill as adjusted for Prop 13, or if there was
a transfer the value on January 1st.
When
you purchase a property the tax base for the property is adjusted based on your
purchase price. Depending on when you purchased the property the new value may
not be adjusted by the County Assessor before the tax rolls are set for the
coming fiscal year. If this is the case the tax bill you have received reflects
the prior assessed value plus and adjustments for Prop 13 (see below) or
additional payments for taxes or bonds put in place by voters or local government.
This is the primary reason your tax bill is probably lower than you
anticipated, and why you will receive, or have received, a supplemental tax
bill.
The
supplemental tax bill covers the difference between the taxes on the tax bill
and the taxes you should be paying from the date of the close of escrow on your
property purchase to the end of the fiscal year, June 30th.
Depending on the seller’s assessed value and your purchase price the
supplemental bill can be very large, very small, or even “negative,” in which
case you will receive a refund from the County.
Supplemental
tax bills are only mailed a few times a year, so it may be some time after you
closed your purchase before you receive your supplemental bill. Please note, if
you have an impound account and your lender is collecting and paying your
property taxes that your supplemental bill is not sent the supplemental tax
bill, the payment is entirely your responsibility.
Confused?
Let’s say you purchased a home for $650,000 and closed escrow on February 7th.
Using our rule of thumb of your property taxes being 1.25% of the purchase
price your annual taxes the first year of ownership should be $8,125 per year
($4062.50 for the first and second half tax bills). Your seller purchased the
property in 2000 for $375,000 and their assessed value has risen through the
years and their tax bill the year they sold the property was $5500. You just
received your first property tax bill from your County Assessor and it shows
you owe $5610 conveniently payable in two payments of $2805 each.
There
is a difference in annual taxes between what you should be paying and what you
are being billed of $2625. However, this will not be the amount of your
supplemental tax bill as that is the annual property tax differential and you
only owned the property since February 7th, not July 1st
of the prior year. There are 143 days between February 7th and June
30th, and that is the period which the higher assessed value should
be applied for property taxes. Therefore, your supplemental tax bill will be
the annual property tax differential divided by 360 days multiplied by the
number of days you owned the property between the sale date and end of the tax
year:
$2625/360
= $7.29 per day x 143 days = $1042.71 as your supplemental bill.
Note
that depending on your closing date you may receive more than one supplemental
bill.
It
can get pretty confusing, however most County Assessor websites have links
where you can input your address, sales price and closing date and it will calculate
your estimated supplemental tax bill.
…why is it higher than last year since
we are under Proposition 13? Prop 13
was passed at the ballot box by California voters on June 6, 1978. There were
three major items in the measure that immediately impacted property owners in
1978. First, it decreased assessed values by having all properties in
California re-assessed to their assessed values in 1976. Second, it capped the
assessed value of real property taxes by to the state at 1% of the ad valorem value of the property, i.e.
the transaction value. Third, it limited increases to assessed values to an
inflation index but not to exceed two percent (2.00%) per year.
It
is the third factor that confuses many new or experienced property owners when
they receive their property tax bill that the total is higher than what they
paid the year before. Since property values are increasing your assessed value
is increasing as well, but not more than two percent above the assessed value
from the prior year.
Also
surprised are those property owners who do not follow the news or politics.
Their surprises come in the form of special assessments put on tax bills by
either voters or elected officials in the form of bonds or taxes. For instance
for our home in Long Beach we have nine such assessments that add 29% to our
base tax rate of one-percent. Three of the assessments are local bonds for the
Metro Water District, Long Beach Community College District and the Long Beach
Unified School District; the other six are county measures and bonds for parks,
flood control, sanitation, etcetera. Every city and county has different
special assessments on their property tax bills that are added to the
one-percent maximum taxable assessment from the state.
…how much should we pay?
Before I
answer here is the disclaimer: I am not a tax professional or accountant,
before you make any decision as to how much you should pay in property taxes
this year consult your tax preparer.
In December 2017, the
federal tax reform was enacted in Washington D.C. Part of the new tax act was
capping the deduction for State And Local Taxes (SALT) to $10,000. This impacts
residents and homeowners in several states, including California. Why bring
this up? Some individuals or families may want to consider paying their first
and second half property taxes in 2019 if they will not reach the $10,000 limit
in SALT paid in 2019 and predict they may exceed it next year. Before making
this decision consult with your tax preparer
who can review your options and help you forecast next year’s income and
possible tax liabilities for 2020.
Repeating my disclosure: I am not a tax professional. Before
making any decisions regarding our taxes please consult with your tax preparer.
If you own
property I strongly recommend you have two professionals assist you: a family
law attorney to help you establish an estate plan with a trust and a
professional tax preparer to ensure you are maximizing your tax opportunities
as well as able to provide advice when needed.
If you have
any questions on property taxes please do not hesitate to contact me and I will
assist you the best I can.
If you, or
someone you know, do not currently pay property taxes I am very willing and
able to speak with you about how you can purchase property and become a
homeowner!
After last
week’s busy economic calendar this week saw little in the way of
major economic data that would have big impact on rates. What did have markets
moving was announcement from Chinese government late Wednesday that China and
the U.S. were very near a phase 1 agreement to rollback some tariffs. This made
equity markets happy and bonds, mortgages sold to purchase stocks—stocks up,
rates up. The news was called premature by the U.S. and was seen as a
negotiating ploy by the Chinese to put pressure on the White House to take
whatever China has on the table to announce a deal. Stocks sold, bonds and
mortgages bought. So the see-saw in markets continues to go up and down based
on rumors, announcements and tweets regarding the Sino-American trade dispute.
Rates for
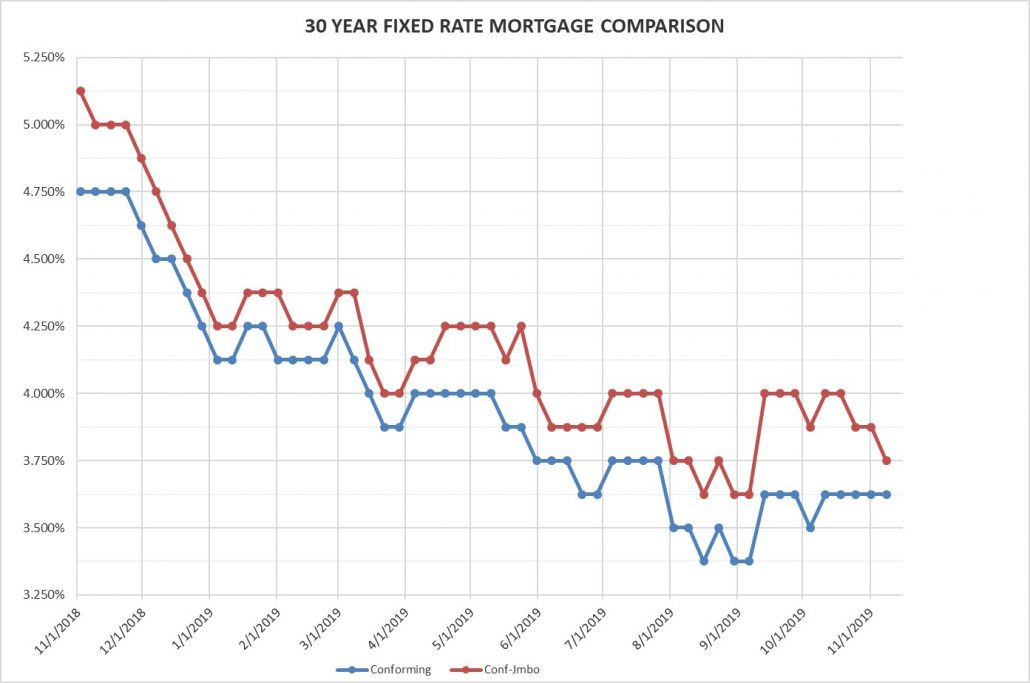
Friday November 8, 2019: After the inter- and intra-day ups and downs the
conforming rate is flat for the fourth Friday in a row. The high-balance has
dropped this week at two of our lenders. Why with some lenders but not others?
Lenders have a bit of restriction on what percentage of their mortgages with
Fannie Mae and Freddie Mac can be “high-balance” (over $484,350 and in LA and
Orange Counties no higher than $726,525). When lenders are near the threshold
they raise their rates on these loans, if they are not near their lending limit
they lower their rates. The advantage Stratis Financial has is we can sift
through several lenders to see who is offer what rates on any given day for any
give product.
Rates and markets are still “edgy” to news and views, my advice is not to
try to hit “the low,” but lock in your rate as soon as you are able.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.625% Flat
30 year high-balance conforming 3.75% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
I don’t
understand how when we travel to other time zones I almost instantly adapt to
the new time, but when we change our clocks at home my rhythm gets messed up
for several days. Maybe I should pretend I have travelled somewhere in the fall
and spring when we shift our time pieces!
https://www.denniscsmith.com/wp-content/uploads/2018/10/taxes_DennisCSmith.png800800Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-11-08 13:45:562019-11-08 13:46:01About that property tax bill...
What we have not addressed in
several years is what if you have poor credit and want to buy a home. The question
of if your parents, or another connected party, can help you purchase your new
home if you have poor credit.
The quick answer is, No. Of
the three factors that are considered for a borrower in loan qualifying,
income, credit and cash to close, credit is the one area that outside
assistance is not able to enable qualifying.
Mortgage underwriting
guidelines state that the lowest middle credit score of all borrowers on an
application is the score that will be used for qualifying and pricing the loan.
For instance, Angela and Adam are recently married and wish to purchase a home.
Angela’s credit scores from the three major credit agencies (Experian,
TransUnion and Equifax) are 763, 744 and 768; her middle score is 763. Adam had
a few issues in his past and his middle scores are 689, 703 and 679; his middle
score is 689. Since Adam’s middle score is the lowest of the two, the score for
the file is 689.
Some programs require a minimum
score of 700 to be eligible. If one of these programs were the one Angela and
Adam wanted for their home purchase or refinance they would not be eligible for
the program. “Dennis, what can we do? Can my parents co-sign for us?”
If you are unable to qualify
because your income is low, we can add a “non-occupant co-borrower” to your
mortgage application to enable you to qualify. If you are short funds to close
you can get a documented gift from your parents or other connected party to
qualify. If you have a credit score that is too low for the loan program for
which you are applying the only way you can qualify for that program is to
increase your credit score.
All is not lost. There are
different options that may be available to Angela and Adam to achieve their
home purchase or refinance goal.
One option is to look at Adam’s
credit report and see if there is something that can be done to increase his
score. Perhaps paying an account down, or off, may raise the score the eleven
or more points needed; or sometimes opening an account will get the extra
points needed. Not all credit reports are the same and the composite data that
creates the credit score is influenced by many, many factors. Depending on what
is on the report it may be fairly easy to increase the score.
A second option is to see if
there is another program that may enable Angela and Adam to achieve their goal.
While more expensive because of mortgage insurance, FHA mortgages are often
used for clients with lower credit scores because their minimum scores for
different programs are a lot lower than those for conventional and most jumbo
programs. The decision factor in this case is the trade-off between the current
higher mortgage cost due to the mortgage insurance versus the potential higher
cost if waiting to purchase or refinance due to higher home values and/or
rates. It is not an unusual reaction to want to have the mortgage product with
the lower costs, however that product is not available to you, a change in
mindset may be the most beneficial to you in the long term as you are able to purchase
your home today.
A third option is that
perhaps mom and dad can co-sign—with Angela. Depending on the ability of
everyone involved and the mortgage program, by dropping Adam from the mortgage
and adding mom and dad as co-signers the transaction may be able to continue.
One other option we have
employed is for mom and dad to purchase the property as an investment property.
Angela and Adam move in and make all the payments for the mortgage, property
taxes and insurance. In the future, when Adam’s credit scores are better,
depending on the rates and the market Angela and Adam may want to refinance to
put the home and mortgage in their own name.
Since a low credit score
cannot be cured with adding co-borrowers, it is advisable for you to know what
is on your report and address any issues that are negatively impacting your
credit as soon as you can. We have plenty of experience analyzing credit
reports and assisting borrowers increase their scores. Sometimes this can happen in a short period
of time, sometimes not. For the latter, I always bring up a client from more
than twenty years ago, Yvonne.
Yvonne and her husband wanted
to purchase their home but had undergone some economic traumas that resulted in
low credit scores. Yvonne was determined to own her own home and for almost two
years she worked to improve their credit. She would constantly check in with me
and we would review her accounts and her plan, checking her credit report every
5-6 months to see where they stood. Finally, the day came when their credit was
rehabilitated and they purchased their home. When I called to tell Yvonne her
loan had funded and she was going to be a homeowner she was not the only one on
the call with a catch in her throat and blurry eyes.
Poor credit and low scores
can delay your home ownership, but do not let it prevent it. Be like Yvonne and
tackle the problem as soon as you can.
This was a
very busy week for market impacting news and data. In order of
the announcements this week and positive or negative impact on rates:
One year
after hitting a peak, consumer confidence in October was down slightly
from September, but by less than prior months. Over the past year the consumer
confidence chart looks like a ride at Knott’s Berry Farm. The valleys have been
getting higher since January and the trend line looks like the next trend is
back up. The over-riding news from the report is that consumers are reasonably
confident and holiday spending should not be curtailed. Over all the news is
somewhat negative for rates as high consumer confidence can lead to high
consumer spending, which is about 65-70% of our economy, which leads to
economic growth.
Consumer
confidence and spending resulted in another positive quarter of growth for
the Gross Domestic Product. The 3rd quarter increase of 1.9% was
down a peg from the 2nd quarter growth, but higher than the 1.6%
that was expected from most of the experts. Inside the report, the spending by
consumers in the quarter more than counter-balanced a large drop in business
investment caused by a drop in oil prices and the trade conflict with China. Showing
stronger than expected growth, despite consumer spending dropping from the
extremely strong 4.6% growth in the 2nd quarter to 2.9% in the 3rd
quarter, plus residential housing investments increasing for the first time in
five years, the GDP data is negative for mortgage rates.
Following
the GDP data release was the announcement from the Fed that it cut its
benchmark interest rate by 0.25%. This move was expected and on its own had not
impact on mortgage rates. In making the rate announcement the Fed used its
normal Fed-Speak to announce that it would likely take a pause before enacting
any more rate cuts. Some investors have expected more rate cuts in the near
future and a pause puts them on the wrong side of the market. From their
announcement, it appears the Fed is content with the current path on rates as
they forecast continued moderate growth in the economy, a continuing strong
labor market and inflation very near its 2% target. Overall the news is a bit
rate negative due to the Fed taking off the table the certainty of another rate
increase and the more positive message than it has supplied in prior
announcements.
Thursday, it
was back to consumers as the Commerce Department released data for September
on consumer spending, personal income and inflation. Consumer spending
increased for the month at a mundane 0.2% rate, down from August’s dull 0.3%
growth. While dull and mundane, September was the seventh month in a row of
increased spending. The increase in spending was supported by higher earnings
as incomes rose 0.3% in September, reflecting the strongest labor market in
fifty years. With spending increasing at a slower pace than incomes it is not
surprise that the savings rate increased to 8.3%, near post-recession highs and
showing that while consumers are spending steadily they are doing so within
budgets that enable saving as well—something that was absent prior to the Great
Recession. Because the growth in spending and incomes have been moderate the
pressure on prices has been the same, prices have increased only 1.3% from September
2018, the matching February as the lowest since 2016. This news is neutral for
mortgage rates as it reflects an economy that is not booming nor busting but
chugging along.
Rates for
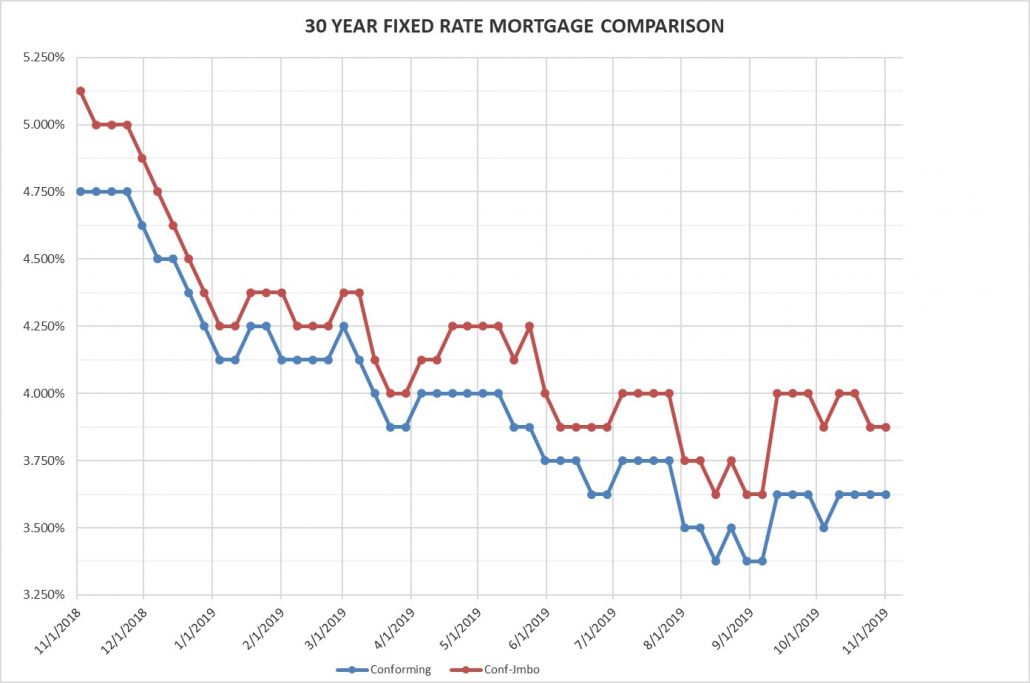
Friday November 1, 2019: Last week there was an error in the rate numbers
below, the chart was correct but not the numbers, they did not reflect the
0.125% drop in the high-balance rate from the prior week. This week the
high-balance rate further compresses to the conforming rate, which is flat this
week. Following all the economic news reported today I was expecting rates to
be a bit higher. We may be nearing the end of a cycle so a bump next week would
not surprise me.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.625% Flat
30 year high-balance conforming 3.75% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Do not forget to turn your clocks back before you go to sleep on Saturday night or you’ll be early for church…or is it late? I can never keep that part straight.
If you live
anywhere in Southern California you have likely smelled smoke over the past few
days. Unfortunately, it is that time of year again where too many of our fellow
Californians are experiencing trauma and tragedy due to major fires. Here is
what has become a semi-annual link I provide for those who are wanting to help:
Donate
to the Red Cross The Red Cross does what no other entity, public, private
or non-profit, does when it comes to disaster relief and assistance, every
little bit helps. If everyone who receives this Weekly Rate & Market Update
donates just $10, more than $6000 will be raised to assist with food, blankets
and housing. Take a minute and click-it!
I was
half-right last Friday, the Washington Nationals did win their first World
Series ever, but it took more games than I thought. How amazing that every game
was won by the visiting team!
https://www.denniscsmith.com/wp-content/uploads/2017/06/serv1.jpg200400Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-11-01 13:52:382019-11-01 13:52:42Can I get a mortgage if my parents co-sign because of my poor credit?
Question of
the week: What are your tips for making our search for
a new home easier?
Answer: This was a question asked last week by a young couple
purchasing their first home. They were referred to me by her older brother and
were just beginning their home buying process. Here is the plan I laid out for
them.
The first thing I tell new
clients is to remember a few things. First, when meeting with mortgage
professional(s), real estate agent(s) or other service providers, you are
conducting job interviews. You will be working with these people for quite a
while, if you’re very lucky in finding the right home right away, are fully
qualified, you are looking at a month minimum. The home buying process is
somewhat emotional and you want to work with people you have confidence in
their ability, are experienced and that you trust.
Either the first or second
step was being taken care of, they were meeting with a mortgage professional.
Being that they are first time buyers, our initial meeting was about an hour.
We covered how mortgages work, the process once they have an accepted offer and
the relationship between price, down payment, mortgage amount, rates and costs
for closing. Then we got into their financial details to determine a purchase
price range and subsequent funds needed for closing and their monthly housing
payment.
With this information
exchange, they were comfortable with the financial aspects of their purchase
and we are able to generate a pre-approval package to accompany their offer
when they find the right home. My objective is that when you are looking at
homes in the price range we discussed you are focused on the properties and
their plusses and minuses and not wondering if you can afford the homes you are
considering.
If meeting with a mortgage
professional is not the first step, the first step should be to meet with a
licensed real estate professional. If you have not been pre-approved, or spoken
to a mortgage professional to determine a price for which you can qualify, I
advise that the initial meeting is to get to know one another. As mentioned,
this is a job interview. Ask how they like to work with buyers, what is their
process, when are they available to show you properties. If you have already
met with a mortgage professional, let them know and provide contact
information. If you have not met with me yet, please tell them that you have a
mortgage guy with over thirty years in the industry and you will be meeting
before you start looking at homes—unless you are out of state in which case I,
unfortunately, cannot assist you.
Until you know how much of a
home you can afford, an amount verified by a mortgage professional, do not
start looking at homes. Most experienced agents will not start showing new
potential clients homes until they hear from a lender letting the agent know
they are qualified, any potential issues being addressed and how much the
buyers can afford.
The obvious concern is you do
not want to look at homes for $750,000 and find out you can qualify for a
$650,000 home. However, we also have worked with many clients who were looking
at homes with prices significantly lower than what they can afford. They made
assumptions of what they can afford, or used simple on-line calculators, and
after our discussions with them and educating them on the process and how we
determine affordability adjust their sights a bit higher.
The next step I strongly
suggest for home buyers before starting to look for property is a Must
Have/Can’t Have list. If you are buying with your spouse or significant other I
advise that you each be very selfish. Go into separate rooms and make a list of
the three things, or less, that your home must have. Then make a list of three
things, or less, that if a home has this feature you absolutely will not buy
it. Then compare lists.
If there is something on your
“can’t have” that is on your spouse’s “must have” list then you need to have a
conversation because one of you might not be happy living in a home that either
has that feature or does not.
Ideally, your lists are
compatible and reasonable. When my wife and I were looking to purchase our
current home 20 years ago her only “must have” was a formal dining room. I
didn’t have a “must have” and my only “can’t have” was a rock roof.
Regarding the Can’t Have,
I have had agents express to me, “I’ve shown them fifteen houses that are
exactly what they say they want and they won’t write and offer.” I ask, “have
you asked them what the home can’t have?” No infrequently that solves the
problem, as the Can’t Have for some can be more important than the Must Have.
Make sure you let your agent know any features that will stop you from buying a
home, it will make your search easier. As well, if an agent continues to show
you homes with features that you have expressed are deal killers you may want
to look for another agent.
Once you have your list give
it to your real estate agent. With your list, knowing the price range for which
you qualify and the area where you would like to live, your agent should be
able to show you homes that are on the market the meet your criteria, or most
of it.
This is important—listen to
your agent. If your needs list, amount for which you qualify and area where you
wish to purchase do not match, then you need to make some changes in your
expectations. Every agent has the story of clients who wanted what was
impossible, essentially a $800,000 home with a $500,000 budget. The clients go
from agent to agent to agent being told, “that is not possible,” but refuse to
listen. These types of clients are still looking, only the house they could
have bought for $500,000 a few years ago now costs $575,000.
Finally, on the home search,
there is no perfect home. I have had clients have custom homes built and after
they moved in there were features they wish they had added, not put in or built
differently. Your objective is to get as close to your list as you can, but you
may need to make a few concessions.
Once you are all on the same
page be ready to buy. Your agent knows what you want, s/he knows what you can
afford and has been monitoring the market, and making calls to past clients,
for the home you want to buy. If s/he calls you on Tuesday and says, “I found
it and it went on the market today..” go see it that day or evening and do not
be afraid to write your offer!
One final point, this process
is about you. You will be getting advice from a lot of people, some involved in
the transaction, such are your agent and me (ideally); some not involved, such
are you co-worker or cousin Linda. I tell clients to always remember they are
in control, they make the decisions and everyone else reacts to those
decisions, and that three things are true, at least when it comes to me and
likely everyone else: 1) I am not spending any of my savings to buy your home
2) I am not going to dedicate any of my income to make your monthly payment 3)
I am not going to live in your home. All advice you get goes through that
filter—you are buying the home, paying for the home and living in the home,
your opinion is the one that matters most.
Working with homebuyers to
set up their purchase transaction and work with them through our closing of
escrow to become homeowners is something myself, and our company, excel at, as
thousands of homeowners in California can attest. We do not just punch numbers
and say, “this is how much you can buy.” We work closely with our clients to
ensure they understand the transaction, are comfortable with the financial
aspect of the purchase and have all their questions and concerns addressed.
If you know someone
considering a home purchase in the near, or even distant, future please have
them call me.
California
home sales a bit mixed. The California Association of Realtors released
sales data for September home sales. Total units sold statewide were down 0.5%
from August, but up 5.8% from last September, while the median price dropped
1.9% for the month to $605,680, which 4.7% higher than the median price in
September 2018. More locally, while total units sold in LA County was down 9.4%
from August, sales volume was up 9.2% from last year and the median priced home
in the county was up over $35,000 (5.6%) from August to $663,110, a 4.5% year
over year gain. Orange County has been up and down all year, due to smaller
number of sales and a wide spread in home values. In September the median home
price was $830,000, up 0.6% from August and a whopping 16.4% from 2018; the
number of units sold was down 9.1% from last year but up 2.5% from August. Low
rates are supporting the housing markets, which are tempered by high prices and
reducing inventory—active listings statewide are down almost twelve percent
from last September and the number of active listings has been falling for
three straight months.
Rates for
Friday October 25, 2019: We saw fractional improvement in the mortgage market
from last Friday, not enough to move the rate on the 30 year conforming rate,
but enough to drop the high-balance rate back to the more traditional 0.125%
(one-eighth of one percent) spread above the conforming rate. The market has
priced in a rate drop by the Fed next week. If the Fed does not change the rate
we can expect rates to pop up, if they drop the rate and release a statement
that somehow forebodes another rate decrease in the near future rates
may/should soften and perhaps dip a bit more.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.625% Flat
30 year high-balance conforming 4.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
This Indian
Summer in California, temperatures in the mid-90’s to 100’s depending on where
you live. In many parts of the country Indian Summer is when the thermometer
reaches mid-60’s to 70’s. We can complain about hot weather in October, but….when
our “cold days” are in the low 50’s during the winter how empty are those
complaints about our October temperature spikes?
The World
Series thus far has not gone as many expected, myself included. Being a
Phillies Phan I do not hold much love for the Nationals, but very much
appreciate the season they had after a horrible start and the way they play the
game. Speaking of which, no matter who your team is, if you are a baseball fan
you have to love to watch Jose Altuve of the Houston Astros play the game. I’m
still hoping for an Astros comeback, but I think I will be disappointed and
Washington will be hoisting a trophy and hosting a parade before the next
Weekly Rate & Market Update.
https://www.denniscsmith.com/wp-content/uploads/2018/10/moving_DennisCSmith.png800800Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-10-25 09:53:032019-10-25 09:53:06What are your tips for making our home search easier?
Question of
the week: Did I miss it; did I miss the rates bottom?
Answer: Maybe.
As you will see below rates
this week went up the most in one week since the week ending October 5, 2018.
When rates climbed at the end of last September they ended up peaking for about
a month before we had a long slide down (down every Friday for five of six
weeks).
Rate increases this sudden
and this high are rare but they do happen. Why? Usually rates jump up on very
positive economic news, political news, or a geopolitical event. This week the
trigger for the rate jump appears to be the nice-nice talk between China and
the United States on tariffs and trade agreements. This made investors positive
about American businesses and removal of a drag on the economy and they left
the safety of bonds and mortgages and bought equities, i.e. stocks in corporations.
Further pushing rates higher
was today’s news that August was a very strong month for consumer spending as
retail sales climbed 0.4% with a very large 1.8% increase in vehicle purchases.
Consumer spending is 65-70% of our economy and if the cash registers continue
to ring at a growing pace the economy will grow as well.
Also in the reports today was
that hourly earnings are up 3.2% year over year, well above inflation which
provides support for continued consumer spending.
All this good news in
negative for lower rates for several reasons, primarily they show an economy
that would be further away from the recession many pundits and media outlets
have been used to fill the airwaves, interwebs and newsprint. Secondly, the
potential of the trade war with China cooling down adds more support to pushing
out any possible recession even further.
Currently the mortgage
markets have priced in a rate cut of 0.25% by the Federal Reserve when it Open
Market Committee meets, what is uncertain is whether there will be more rate
cuts later this year. The economic and political news is making further cuts
somewhat more unlikely—which investors have also been reacting to as some have
been making decisions based on at least one further cut after next week.
If, for some reason the Fed
does not cut its benchmark rate next week be prepared for another spike in
rates.
So, did you miss the bottom?
For the short term it appears that it is likely you did. For the medium term
the answer is unknown as the current spike could be a sell-off to protect
profits, in which case they will slowly move back to bonds when they feel
equity markets are peaking, or near peaking.
All that said, even if you
missed the bottom rates are really, really good. The current rates are where
they were in July, which were near multi-year lows. If you have been
considering making a purchase or refinance for the bottom of the market, you
may want to consider doing so from the perspective of rates bouncing off what
may have been the bottom.
Typically
this section of the WR&MU covers what is happening in the economy that impacts
rates, today that was the first section!
Rates for
Friday September 1, 2019: We will see over the next week or two if the spike
in rates is a blip or a trend. I suggest not floating your rate and locking
when you are able to avoid further rate loss should rates bump up more.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.625% Up
0.25%
30 year high-balance conforming 4.00% Up 0.375%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Thank you to
everyone who sent happy anniversary issues to us last week. We had a great time
scheduling nothing to do every day and knocking that important item off our
to-do lists!
https://www.denniscsmith.com/wp-content/uploads/2017/06/interestRate_vs_APR.jpg162132Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-09-13 13:15:232019-09-13 13:15:26Did I miss it; did I miss the bottom for rates?
Question of
the week: When can we, should we, refinance?
Answer: A very popular
question recently and it was part of a lunch discussion I had yesterday with
two friends.
As for “when” you can
refinance, there is no time limit. I say that with some trepidation as many
lenders are faced with stiff penalties from the lender being paid off if the
payoff is too soon after the close of the loan. Unless you have a pre-payment
clause in your contract that has a fee if you payoff before a certain date you
can refinance when you are able.
It should be noted that if
you are paying off and closing a Home Equity Line of Credit (HELOC—see below
for more details on refinancing HELOCs) with your refinance you may face an “early
closure fee,” the amount and time limit for such a fee varies from lender to
lender.
As to the “should” you
refinance, it depends…does it “make sense” for you?
There are two types of
refinances, rate and term or cash-out.
A rate and term refinance is
one where you are not pulling any money out of the property and are refinancing
to reduce your monthly payment, change the terms of the loan from an adjustable
to a fixed rate or possibly from a 30 year to a 15 year or vice-versa, or
possibly reduce the monthly payment and eliminate mortgage insurance—in some
cases lower the monthly payment on mortgage insurance if it cannot be
eliminated.
The most common refinance is
a rate and term refinance from one 30-year fixed rate mortgage to a new 30-year
fixed rate mortgage. For these types of transactions, the “make sense” filter
we use is what is your tangible benefit? Will your monthly payment decrease by
5% or more? What will be the total cost of the refinance divided by the monthly
savings, is it less than 3 years?
Many reading the last sentence are thinking, aren’t
there ‘no cost’ refinances?
Everything has costs,
including “no cost refinances,” the question is how are the costs paid in a no
cost refi? In the March 29,
2019 Weekly Rate & Market Update we answered the question, “Do we have
to pay closing costs?” I do not want to recap the entire answer, but briefly
closing costs for a refinance can be paid by adding to the loan amount, your
bringing funds to escrow to pay them, or by your taking a higher interest rate
and the lender will pay them, or a portion some or all of these options.
What if you want to convert
your 30 year mortgage to a 15 year mortgage? This is a refinance some
homeowners like to consider prior to retirement so they will have their home
paid off when they retire, or shortly thereafter. The decision is usually not
as easy to make as it is when refinancing from one mortgage to another that has
the same term because a 15 year mortgage will have a much higher monthly
payment than a 30 year mortgage. Is it worth the costs to refinance to a
mortgage with a higher payment, or does it make more sense just to make larger
payments on your existing mortgage—or to put extra money into savings and
investments and use those funds to pay down or assist on payments when you do
retire?
For a rate and term refinance
the answer to “should we refinance” is very easily answered with math and the
assistance of my trust HP12C calculator to determine your new payments and
comparing them to your current payments.
Cash-out refinances involve a
different set of circumstances and therefore the decision is usually a bit more
challenging.
Why would someone take
cash-out of their property? There are many reasons, payoff debt, gift children
money to purchase their own home or for college, buy-out a partner in the
property or a business, use for remodeling, or perhaps for down payment on a
second home or income property.
One form of cash-out refinance
is paying off a HELOC*. The guidelines for conventional mortgages (Fannie
Mae/Freddie Mac) are that unless the HELOC, or other 2nd lien, was
used to purchase the property a refinance that includes paying off a HELOC is
considered “cash-out.” For many jumbo programs, if you have not accessed the
line of credit in the past 12 months they will consider the refinance a rate
and term transaction. Note that many jumbo lenders will loan down to the conforming
loan limit plus one-dollar (total $484,351) so homeowners with a high-balance
loan amount can benefit from the more generous jumbo guidelines if paying off a
HELOC that has not been accessed for a year or more.
Does it make sense to
refinance to consolidate your HELOC into a one mortgage with your current
primary mortgage? It depends on the math, your comfort with likely having your
payment increase, how risk averse you are to potential/probable higher rates on
the HELOC in the future and your ability, willingness and actions in paying
down the HELOC.
A typical transaction on a
refinance to payoff a HELOC can look like this. A couple have a home worth
$650,000 and have a primary mortgage of $350,000 at 3.75% that was $400,000
when they bought the home and has a payment of about $1800 per month. They have
a HELOC with a $100,000 balance that was used to remodel their kitchen, the
rate is currently Prime (5.25%) plus 1.5% for a rate of 6.75%. The payment on
the HELOC is interest only, about $560 per month. Every month they intend to
make payments to pay down the balance but never really do. Should they
refinance?
If they get a 4.25% rate (a
sample rate, not today’s rate which may be higher or lower depending on many
factors) for a $450,000 mortgage ($400,000 primary + $100,000 HELOC), the
payment would be about $2215 per month. Currently the couple is paying $2360
per month with no reduction in the HELOC balance—this makes sense.
But what if the math was
different, they are paying $2500 per month now and a refinance would be $3000
total per month, does that “make sense?” Now we discuss with the client how
comfortable they are with the adjustable aspect of the HELOC, when and how they
intend to pay off the balance. Eventually the HELOC will no longer be interest
only and be amortized over a ten or fifteen year period (much higher payments)
or a balloon payment will be due and it will need to be paid with cash or a
refinance. Now the decision is not so easy.
Like most Questions of the
Week, there is no standard answer of “should we refinance?” The math often
provides the clearest answer, but some situations are more complicated than
others.
Making the decision easier
for many homeowners is the very low interest rates currently available.
If you have been asking
yourself, or others, the question as to whether to refinance or not, call me
and I’ll do you math and go through your options.
Not so fast…That is the
message from the first revision to the Gross Domestic Product (GDP—essentially
the measure of the U.S. economy) revised economic growth in the 2nd
quarter down from 2.1% to 2.0%. The more detailed report than the initial GDP
estimate was interesting in that it showed very robust consumer spending in the
quarter and GDP growth has dampened by fewer exports and less business
investment. Between the lower investments and higher consumer spending U.S.
businesses saw profits grow pre-tax by 5.3% in the quarter—the largest increase
in five years. Overall the revision has no impact on mortgage rates.
Buy big. That was the
sentiment for the American consumer in July as consumer spending increased 0.6%
in July from June, such grow can be described as “robust.” Leading the way in
spending was a strong increase in new car and truck sales—and RVs! To make
their purchases consumers dipped into savings (the savings rate falling from a
high of 8% to 7.7%) as personal income rose only 0.1% for the month—giving employers
a breather in the steady wage increases seen over the past year or so due to
the tight labor markets. Inflation for the month saw prices increase 0.2% with
prices up 1.4% from last July; well below the Fed’s 2.0% target giving some
support to those in the Fed who want to lower rates in September. The news is
mixed for mortgage rates; the consumer spending is negative for rates as
spending is 65-70% of GDP, the inflation news is positive for rates as it fuels
speculation the Fed will lower rates and investors will act accordingly.
Rates for
Friday August 23, 2019: Early in the week rates paired the pop in rate last
week and we touch our multi-year low once again this Friday.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.375% Down
0.125%
30 year high-balance conforming 3.625% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Twenty-five
years ago on Labor Day weekend I was playing golf with some friends and
relatives on Saturday, then a nice family dinner. Monday, I woke up late, which
is unusual, and heavy headed but very happy. In between, on Sunday, I spent the
morning and midday trying to relax because I had a 4:00 appointment with Leslie
in the backyard with about 25-30 others. Somewhere close to 4:00 Leslie’s dad
escorted her across the lawn where he dropped off next to me and in front of
the minister.
Our anniversary
is this coming Wednesday, but Labor Day weekend is always memorable for me for one
of the shortest sentences I have ever uttered, and by far the wisest, “I do.”
https://www.denniscsmith.com/wp-content/uploads/2018/10/legal_DennisCSmith.png800800Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-08-30 13:57:422019-08-30 13:57:45When can we, should we, refinance
Answer: We have a lot
of first time buyers entering the real estate market, which means a lot of
people unfamiliar with the terminology and different services in the industry.
This question was asked to me this week by a young couple purchasing their
first home. They have heard, “when you open escrow, when you close escrow,” but
what is this “escrow” they will be opening and closing?
Dictionary.com defines escrow
as “a contract, deed,
bond, or other
written agreement deposited with
a third person,
by whom it
is to be delivered to the
grantee or promisee
on the fulfillment
of some condition.”
By
this definition escrow is a third person with whom a contract is
deposited. For a contract to be valid it
needs two parties, so part of the contract must be that both parties agree who
will be the escrow, the holder of their contract.
In
real estate, escrow is a third party that buyer and seller, or in the case of a
refinance the borrower and the lender, use to transact funds from one party to
the next; escrow is also referred to as the settlement agent. Given instructions agreed to by both parties,
the escrow holder agrees to accept funds from the buyer, and the buyer’s lender
if necessary, and then after paying costs for other services involved in the
transaction, deliver the funds to the seller once all promises are fulfilled in
exchange for a grant deed from the seller that is delivered to the buyer.
Escrow
is neutral and has no agency contract with the buyer or seller, its agency is
with the transaction. A simpler way to
look at this is that the Smiths are selling their home to the Joneses. The Smiths are represented by Mary as their
real estate agent and the Joneses are represented by Joe as their real estate
agent. Once an agreement to price and
terms is made an escrow account is opened with Sally at the escrow company, at
that point Sally is the agent of the transaction representing the agreement the
Smiths and the Joneses made.
If
the Joneses wish to make a change to the agreement, say have $3000 credited to
them to off-set some repair costs discovered during their home inspection, they
notify Sally at the escrow company.
Sally cannot just change the terms of the transaction, she first must
get consent from the Smiths for the credit.
Once both parties agree to any changes then Sally can amend the
transaction.
Escrow
plays a vital role in real estate transactions.
Large sums of money flow through escrow companies on a daily basis for
purchase and refinance transactions.
Escrow is not only charged with making sure the initial instructions are
followed but also that neither party is able to change the transaction without
the consent of the other. At closing,
escrow is responsible for disbursing funds to all the parties and services
involved in the transaction, refunding overages to buyers or borrowers, pay
fees to termite, title, home warranty, lender and themselves, payoff any liens
currently on the property such as the seller’s mortgage or tax obligation and
transmit the net proceeds to the seller.
After the closing escrow provides a very detailed accounting of all
funds received and disbursed to all parties.
Escrow
companies and officers in California can be independent of any other
affiliation or may be part of a title company or owned and operated by a real
estate brokerage. If the escrow company
for a purchase transaction is owned by the real estate broker representing the
buyer or seller this must be disclosed to all parties.
Agents
and lenders cannot require that a particular escrow company be used on any
transaction; buyers and sellers have the opportunity to request a specific
company if they choose, though it is customary in our marketplace the seller,
or the seller’s agent, is given the choice of this service.
A
good escrow officer and company is like a good umpire in a baseball game, you
don’t always know how good they are until you get a bad one; thankfully the
latter are very few and far between these days.
For
the first-time buyers, all buyers, opening escrow is great news as it means your
offer to purchase your new home was accepted. Closing escrow is even greater
news as it means you now own your new home!
No worries
here. The Consumer Price Index for July showed that prices for consumers rose
0.3% for all goods and services and also for the “core” rate (gas and food are
stripped out). For the past twelve months, the CPI is up 1.8%, which could be
labelled a very benign inflation number. If price growth continues to decline
there will be more support for the Fed to lower rates, however the last several
CPI releases have shown a pretty steady rate of price growth just below 2%. The
news is mortgage rate neutral.
What me
worry? Says the American economy after the Commerce Department released retail
sales data for July. July saw the largest one month increase in retail sales in
four months at 0.7% above June’s sales. Taking out car and gasoline sales for
the month and sales increased 0.9% for the month, with on-line sales jumping a
staggering 2.8% from June—likely boosted (shoved up?) by Amazon’s Prime Day and
its competitors also pushing their own deals available. Evidently the trade
dispute with China is not preventing consumers from buying products, nor is it
increasing the prices paid for those products. Overall the news should be
negative for lower interest rates as consumer spending is 65-70% of our economy
and strong retail sales should portend economic growth and higher rates.
Rates for
Friday August 16, 2019: Look at the pretty charts! Chart makers who track stocks
and bonds had a fun week as they created what looked like silhouettes of
mountain ranges with peaks and valleys. As I write this the Dow is down about
0.875% for the week and the S&P is down 3.67% since Monday’s open. In
between we say a large peak on Tuesday and a deep valley on Thursday. All the
while the rate on the 10-year Treasury dropped into mid-week before bouncing a
bit today. Why all the activity? Concerns about a recession and European
economies caused investors to sell of their equity holdings and purchase bonds
and fixed rate investments—engaging in flight to safety (as discussed in the July 26th WR&MU).
As discussed above, the concerns appear to be unfounded, however the result of
the recession concerns is a dip in rates this week from last Friday, and the
conforming rate at its lowest since the week ending December 9, 2016. Can they
go lower?
FIXED RATE MORTGAGES
AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.375% Down
0.125%
30 year high-balance conforming 3.625% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Long time
readers of the WR&MU know that this is the space I use to comment on
personal events in me and my family’s life—for some I know this is the only
part you read! (As an aside, my dad was very old school and could not
understand why I always wrote this final segment—when I informed him it was
probably the most read section, “Oh, then you should probably keep it.” Good
advice.) This week these section is for parents of new adults.
Do you have a
son or daughter who recently turned 18, or any children you still provide for
over 18? Then please read on. Last year when our oldest daughter, then 18, flew
off to Boston for college, before she left I had her sign two copies of a HIPAA
Release Form (link below). Because she is an adult, no medical provider can
provide either my wife or I any medical information about her. Should she have
an accident or emergency and we are contacted that an event has occurred,
federal law prohibits the medical provider from releasing any details.
With she and us
each having signed copies of the HIPAA release form that we can provide the
medical provider authorizing them to communicate with Leslie and I, they will
be able to provide us with details of her condition, etc. We also have an
electronic copy that we can quickly send to a healthcare facility across the
country to expedite the information collection.
If you have any
children 18 or older I encourage you to have them complete the form linked
below and provide you with an original or copy. As well, if they are in college
and/or living with roommates, encourage them to inform their roommate(s) of the
form and where it is located (and to have them complete one for their parents).
Privacy laws are very important to protect us, the HIPAA laws however can be
detrimental for parents who need information and be able to be pro-active in
their adult children’s healthcare.
Here is a link
to the HIPPA
Release Form we use. I hope none of us ever need to use it.
https://www.denniscsmith.com/wp-content/uploads/2017/06/overview.jpg118177Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-08-16 12:48:102019-08-16 12:48:16What is Escrow?
Answer: On I-94 West
leaving Milwaukee and heading to Steamboat Lake, Minnesota (near Walker, near
Bimidji).
Leslie has command of the
rental Hyundai Tuscon at 7:45 local time while I spend a few minutes getting
out the big economic news this week and rate shift.
As expected, the Federal Reserve cut its benchmark
rate by 0.25% on Wednesday—that move was already priced into the markets. After
the announcement Fed Chair Jerome Powell held a press conference and his
answers to some of the questions set the markets into a tizzy. The general
expectation has been that the Fed would lower rates up to three-quarters of one
percent this year (0.75%). At his news conference Powell indicated that
Wednesday’s rate move could be a one-and-done, made to put some confidence into
the economy. Sensing no more cheap money to borrow to buy, investors dumped
their stock holdings and purchased bonds (see last
week’s WR&MU for brief overview of relationship between stocks and
bonds). This sent stocks prices and bond and mortgage rates tumbling. It should
be noted this is the first time since the financial crisis of 2008 that the Fed
has increased rates, the second longest period in history—the longest being
from 1942 to 1954.
But wait, there’s more! In reaction to the markets collapse in
2008 the Fed began a policy known as “quantitative easing” during which it
purchased U.S. Treasury bonds and Mortgage Backed Securities (MBS) to soak up
supply and keep rates low. Last year the Fed announced a policy of “quantitative
tightening.” Under this policy the Fed would start to sell its holdings of U.S.
Treasury debt and mortgages. The impact of this policy is to tighten interest
rates by lowering the prices on fixed rate assets, which as we learned last
week pushes rates up. Originally the policy was to stay in effect for two more
months, but the Fed cut the cycle by two months.
In other news…Economic data this week was counter to
the Fed’s position of an economy that needs outside stimulus with lower rates.
Positive economic news should lead to higher interest rates, ahead of the Fed
rate cut we learned that consumer spending (65-70% of our economy) increased
0.3% in June and for the fifth month in a row personal income showed growth,
increasing 0.4% for the month and up 3.2% from last year. With the gap between
personal income growth and spending growth it is not a surprise that personal
savings also increased, to 8.1%. Inflation concerns, a key factor for interest
rates, are non-existent as prices increased a scant 0.1% in June and are up
only 1.4% from last June; well, well below the Fed’s 2.0% inflation target. The
inflation number is the only number that would hint at a rate increase, the
other data all suggests an economy that is on track to continue record
expansion that began in June 2009.
Lost in all
the chatter about the Fed announcement will be today’s report from the Labor
Department that the economy added another 164,000 jobs in July. More news that
would suggest rates stay steady or face some upward pressure.
Rates for
Friday August 2, 2019: The conforming rate is the lowest it has been since
October 2016, hitting 3.5% this week following the Fed move and more
importantly Powell’s comments. Will they last? Economic principles say no, and
that they should not be this low.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.50% Down
0.25%
30 year high-balance conforming 3.75% Down 0.125%
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Why Milwaukee?
Why not? Leslie and I are having a Planes, Trains and Automobiles summer trip.
We flew to Oakland last Saturday evening and the next morning board the
California Zephyr train headed for Chicago. The trip was beautiful, though a
bit challenging at night as we opted for the small “sleepette” compartment
rather than a sleeper. We crossed the Sierras and Rockies during the day and we
really enjoyed the ride. Two nights in Chicago which included a fantastic meal
with friends one night and “obstructed view” seats the next night to see
Hamilton—a huge discount in price for seats near the back of the mezzanine that
blocked the upper part of the stage—rarely used and no negative impact on our
enjoyment.
In plotting our
trip with the ultimate destination being Camp Birchwood, where one daughter has
been since May as a counselor and the other there since early July as a camper,
we saw Milwaukee was not out of the way for our automobile leg of the trip.
Since neither of us had ever been we decided to make a stop. We are glad we
did! A nice lunch river side, a great walk through the lake side part of the
city to a fun and tasty Irish pub, then a walk back to our hotel had us wishing
we scheduled a bit more time in the city.
The next two
nights a Camp Birchwood, which is owned and run by a man who was my counselor
at the camp when I was young, and was started by his father who was my dad’s
counselor when he was a kid. We fly home from Minneapolis on Monday with our girls
to complete the trip.
https://www.denniscsmith.com/wp-content/uploads/2017/06/creditScore.jpg162132Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-08-02 07:29:312019-08-02 07:29:35Where are you?
Question of the week: What has the
biggest impact on mortgage rates?
Answer: News.
Political news, geo-political
news and economic news impacts interest rates.
Mortgage rates are the result
of investors either buying or selling fixed rate financial instruments—i.e.
bonds and investments that behave like bonds such as long-term mortgages, which
are bundled and sold as Mortgage Backed Securities (MBS). Interest rates move
inversely to the price of the bond, or MBS. If more investors are selling MBS
then prices will drop, which will push mortgage rates up; if more investors are
purchasing MBS then prices will rise, which will push mortgage rates down.
What determines whether investors
will be buying or selling? Extrapolation, anticipation, historical behavior,
expectation and speculation. If you knew that a certain piece of news would benefit
DCSmith Industries creating more sales and revenue, you would buy stock with
the expectation the value of the stock would rise, increasing your investment.
If after you own the stock there is some news expected to come out, or that has
just come out, that would be detrimental to DCSmith Industries harming revenue
you would sell the stock to retain your gains.
Investors do exactly that,
except for fixed rate investments the information processed to anticipate
whether prices should go up or down on bonds and MBS is different than the
information processed to forecast future prices for individual companies. News
is the currency of investors when it comes to fixed rate investment. And good
news is bad and bad news is good when it comes to higher or lower rates.
Generally speaking, investors
have two choices. They can trade equities (stocks in individual companies) or
fixed rate instruments—bonds, mortgages. Historically, if equity markets are
rising in price, fixed rate investments are dropping in price because investors
sell their fixed rate investments to purchase the equities. The opposite is
also true, if investors are selling equities they will generally take the sale
proceeds and purchase fixed rate investments.
Good news creates a positive
economic environment that boosts growth, and therefore sales and revenue of companies.
With the expectations that the growth will create more value for private companies,
with higher dividends and stock prices, investors will increase purchase of
equities causing prices to increase.
This activity will reduce the
demand for bond and MBS, causing prices to drop and rates to increase. Further
influencing the lower demand for these investments is that strong economic
growth historically has led to central banks, like the Federal Reserve, will
increase their rates to slow growth and keep inflation in control. If they know
this is the reaction of the central bank when economies are showing strong
growth, investors will react by being even more reticent to buy or continue to
hold bonds since their prices should drop, reducing their profits or creating
losses. If they anticipate prices dropping further, why should they buy?
At some point the rates of
return on the long-term fixed investments become high enough, therefore the
prices low enough, that investors will start to return to these investments,
slowing rate increases and potentially reversing the trend.
Bad news has the reverse
effect. Individual company stocks and equity markets in generally are typically
a lot more volatile than fixed rate investments. This creates a situation where
prices in equity markets can swing wildly day-to-day, or even within one day,
as we have seen several times in recent history. Extremely bad news, such as the
outbreak of armed conflict, will create an environment known as “flight to
quality.” “Quality” is synonymous with “fixed rate investments.” If you
purchase an investment that will pay you 4% of the purchase price every year
for ten, fifteen, thirty years, you know exactly what you will be receiving for
your investment—there is almost no risk if it is backed by the United States Treasury.
This is known as a quality investment. Conversely, purchasing stock in an individual
company has risks, no matter the history or strength of the company. Think of
major U.S. corporations that seemingly would never go out of business or see
its value drop considerably, Blockbuster and Kodak did not adapt to technology
and investors who held onto their stock lost a lot of money; Pan Am and Eastern
were very strong world-wide brands that are no longer a brand of any kind except
historical; Woolworths, Arthur Anderson,
Lehman Brothers…all these companies at one point, and for a long period of
time, were leaders in their fields and industries but investors in these companies
lost their investments—or most of them. Such is the risk to individual companies
to bad economies, bad events and bad behavior by corporate leaders.
Because of the inherent risk
in equities, when bad news occurs, or appears about to occur, we see the
behavior of “flight to quality” with bond prices climbing and rates dropping.
Every week, in the section
below this in the WR&MU I provide important news that impacts mortgage
rates. If news is good, I comment the news is bad, or not good, for lower
rates; if the news is not so good it should lead to lower rates. Historically,
this has been the relationship between news and events and interest rates.
Historically is the key word
as for the past several years our historical models and behavior have not
always applied to the news, events and data that should put either upward or downward
pressure on rates. As a result, despite the longest post-recession economic
recovery in our nation’s history, rates are still significantly lower than they
were pre-recession, and lower than several times during the recovery.
Just remember, if you are
getting ready to borrow money for your new home, or to refinance your current
one, bad news is good for you as it should lead to lower rates, and good news
is bad. Selfishly, you are somewhat hopeful for some sort of bad news just
before you lock your interest rate.
This explanation of what
impacts mortgage rates and their rise or fall has been very general, there are many,
many other issues, but I hope the generalization has been helpful.
Good news or bad news? The first
estimate of Gross Domestic Product growth for the second quarter of 2019 showed
the economy grew at an annual pace of 2.1%. This growth was one-percent lower
than the first quarter’s growth, but a bit higher than most economists predicted.
Is the slowing growth good or bad news? On the one hand, it is good news as the
quarter showed the spending by consumers in one quarter since 2017. On the
other hand, it is not good news as holding down total economic growth was
slowing in business growth as manufacturers and exporters invested less in
fixed capital (buildings, tools, etc) as they took a wait-and-see approach to
new investments as the trade talks and tension with China and other nations
created uncertainty. Consumer spending is approximately 65-70% of our GDP, and
the strong showing should have reflected growth of at least 3%; however the
strong decline in business investment counter-acted the consumer—and appears to
be the primary reason the Fed is looking to increase interest rates.
Rates for
Friday July 26, 2019: The
GDP news had little impact on rates today and we are flat for the third Friday
in a row. If the Fed does raise interest rates next week, the increase is
pretty much already priced into mortgage rates and the announcement should have
little impact on rates.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.75% Flat
30 year high-balance conforming 4.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
Our summer heat
has finally arrived in Southern California, which means our pool is finally not
too cold for me to take the occasional dip. I am no fan of cold water, which I consider
to be anything below about 72-3 degrees. The “you’ll get used to it” line has
never held true for me!
Stay cool, stay
hydrated and make sure you have plentiful and fresh water for you pets.
https://www.denniscsmith.com/wp-content/uploads/2018/10/cash_income_DennisCSmith.png800800Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-07-26 14:58:292019-07-26 14:58:33What has the biggest impact on mortgage rates?
Question of the week: Do you have a
will and a trust?
Answer: This is one
of the recurring topics in the Weekly Rate & Market Update, and it is time
to revisit it again.
It is coming up this week because
in the last few weeks I have run across quite a few professionals in various
industries, banking, insurance, financial services and even an attorney, who
have not prepared a will and trust. All have property, some have children, and
all have referred clients and friends to attorneys with the advice they need to
have a plan for their estates.
Physician, heal thyself—patients
take heed to what the doctor advises but not how the physician behaves….
For those of you who have a
proper estate plan you may wish to skip the rest of this section of the
WR&MU, for those who do not I encourage you to read on.
Many people feel that
preparing a will and trust is not something they need to do at this time in their
lives, they are “too young,” or “do not own enough to bother,” or one of my
favorites, “my family will take care of it,” which is a nice burden to put on
one’s family.
If you were hit by a bus
today what happens? What happens will depend on many things, are you married,
do you have joint assets with a non-spouse, do you have children, and very
importantly do you have a legal document that spells out what you want to
happen? The last phrase would be a will and trust.
One question I asked married
couples with children who do not have an estate plan is, “if you were both to
die at the same time, what happens to your children? Whose parents, sister or
brother would raise them, care for them, ensure their continued education and well-being?”
I then add that without a
plan in place, that all family members know about, there is a decent chance
that the in-laws may stage a battle of custody of their grandchildren/nieces/nephews.
Consider the children have had their parents die and now are in the middle of
legal battle between their two sets of grandparents, or uncles and aunts, over
where they get to live.
If you have children you are
likely having a pretty grim vision of your own children and relatives. Unless
you have a plan in place spelling out who will have custody of your children,
who will be the executor of your estate and ensure that your assets are
properly protected and used for the continued well-being of your children until
they reach a certain age at which they will have access to what assets may be
left in the estate.
If you have children, whether
you own property or not, having a written legal directive spelling out your
desires should you and your spouse become incapacitated for your children and
assets is a must. If you do not have a plan in place the decision will be made
by the state, which means family court, which will take a lot of time, cost a
fair amount of money, and not be beneficial to your children and perhaps
detrimental to the family members who may be contesting custody.
One of the primary benefits
of having a trust is the avoidance of probate. If someone dies without a will
outlining how an estate is to be settled then a judge in probate court will
make the decisions. Usually a family will hire an attorney to act as their
agent for the proceedings and process. The costs can be very high for probate,
a lot higher than the cost of having a will and trust prepared, unless of
course one of the surviving family members has the time and ability to go
through the filing process, court time, etc. Speaking of court time, per friend
and attorney Greg Burnight when I asked how long probate is taking in Los
Angeles County, “It is almost impossible to close an estate through probate in
less than nine to ten months. More often it is a year or so without any real
hiccups.” That is a long time for your children to be waiting to find out which
relative they will permanently be living with if there is a contest.
The probate process exists
whether you are married, single, co-habitating, have children, own real estate,
are young or old. If you die and do not have a will chances are your estate
will go through probate. The “I am not old enough,” “We don’t have kids,” reasons
people give not to prepare a will and trust are not valid—it is something adults
need to do and is essential for parents with minor children.
One more point, as I have
mentioned before, proper estate planning comes at a cost. There are some areas
of our lives where we can look for “deals” or “savings” or cut back. Estate
planning is not one of these areas. Look for savings on airline tickets and
hotels, new workout shoes or a vehicle purchase, do not look to save money and
get a bargain on securing your estate. As I have told many clients over the
years when discussing the topic, you will never know if your will and estate
plan was properly prepared, fulfilled your intentions and spared your family
time and resources while grieving your passing. But they will know, and the
frustration, challenges and cost to them may tarnish their memory of you and
the legacy you wish to leave behind.
If you have an estate plan
make sure you review and have it revised from time to time. Our oldest daughter
is now an adult, our estate plan was therefore not current resulting in our
consulting with an attorney who specializes in the field to make the necessary
revisions so we can be at ease knowing if the tragic were to occur our children
will be looked after.
Open your calendar and schedule
a for some time next week to call a will and estate planning attorney. If you
do not know one and would like recommendations please call or email me.
Is inflation
tame or not? I often say, “math doesn’t lie.” Two plus two is always four, the square
root of 169 is always 13 and 4% of $500,000 is always $20,000 (I use a
calculator for the hard ones). But absent math, numbers can be subject to
interpretation. Take the June Consumer Price Index, which showed prices
increasing 0.1% for the month and 1.6% year over year. These numbers show that
inflation is pretty tame, and below the desired 2% inflation target set by the
Federal Reserve. Change the calculation for prices pay for goods and services
by eliminating food and energy costs (call the “core” rate) and the scaled down
basket of items increases 0.3% for the month and is up 2.15% for the year—above
the Fed target. The discrepancy is due to falling energy prices in June and
rising costs for rents, clothing and automobiles (especially used).
Traditionally the Fed uses the core rate of inflation when making monetary
decisions, such as whether to raise its benchmark interest rate. If tradition
were followed the CPI data for June would be a negative for rates and possible
higher rates.
Tradition! Tradition!***
A lot of market activity this week because of the release of the minutes
from the most recent meeting of the Federal Reserve Open Market Committee
(FOMC). The minutes show that the majority of voting members favor lowering
interest rates due to “risks and uncertainties” that weigh on economic outlook
for future growth. In testimony before Congress this week Fed Chair Jerome
Powell indicated that the business confidence survey in May appears to be a
reason the Fed will likely cut rates before the end of the month. Lost in the
reasoning for cutting rates is reference to data. In terms of data, there is
little that indicates a cut in rates is necessary. Historically, traditionally,
when the core inflation rate is at or above 2%, when labor markets are tight
and rates are increasing, and when GDP continues growing, the expectation is
more towards higher rates to dampen possible future inflation. As the holder of
a degree in economics and having studied the field for several decades, I find
the potential action by the Fed based on surveys and perceived uncertainties to
be untenable. The Fed news is generally good for rates in the long-term, and
has already been priced into our rates. The result of the rate decrease, likely
a boost to equity markets and a weakening dollar, can lead to higher rates. ***see
bottom of update
Rates for
Friday July 12, 2019: With the contradiction between data and public
comments from the Fed rates have jumped around this week, and there are some
large variances amongst the lenders we use. As we close out this Friday, rates
are flat from last Friday. The market is choppy, my advice is to lock
when you can and not risk rates jumping while you are waiting to see if they go
lower.
FIXED RATE
MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year
conforming
3.75% Flat
30 year high-balance conforming 4.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
***One of my
favorite musicals (I love musicals) is “Fiddler on the Roof.” In 7th
grade I was part of the chorus and dance cast for the musical at school, I was
not that great but I’m not sure any other kid like the music and story as much
as I did. Fast forward, I was fortunate to see Zero Mostel play Tevye at the
Winter Garden Theater in 1977 when my mom took me out of school for a Wednesday
matinee. For many, many years, when I hear, see or write “tradition” I sing to
myself the song from Fiddler on the Roof.
https://www.denniscsmith.com/wp-content/uploads/2017/06/dollfamily.jpg178276Dennis C Smithhttps://www.denniscsmith.com/wp-content/uploads/2024/06/dennis-c-smith2.pngDennis C Smith2019-07-12 15:03:282019-07-12 15:03:31Do you have a will and a trust?