
Posts

About that property tax bill…

This week’s question of the week is a repeat from last October, however the topic is one I feel should be addressed every year for homeowners in California.

Question of the week:  We just received our property tax bill…

 Answer:  Okay, okay this is not a question; it is the start of a question. There are several phrases to make it a question I will quickly go through this week:

…why is it lower than you estimated when we purchased our home earlier this year?

…why is it higher than last year since we are under Proposition 13?

…how much should we pay?

…why is it lower than you estimated when we purchased our home earlier this year?

If your property tax bill is significantly less than my estimates when we funded the loan to purchase your home then you will very likely receive a supplemental tax bill, if you have not received one already and the two bills added together, the tax bill you have just received from the County where your property is located and the supplemental tax bill, should be close to the estimate we used when you purchased your home.

In California, the fiscal year is from July 1st to June 30th. The tax bill property owners have received in the past week from their County Assessor has an option of paying half the bill by December 10th covering first half taxes from July 1st to December 31st and the other half by April 10th covering the second half taxes from January 1st to June 30th. The tax bill mailed in September or October is based on the prior tax bill as adjusted for Prop 13, or if there was a transfer the value on January 1st.

When you purchase a property the tax base for the property is adjusted based on your purchase price. Depending on when you purchased the property the new value may not be adjusted by the County Assessor before the tax rolls are set for the coming fiscal year. If this is the case the tax bill you have received reflects the prior assessed value plus and adjustments for Prop 13 (see below) or additional payments for taxes or bonds put in place by voters or local government. This is the primary reason your tax bill is probably lower than you anticipated, and why you will receive, or have received, a supplemental tax bill.

The supplemental tax bill covers the difference between the taxes on the tax bill and the taxes you should be paying from the date of the close of escrow on your property purchase to the end of the fiscal year, June 30th. Depending on the seller’s assessed value and your purchase price the supplemental bill can be very large, very small, or even “negative,” in which case you will receive a refund from the County.

Supplemental tax bills are only mailed a few times a year, so it may be some time after you closed your purchase before you receive your supplemental bill. Please note, if you have an impound account and your lender is collecting and paying your property taxes that your supplemental bill is not sent the supplemental tax bill, the payment is entirely your responsibility.

Confused? Let’s say you purchased a home for $650,000 and closed escrow on February 7th. Using our rule of thumb of your property taxes being 1.25% of the purchase price your annual taxes the first year of ownership should be $8,125 per year ($4062.50 for the first and second half tax bills). Your seller purchased the property in 2000 for $375,000 and their assessed value has risen through the years and their tax bill the year they sold the property was $5500. You just received your first property tax bill from your County Assessor and it shows you owe $5610 conveniently payable in two payments of $2805 each.

There is a difference in annual taxes between what you should be paying and what you are being billed of $2625. However, this will not be the amount of your supplemental tax bill as that is the annual property tax differential and you only owned the property since February 7th, not July 1st of the prior year. There are 143 days between February 7th and June 30th, and that is the period which the higher assessed value should be applied for property taxes. Therefore, your supplemental tax bill will be the annual property tax differential divided by 360 days multiplied by the number of days you owned the property between the sale date and end of the tax year:

$2625/360 = $7.29 per day x 143 days = $1042.71 as your supplemental bill.

Note that depending on your closing date you may receive more than one supplemental bill.

It can get pretty confusing, however most County Assessor websites have links where you can input your address, sales price and closing date and it will calculate your estimated supplemental tax bill.

…why is it higher than last year since we are under Proposition 13? Prop 13 was passed at the ballot box by California voters on June 6, 1978. There were three major items in the measure that immediately impacted property owners in 1978. First, it decreased assessed values by having all properties in California re-assessed to their assessed values in 1976. Second, it capped the assessed value of real property taxes by to the state at 1% of the ad valorem value of the property, i.e. the transaction value. Third, it limited increases to assessed values to an inflation index but not to exceed two percent (2.00%) per year.

It is the third factor that confuses many new or experienced property owners when they receive their property tax bill that the total is higher than what they paid the year before. Since property values are increasing your assessed value is increasing as well, but not more than two percent above the assessed value from the prior year.

Also surprised are those property owners who do not follow the news or politics. Their surprises come in the form of special assessments put on tax bills by either voters or elected officials in the form of bonds or taxes. For instance for our home in Long Beach we have nine such assessments that add 29% to our base tax rate of one-percent. Three of the assessments are local bonds for the Metro Water District, Long Beach Community College District and the Long Beach Unified School District; the other six are county measures and bonds for parks, flood control, sanitation, etcetera. Every city and county has different special assessments on their property tax bills that are added to the one-percent maximum taxable assessment from the state.

…how much should we pay? 

Before I answer here is the disclaimer: I am not a tax professional or accountant, before you make any decision as to how much you should pay in property taxes this year consult your tax preparer.

In December 2017, the federal tax reform was enacted in Washington D.C. Part of the new tax act was capping the deduction for State And Local Taxes (SALT) to $10,000. This impacts residents and homeowners in several states, including California. Why bring this up? Some individuals or families may want to consider paying their first and second half property taxes in 2019 if they will not reach the $10,000 limit in SALT paid in 2019 and predict they may exceed it next year. Before making this decision consult with  your tax preparer who can review your options and help you forecast next year’s income and possible tax liabilities for 2020.

Repeating my disclosure: I am not a tax professional. Before making any decisions regarding our taxes please consult with your tax preparer.

If you own property I strongly recommend you have two professionals assist you: a family law attorney to help you establish an estate plan with a trust and a professional tax preparer to ensure you are maximizing your tax opportunities as well as able to provide advice when needed.

If you have any questions on property taxes please do not hesitate to contact me and I will assist you the best I can.

If you, or someone you know, do not currently pay property taxes I am very willing and able to speak with you about how you can purchase property and become a homeowner!

Have a question? Ask me!

After last week’s busy economic calendar this week saw little in the way of major economic data that would have big impact on rates. What did have markets moving was announcement from Chinese government late Wednesday that China and the U.S. were very near a phase 1 agreement to rollback some tariffs. This made equity markets happy and bonds, mortgages sold to purchase stocks—stocks up, rates up. The news was called premature by the U.S. and was seen as a negotiating ploy by the Chinese to put pressure on the White House to take whatever China has on the table to announce a deal. Stocks sold, bonds and mortgages bought. So the see-saw in markets continues to go up and down based on rumors, announcements and tweets regarding the Sino-American trade dispute.

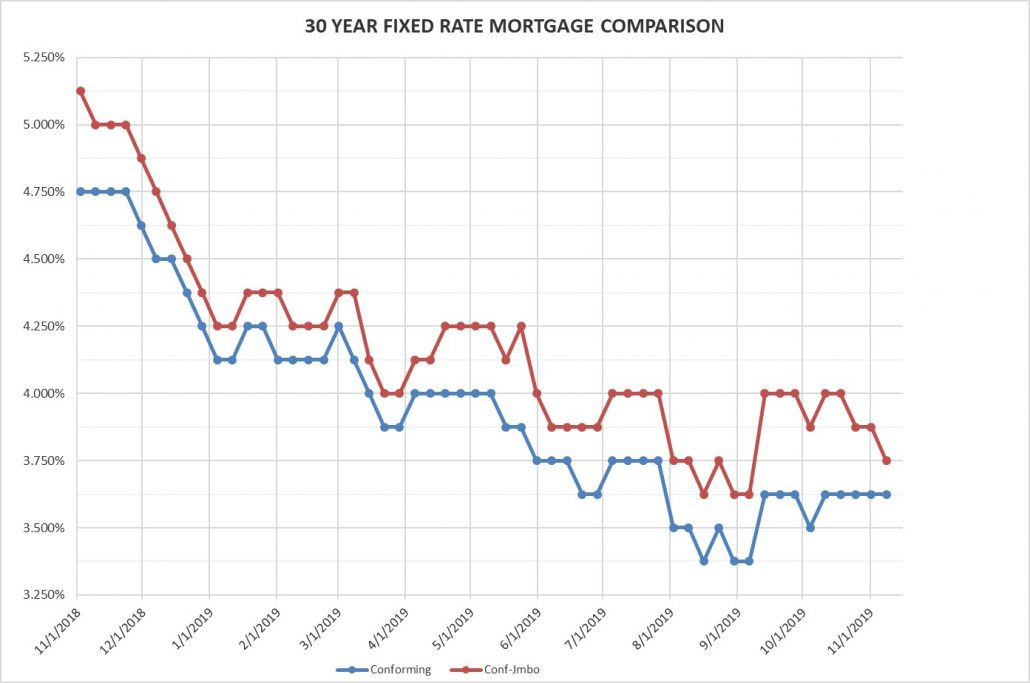
Rates for Friday November 8, 2019: After the inter- and intra-day ups and downs the conforming rate is flat for the fourth Friday in a row. The high-balance has dropped this week at two of our lenders. Why with some lenders but not others? Lenders have a bit of restriction on what percentage of their mortgages with Fannie Mae and Freddie Mac can be “high-balance” (over $484,350 and in LA and Orange Counties no higher than $726,525). When lenders are near the threshold they raise their rates on these loans, if they are not near their lending limit they lower their rates. The advantage Stratis Financial has is we can sift through several lenders to see who is offer what rates on any given day for any give product.

Rates and markets are still “edgy” to news and views, my advice is not to try to hit “the low,” but lock in your rate as soon as you are able.

FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.625%     Flat

30 year high-balance conforming                    3.75%      Down 0.125%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
I don’t understand how when we travel to other time zones I almost instantly adapt to the new time, but when we change our clocks at home my rhythm gets messed up for several days. Maybe I should pretend I have travelled somewhere in the fall and spring when we shift our time pieces!

Have a great week,

Dennis

Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog
10-12-18: We just received our property tax bill…

Question of the week:  We just received our property tax bill…


 Answer:  Okay, okay this is not a question; it is the start of a question. There are several phrases to make it a question I will quickly go through this week:


…why is it lower than you estimated when we purchased our home earlier this year?


…why is it higher than last year since we are under Proposition 13?


…how much should we pay?


…why is it lower than you estimated when we purchased our home earlier this year?


If your property tax bill is significantly less than my estimates when we funded the loan to purchase your home then you will very likely receive a supplemental tax bill, if you have not received one already and the two bills added together, the tax bill you have just received from the County where your property is located and the supplemental tax bill, should be close to the estimate we used when you purchased your home.


In California the fiscal year is from July 1st to June 30th. The tax bill property owners have received in the past week from their County Assessor has an option of paying half the bill by December 10th covering first half taxes from July 1st to December 31st and the other half by April 10th covering the second half taxes from January 1st to June 30th. The tax bill mailed in September or October is based on the prior tax bill as adjusted for Prop 13, or if there was a transfer the value on January 1st.


When you purchase a property the tax base for the property is adjusted based on your purchase price. Depending on when you purchased the property the new value may not be adjusted by the County Assessor before the tax rolls are set for the coming fiscal year. If this is the case the tax bill you have received reflects the prior assessed value plus and adjustments for Prop 13 (see below) or additional payments for taxes or bonds put in place by voters or local government. This is the primary reason your tax bill is probably lower than you anticipated, and why you will receive, or have received, a supplemental tax bill.


The supplemental tax bill covers the difference between the taxes on the tax bill and the taxes you should be paying from the date of the close of escrow on  your property purchase to the end of the fiscal year, June 30th. Depending on the seller’s assessed value and your purchase price the supplemental bill can be very large, very small, or even “negative,” in which case you will receive a refund from the County.


Supplemental tax bills are only mailed a few times a year, so it may be some time after you closed your purchase before you receive your supplemental bill. Please note, if you have an impound account and your lender is collecting and paying your property taxes that your supplemental bill is not sent the supplemental tax bill, the payment is entirely your responsibility.


Confused? Let’s say you purchased a home for $650,000 and closed escrow on February 7th. Using our rule of thumb of your property taxes being 1.25% of the purchase price your annual taxes the first year of ownership should be $8,125 per year ($4062.50 for the first and second half tax bills). Your seller purchased the property in 2000 for $375,000 and their assessed value has risen through the years and their tax bill the year they sold the property was $5500. You just received your first property tax bill from your County Assessor and it shows you owe $5610 conveniently payable in two payments of $2805 each.


There is a difference in annual taxes between what you should be paying and what you are being billed of $2625. However this will not be the amount of your supplemental tax bill as that is the annual property tax differential and you only owned the property since February 7th, not July 1st of the prior year. There are 143 days between February 7th and June 30th, and that is the period which the higher assessed value should be applied for property taxes. Therefore your supplemental tax bill will be the annual property tax differential divided by 360 days multiplied by the number of days you owned the property between the sale date and end of the tax year:


$2625/360 = $7.29 per day x 143 days = $1042.71 as your supplemental bill.


Note that depending on your closing date you may receive more than one supplemental bill.


It can get pretty confusing, however most County Assessor websites have links where you can input your address, sales price and closing date and it will calculate your estimated supplemental tax bill.


…why is it higher than last year since we are under Proposition 13? Prop 13 was passed at the ballot box by California voters on June 6, 1978. There were three major items in the measure that immediately impacted property owners in 1978. First, it decreased assessed values by having all properties in California re-assessed to their assessed values in 1976. Second, it capped the assessed value of real property taxes by to the state at 1% of the ad valorem value of the property, i.e. the transaction value. Third, it limited increases to assessed values to an inflation index but not to exceed two percent (2.00%) per year.


It is the third factor that confuses many new or experienced property owners when they receive their property tax bill that the total is higher than what they paid the year before. Since property values are increasing your assessed value is increasing as well, but not more than two percent above the assessed value from the prior year.


Also surprised are those property owners who do not follow the news or politics. Their surprises come in the form of special assessments put on tax bills by either voters or elected officials in the form of bonds or taxes. For instance for our home in Long Beach we have nine such assessments that add 29% to our base tax rate of one-percent. Three of the assessments are local bonds for the Metro Water District, Long Beach Community College District and the Long Beach Unified School District; the other six are county measures and bonds for parks, flood control, sanitation, etcetera. Every city and county has different special assessments on their property tax bills that are added to the one-percent maximum taxable assessment from the state.


…how much should we pay?  The first question, “how much should we pay?” is a follow up to my Weekly Rate & Market Update from December 22, 2017 after the new tax law was passed that limited SALT (State And Local Tax) deductions to $10,000 per year. In the WR&MU the question was given the reduction in ability to deduct California state income tax and property taxes to a cap of $10,000, did it make sense for California property owners to pay both the first (due by December 10th) and second (due by April 10th) half taxes in 2017, which would result in most property owners who did this paying three half year tax year bills in 2017 (2nd half of 2016-17 in April 2017, 1st half of 2017-18 in December 2017 and 2nd half of 2017-18 in December 2017) thereby maximizing their property tax deductions. The advice from my CPA tax preparer friends Lew Finkelstein and Paul Scholz was, “depends” as some clients would not benefit from the additional half-year of taxes deduction if they were under the Alternative Minimum Tax (AMT) zone for 2017. For most people however it did make sense to pre-pay the April 10th payment and get the deduction.


What about this year? Before I answer here is the disclaimer: I am not a tax professional or accountant, before you make any decision as to how much you should pay in property taxes this year consult your tax preparer.


If you did pay the second half of your property taxes in 2017 instead of in April of this year, your property tax payment due by December 10th will be your first property tax payment of the year. Should you also pay the second half bill due by April 10, 2019? Again, it depends. If you pay just the first half payment, will your total of property taxes paid plus state income taxes be less than or more than $10,000? If your total is less than $10,000 you may want to go ahead and pay both first and second half property taxes in December to maximize your deduction; if your total is more than $10,000 you may want to pay the second half taxes next year in April when due—which means in 2019 you will again be over the $10,000 limit but at least you will not have a double tax payment in December when you may need the extra cash for the holidays.


Confused? Let’s say your annual tax bill is $6,000, you owe $3000 by December 10th and another $3000 by April 10th. You paid the full property tax bill in December of last year, so this year you have paid no property taxes. As a household your state income taxes for 2018 are approximately $8000 for the year. You have to pay your first half tax bill of $3000, so you will have paid a total of $11,000 in SALT (State And Local Taxes, i.e. income and property taxes) and can only deduct $10,000 on your federal taxes, so you have lost $1000 in deductions you used to get. If you pay the full $6000 then you will pay a total of $14,000 in SALT, can only deduct $10,000 so lose $4000 in deductions you used to get.


If you just pay the first half, in April you will have to pay $3000 for the second half taxes, in December you will have to pay the first half taxes for 2019-20, assuming it increases the maximum amount (2%, see above) that payment will be $3060 for a total of $6060 paid in property taxes in 2019. If your state income tax bill is the same, $8000, then you will have paid $14,060 in SALT and be able to deduct only $10,000 so you have $4060 you miss in deductions.  Provided there are no changes to the tax bill that increases SALT deductions.


The question you want to answer is do you want to have deductions left on the table this year or next year if the laws do not change? Personally, I will only pay the first half taxes this year and see if there is some political deal to revise the SALT deductions for 2019—I doubt there will be but we never know since there will be a new Congress starting in January.


Repeating my disclosure: I am not a tax professional. Before making any decisions regarding our taxes please consult with your tax preparer.


If you own property I strongly recommend you have two professionals assist you: a family law attorney to help you establish an estate plan with a trust and a professional tax preparer to ensure you are maximizing your tax opportunities as well as able to provide advice when needed.


If you have any questions on property taxes please do not hesitate to contact me and I will assist you the best I can.


If you, or someone you know, do not currently pay property taxes I am very willing and able to speak with you about how you can purchase property and become a homeowner!


Have a question? Ask me!


Prices are still under control. Strong increases in prices are still anticipated by many economists and analysts, as they have been for the bulk of the year, but have yet to manifest in the market place as inflation still remains under 3%. After dropping 0.1% in August, the Producer Price Index rose 0.2% in September and year over year wholesale prices are up 2.6%, the increase was in goods and services as food and gasoline prices both dropped nationally in September. On the consumer side the Consumer Price Index increased 0.1% in September, less than anticipated and slower than August’s increase of 0.2%. Year over year consumer prices are up 2.3%, a drop from August’s 2.7% annualized increase in prices. The most significant push on higher prices in September were higher costs for renters and home owners. Good news in the report was the after inflation wages for workers rose 0.3% in September and year over year are up 0.5%. The report is the basis for 2019 CPI adjustments for the government and it has been reported that social security benefits will increase 2.8% next year. Over all the price news is neutral for mortgage rates.


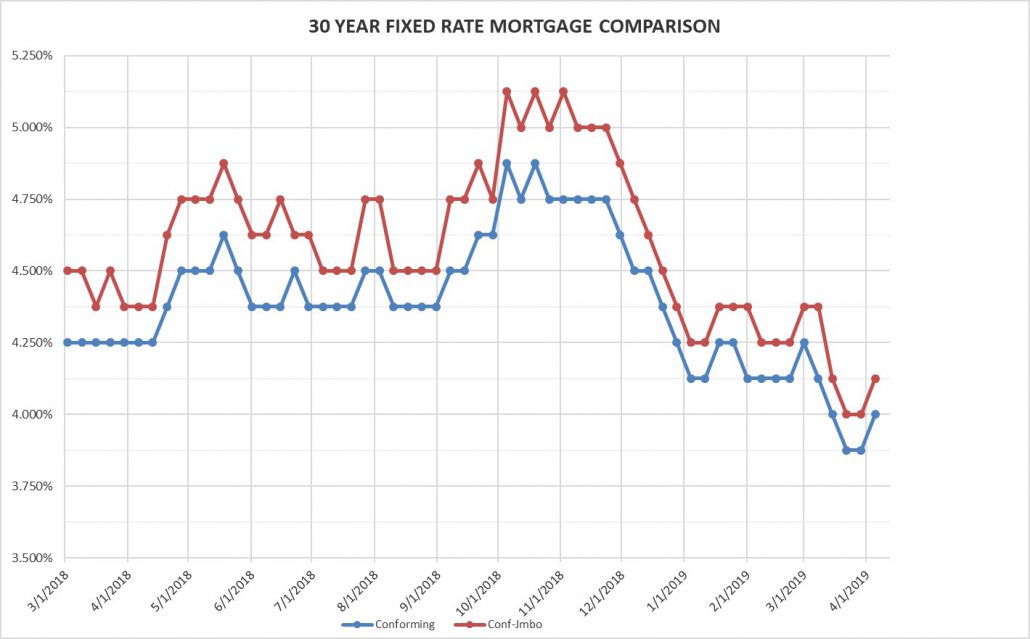
Rates for Friday October 12, 2018: A see-saw week for mortgage rates this week as investors ran to and fro with their money reacting to Fed-speak and speculation the Fed will increase rate by one-half of one percent (0.5%) in December instead of the anticipated one-quarter of one percent (0.25%) and have four rate increases next year instead of three. As well the drop in stock prices this week caused many investors to put some of their proceeds from selling their equity holdings into bonds—though it appears most of the money went into cash. We have a volatile rate environment, now is not the time to float your rate or try to time a dip, lock your rate when you can. All that said, rates are down slightly after last week’s spike late in the week.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.75%    Down 0.125%

30 year high-balance conforming                    5.00%     Down 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


Is it me or does it seem like Hurricane Michael had little of the pre- and post-landfall coverage that Florence received last month? Michael was the strongest hurricane to hit the United States mainland in over fifty years and the power of the storm is very evident in the pictures we are now seeing. Whole groves of trees snapped in half, houses not only flattened but blown completely away. The devastation looks more like a tornado than a hurricane, but with a significantly larger impact area. Several times a year it seems I post this link in the WR&MU, here it is again, if you are able please make a donation of any size to the American Red Cross who does incredible work assisting those impacted by disasters.


Have a great week,


Dennis

1-19-18: What are supplemental taxes


Question of the week: What are supplemental taxes?


Answer:  This is a question many buyers ask, whether first time buyers or someone purchasing for the first time in a long time.


Before we talk about supplemental property taxes we need to review property taxes. To keep this discussion simple, we are only addressing taxes when a home is purchased.


Your property taxes are established when you purchase your home and are based upon the purchase price. The base tax rate in California is 1% of the purchase price. On top of the 1% are additional assessments as established by the voters or elected officials in the county and/or city where the property is located. For instance in Long Beach there are additional taxes assessed for water district, the county for parks, school district and community college district among other assessments.


The rule of thumb for property taxes is the amount is 1.25% of the purchase price of the property. If you purchase a property for $500,000 we estimate your taxes to be $6250 per year.


In California, the fiscal year is July 1st to June 30th. Tax bills are mailed in October with the first half taxes due by December 10th and the second half taxes due by April 10th. With our $500,000 price example, you would need to pay $3,125 in December and $3,125 in April.


If you are purchasing a home and close on the last day of February the escrow company make sure the second half taxes, due by April 10th, are paid as part of the closing. The taxes that will be paid will be those currently due; i.e. the current owner’s tax bill. As well the escrow company will collect from you and reimburse the seller for four months of taxes since you will own the property the final four months of the tax year—March, April, May and June.


On the property you are purchasing for $500,000 that will have property taxes of $6,250 the current owner’s annual taxes at the time of the sale are $3,850 per year. At closing you will be charged $1283.33 to cover the four months between your purchasing the property and the end of the tax year on June 30th.


In October your property tax bill will state that you owe a total of $3,850, half due by December 10th and half by April 10th.


But…your tax basis is supposed to be $6250, why is your tax bill smaller? Because if you purchase your property between January and May the prior owner’s property taxes will continue through the next fiscal year.


You will also receive a supplemental tax bill in the amount of $2400 with half due by December 10th and half by April 10th. The supplemental taxes cover the difference between the amount you were billed based on the prior owner’s tax obligation and your tax obligation based upon the transfer price.


If you are paying your taxes directly this causes little difficulty, you are paying the total amount that is owed, just off of two different bills, the regular tax bill and the supplemental.


If you have your taxes impounded as part of your monthly mortgage payment then it gets a little tricky. Your lender will be collecting every month based upon what your taxes should be, $520.83 per month, and will be prepared to pay $3,250 in December and $3,250 in April. However, in October the lender will receive a tax bill totaling $3,850 with two installments due.


This is where it can, and does, get tricky and one reason I encourage people to avoid having their taxes and insurance impounded and paid by the lender if it is an option. In this scenario, with an impound account, you will have paid your lender $520.83 per month based on what tax obligation will be, and then your lender will pay the taxes owed on the tax bill. The result will be a balance of the excess between what was collected and what was paid. At some point the lender will refund this money to you, as they must by law.


However, the refund will most likely come after you will need to pay your supplemental tax bill totaling $2400. If you are impounded and have paid the full amount to the lender for the taxes why is the lender not paying the supplemental tax bill? They have the money to pay it.


Because the county assessor does not send the supplemental tax bill to your lender, and you are responsible for the payment. Essentially you will end up paying the supplemental amount twice, once to the lender—which eventually gets refunded—and once to the county.


If you have an impound account there is the possibility that your payments will be adjusted a few times over the following year or more. Because the tax bill sent to the lender was significantly less than the amount collected, the lenders automated billing process may reduce the amount owed every month as part of the tax collection and will send you a notice to this effect.


It is very important if you do get this notice that you contact the lender and inform them that you do not want your impound collection to be lowered due to the one-time tax bill that was paid at the prior owner’s tax rate, because if you do then you will be underpaid when the next tax bill is sent and the lender will end up sending you a notice that the account is short and your payment must be increased to account not only for the real tax amount due but the shortage created by them adjusting their collections.


Confusing isn’t it? This happens not infrequently as the lender tries to catch up to the actual taxes owed. So if you get a notice after the first tax bills have been paid by the lender, and you have paid your supplemental taxes that significantly lowers your tax collection for your impound account contact your lender immediately and have them adjust the collection back to the necessary amount.


As with any mortgage or real estate related question or problem you can contact me if you are having an issue regarding the supplemental taxes or impound account I can help walk you through the process and steps to take.


Have a question? Ask me!


Rates for Friday January 19, 2018: Not a lot of economic news this week to move rates, however there was movement up on high-balance and upward pressure on conforming due to the gains in the stock markets. As I write this after noon on Friday the bond markets are off (higher rates) due to uncertainty over the potential shutdown of the Federal government. Now is not the time to float your rate, if you are in position to lock in your rate through your closing period I suggest you lock.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.875%       Flat

30 year high-balance conforming                       4.125%        Up 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


I had an interesting childhood moving around (three states and a foreign country through high school), as a result I have what some may consider odd allegiances for sports—basically the Oklahoma Sooners due to my native state and Philadelphia sports as that is where we moved when we left Oklahoma. Being a fan of Philly sports is a history of disappointment most of the time with some seasons of hope.


As a result of my allegiances, I have been somewhat excited through December as first the Sooners had the opportunity to play for the national championship in college football and now the Eagles are in position to go to the Super Bowl for the first time since 2005. The Eagles (or Iggles in local parlance) lost that game to Tom Brady and the Patriots who won their second Super Bowl in a row and third in four years. I may be asking for it, but I am hoping not only that the Eagles beat the Vikings this weekend, but they have a chance to upset the Patriots, prevent them from repeating history by winning their second in a row and third in four years.


I know all of you are with me on this!


Have a great week,


Dennis

Fly Eagles Fly


Weekly Rate & Market Update 11-3-17: Should we be worried about the new tax plan that will cut the mortgage deduction?

 Question of the week:  Should we be worried about the new tax plan that will cut the mortgage deduction?


Answer:  With the biggest tax reform plan working its way through the House of Representatives and the Senate it is no surprise that various aspects of what have been released and talked about so far have been a hot conversation topic. Last week at meeting with a group of professionals from family law attorneys to CPAs to business owners we discussed various parts of what had been floated through the media for almost an hour. The only consensus was that we were debating what we don’t know since until both houses in Congress agree on a bill, pass it and present it to the President everything is negotiable.


That said….the two features of the plan presented to the House of Representatives that impacts the housing markets are deductions for mortgage interest and property taxes; under the plan released this week both would be reduced from the current tax code allowable deductions.


Currently if you own a home with a mortgage you have the opportunity to deduct the interest paid on the mortgage and property taxes. “Opportunity” basically means there are limitations on the deductions. First, in order to claim deductions for property taxes and mortgage interest on your primary (and possible second/vacation home) residence you must itemize your deductions and they must exceed the standard deduction given to tax filers (for married couples $12,700 in 2017). If you meet these criteria then you can deduct all property taxes paid to the local tax authority. Second, a married couple can deduct interest paid on a mortgage used to acquire, build or substantially improve the property up to one million dollars of mortgage liens. For example if you own a home with a $1.3 million mortgage at 4% interest you can deduct $40,000 in interest paid, not the full $52,000 you actually paid in interest.


The current plan that will be debated in the House and put through many separate committees before a final bill is presented for a vote increases the standard deduction to $24,000 for married couples and limits the mortgage interest deduction to interest paid on mortgages up to $500,000 and the property tax deduction to a total of $10,000.


What does this mean in plain English and simple math?


Before we do some math, let’s answer the question: What is a tax deduction? Many people confuse a tax deduction with a tax credit, the difference is that deduction is an amount that reduces your taxable income and a credit is an amount that reduces your tax obligation.


Note I am not a tax professional, all examples are very fundamental calculations and used for comparative purposes only.


For example if you and your spouse make $80,000 and file your taxes with the standard deduction of $12,700 for 2017. Before the deduction your tax bracket is the 25% tier based on your $80,000 taxable income. After the tax bracket your taxable income drops to $67,300, and your top out at the 15% tax bracket. The deduction saves you approximately $2300 in federal income tax from about $11,500 without any deduction to approximately $9200 after the standard deduction is applied.


The deduction lowers your income, which can change your upper tax bracket and lowers your tax liability.


A tax credit is applied to your income tax liability directly after your taxes are calculated. Using the same couple above, during the year they installed energy efficient rated windows for a total of $4000. The federal tax code allows a credit of 10% of qualified windows installed on a primary residence, up to a maximum of $200. This lowers the tax obligation from about $9200 to $9000—the credit results in a direct reduction of taxes owed.


Back to the tax proposal.


Currently if you have a mortgage used to purchase your home with a balance of $600,000 and a rate of 4% you will pay approximately $24,000 in mortgage interest. Since this exceed the standard deduction for a married couple, is a mortgage on your primary residence and the mortgage is under $1 million you can deduct the $24,000 from your income when you file your taxes.


To qualify for the $600,000 you may make around $140,000 as a couple. Taking the interest deduction you taxable income drops from $140,000 to $116,000. You are still in the 25% tax bracket, absent any other deductions, so you save 25% of $24,000 in taxes, or $6,000.


Under the new proposal you will only be able to deduct the interest on the first $500,000 of the mortgage, $20,000, so you lose $4000 in deductions from your income. In this scenario your tax obligation will drop $5000 instead of $6000 so the tax proposal as written costs you $1000 more in taxes for the year.


Similar calculations can be made for property taxes if your annual tax bill exceeds the proposed $10,000 limit.


A couple of points regarding this discussion. First, tax reform is constant in our nation’s history. Every President and Congress from 1789 has passed changes to the tax code, some small and some quite major. Any changes in the tax code made by the current 115th Congress and signed into law by President Trump will be subject to future changes as a result of elections changing members of Congress and residents of the White House.


Second, at this stage in the process everything is negotiable. What is in the tax plan today may not be in the tax plan tomorrow. What items in the plan are in there for purposes of negotiation? If some members of Congress want the mortgage interest and property tax deductions levels to increase what are they willing to give up to get their way? Increase the proposed corporate tax rate? Change the elimination of the estate tax to a higher level of tax exemption?


Third, in California we look at taxes in a whole different light than most of the country for a couple of reasons. Our property values are significantly higher than most of the country so our mortgages are higher and our property taxes are higher in dollars paid (several states have higher percentage of property taxes) so limiting those deduction will impact Californians more than those who own homes in Oklahoma, Utah or Kentucky. So, while collectively we may be against the reduction in the deduction limits for interest and property taxes in California, through much of the country the limitations have little to no impact and is more than offset by the increase in the standard deduction. We are represented by 53 Representatives (12% of the total) and two Senators (2% of the total), and while it is the largest state contingent in Congress it still represents just 12% of the population and many Representatives and Senators representing the 88% of the population see more advantages to their constituents than detriments.


Taxes are the ultimate political tool and tax reform is only political. As the plan works through Congress I am going to assume that the mortgage interest and property taxes proposals will be amended—maybe trade a higher mortgage deduction for eliminating the property tax deduction, or raise both limits and trade for something else, or…..the Republican majority cannot keep the party members together and the plan collapses completely and we see no changes to the tax code.


At this point it is all speculation, I hope I have been able to present a fairly clear and understandable example of the potential impact of the proposed changes to the tax plan that could impact California homeowners that you can use to sort out future proposals and potential personal impact.


Have a question? Ask me!


Remember, with Dennis it’s not just a mortgage, it’s your complete financial picture.


The first week of the month means labor data. October saw Americans earning more and spending more—both good news for the economy—but prices are stagnant—which is not great news. Workers saw income increase 0.4% for the month and led by a surge in durable good spending due to hurricanes increased spending by 1% from September. Prices were flat going up only 0.1% for the month and 1.3% from last October, well below the Fed’s inflation rate. The news is mixed for mortgage rates as the stronger earnings and spending would tend to push rates up but the low prices keep rates down.


More workers, a lot more, is the news from the Labor Department’s October report. Total payrolls increased by 261,000 workers, 252,000 in the private sector. This is a very large increase, however much of it is the result of those displaced by hurricanes going back to work. For example, restaurants lost 98,000 workers in September and gained 89,000 in October. There was a dark cloud in the report and that is wages not increasing for the month. Overall the report is mortgage rate neutral.


Big news for the Federal Reserve yesterday when Trump nominated Jerome Powell to replace Fed chief Janet Yellen when her term expires in February. Powell is considered a moderate and unlikely to change any current policies of the Federal Reserve is confirmed for the post by the Senate.


Rates for Friday November 3, 2017: Rates are flat for conforming and dip back down on high balance loans after ticking up last week. All eyes, ears and noses are focused on Congress and the debates, negotiations and horse-trading over the tax bill. Depending on what moves through the process investors may react by fleeing to safety, rates drop, or loading up on equities in private companies, rates increase. Stay tuned, there should be plenty for office water cooler and weekend barbecue discussions.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            3.75%           Flat

30 year high-balance conforming                   3.875%        Down 0.125%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


What was more depressing for you, the outcome of the Game 7 or the amount of candy left over in your bowl for Trick-or-Treaters on Tuesday night? My disappointment was less in the outcome of the game on Tuesday than the lack of a great game that kept us on the edge of our seats all night. Congratulations to the Astros. Two things for baseball fans, right now every team is tied for first place, including my Phillies, and its only 102 until pitchers and catchers begin to report for Spring Training!


Have a great week,


Dennis