


Do you have a will and a trust?
Question of the week: Do you have a will and a trust?
Answer: This is one of the recurring topics in the Weekly Rate & Market Update, and it is time to revisit it again.
It is coming up this week because in the last few weeks I have run across quite a few professionals in various industries, banking, insurance, financial services and even an attorney, who have not prepared a will and trust. All have property, some have children, and all have referred clients and friends to attorneys with the advice they need to have a plan for their estates.
Physician, heal thyself—patients take heed to what the doctor advises but not how the physician behaves….
For those of you who have a proper estate plan you may wish to skip the rest of this section of the WR&MU, for those who do not I encourage you to read on.
Many people feel that preparing a will and trust is not something they need to do at this time in their lives, they are “too young,” or “do not own enough to bother,” or one of my favorites, “my family will take care of it,” which is a nice burden to put on one’s family.
If you were hit by a bus today what happens? What happens will depend on many things, are you married, do you have joint assets with a non-spouse, do you have children, and very importantly do you have a legal document that spells out what you want to happen? The last phrase would be a will and trust.
One question I asked married couples with children who do not have an estate plan is, “if you were both to die at the same time, what happens to your children? Whose parents, sister or brother would raise them, care for them, ensure their continued education and well-being?”
I then add that without a plan in place, that all family members know about, there is a decent chance that the in-laws may stage a battle of custody of their grandchildren/nieces/nephews. Consider the children have had their parents die and now are in the middle of legal battle between their two sets of grandparents, or uncles and aunts, over where they get to live.
If you have children you are likely having a pretty grim vision of your own children and relatives. Unless you have a plan in place spelling out who will have custody of your children, who will be the executor of your estate and ensure that your assets are properly protected and used for the continued well-being of your children until they reach a certain age at which they will have access to what assets may be left in the estate.
If you have children, whether you own property or not, having a written legal directive spelling out your desires should you and your spouse become incapacitated for your children and assets is a must. If you do not have a plan in place the decision will be made by the state, which means family court, which will take a lot of time, cost a fair amount of money, and not be beneficial to your children and perhaps detrimental to the family members who may be contesting custody.
One of the primary benefits of having a trust is the avoidance of probate. If someone dies without a will outlining how an estate is to be settled then a judge in probate court will make the decisions. Usually a family will hire an attorney to act as their agent for the proceedings and process. The costs can be very high for probate, a lot higher than the cost of having a will and trust prepared, unless of course one of the surviving family members has the time and ability to go through the filing process, court time, etc. Speaking of court time, per friend and attorney Greg Burnight when I asked how long probate is taking in Los Angeles County, “It is almost impossible to close an estate through probate in less than nine to ten months. More often it is a year or so without any real hiccups.” That is a long time for your children to be waiting to find out which relative they will permanently be living with if there is a contest.
The probate process exists whether you are married, single, co-habitating, have children, own real estate, are young or old. If you die and do not have a will chances are your estate will go through probate. The “I am not old enough,” “We don’t have kids,” reasons people give not to prepare a will and trust are not valid—it is something adults need to do and is essential for parents with minor children.
One more point, as I have mentioned before, proper estate planning comes at a cost. There are some areas of our lives where we can look for “deals” or “savings” or cut back. Estate planning is not one of these areas. Look for savings on airline tickets and hotels, new workout shoes or a vehicle purchase, do not look to save money and get a bargain on securing your estate. As I have told many clients over the years when discussing the topic, you will never know if your will and estate plan was properly prepared, fulfilled your intentions and spared your family time and resources while grieving your passing. But they will know, and the frustration, challenges and cost to them may tarnish their memory of you and the legacy you wish to leave behind.
If you have an estate plan make sure you review and have it revised from time to time. Our oldest daughter is now an adult, our estate plan was therefore not current resulting in our consulting with an attorney who specializes in the field to make the necessary revisions so we can be at ease knowing if the tragic were to occur our children will be looked after.
Open your calendar and schedule a for some time next week to call a will and estate planning attorney. If you do not know one and would like recommendations please call or email me.
Have a question? Ask me!
Is inflation tame or not? I often say, “math doesn’t lie.” Two plus two is always four, the square root of 169 is always 13 and 4% of $500,000 is always $20,000 (I use a calculator for the hard ones). But absent math, numbers can be subject to interpretation. Take the June Consumer Price Index, which showed prices increasing 0.1% for the month and 1.6% year over year. These numbers show that inflation is pretty tame, and below the desired 2% inflation target set by the Federal Reserve. Change the calculation for prices pay for goods and services by eliminating food and energy costs (call the “core” rate) and the scaled down basket of items increases 0.3% for the month and is up 2.15% for the year—above the Fed target. The discrepancy is due to falling energy prices in June and rising costs for rents, clothing and automobiles (especially used). Traditionally the Fed uses the core rate of inflation when making monetary decisions, such as whether to raise its benchmark interest rate. If tradition were followed the CPI data for June would be a negative for rates and possible higher rates.
Tradition! Tradition!*** A lot of market activity this week because of the release of the minutes from the most recent meeting of the Federal Reserve Open Market Committee (FOMC). The minutes show that the majority of voting members favor lowering interest rates due to “risks and uncertainties” that weigh on economic outlook for future growth. In testimony before Congress this week Fed Chair Jerome Powell indicated that the business confidence survey in May appears to be a reason the Fed will likely cut rates before the end of the month. Lost in the reasoning for cutting rates is reference to data. In terms of data, there is little that indicates a cut in rates is necessary. Historically, traditionally, when the core inflation rate is at or above 2%, when labor markets are tight and rates are increasing, and when GDP continues growing, the expectation is more towards higher rates to dampen possible future inflation. As the holder of a degree in economics and having studied the field for several decades, I find the potential action by the Fed based on surveys and perceived uncertainties to be untenable. The Fed news is generally good for rates in the long-term, and has already been priced into our rates. The result of the rate decrease, likely a boost to equity markets and a weakening dollar, can lead to higher rates. ***see bottom of update
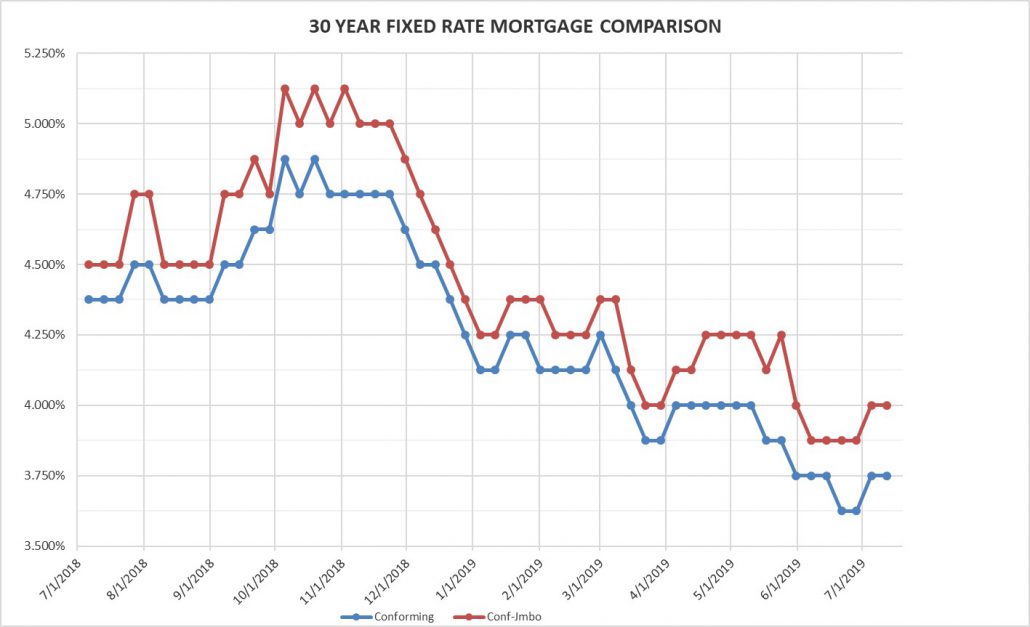
Rates for Friday July 12, 2019: With the contradiction between data and public comments from the Fed rates have jumped around this week, and there are some large variances amongst the lenders we use. As we close out this Friday, rates are flat from last Friday. The market is choppy, my advice is to lock when you can and not risk rates jumping while you are waiting to see if they go lower.
FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:
30 year conforming 3.75% Flat
30 year high-balance conforming 4.00% Flat
Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.
***One of my favorite musicals (I love musicals) is “Fiddler on the Roof.” In 7th grade I was part of the chorus and dance cast for the musical at school, I was not that great but I’m not sure any other kid like the music and story as much as I did. Fast forward, I was fortunate to see Zero Mostel play Tevye at the Winter Garden Theater in 1977 when my mom took me out of school for a Wednesday matinee. For many, many years, when I hear, see or write “tradition” I sing to myself the song from Fiddler on the Roof.
Have a great week,
Dennis
Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog

