Posts

1-4-19: What is 2019 looking like for Stratis Financial?

Question of the week:  What is 2019 looking like for Stratis Financial?


Answer:  Exciting! We spent the last quarter of 2018 adding some new lender partners to expand our portfolio of mortgage products well beyond our foundational products of conventional and jumbo 30-year fixed rate mortgages. Our new lenders bring alternative products that can benefit self-employed borrowers, borrowers with extremely high-net worth and borrowers looking to secure housing through retirement. With our growth in lending options we can cover pretty much any mortgage need for residential homeowners or home buyers in the state of California.


Personally, I am excited to add a new relationship referral source that will enable me to be assist more families with their mortgage needs as well as strengthen my connections with past clients and referral sources.


From you I am looking for inquiries for your mortgage needs and plenty of questions to answer for you in 2019, please ask and I will answer and help you with solutions and options!


Have a question? Ask me!


Job growth and economic growth seem to be going in different directions. In the last revision for 3rd quarter 2018 Gross Domestic Product output the rate of growth was 3.4%, down from the prior quarter’s growth of 4.2%, current forecasts for the 1st quarter of 2019 are economic growth in the U.S. economy growing less than 3%. The data shows economic growth is slowing. In a seeming anomaly, during this slowing growth period employers have not been slowing their hiring practices, as evidence by today’s report on December employment from the Department of Labor. Blowing away forecasts, employers added 312,000 new jobs in December, the consensus forecast of economists surveyed by MarketWatch was an addition of 182,000 jobs. Also included in the report were upward revisions to the job growth data for October and November. The most reported employment number is always the unemployment rate, in December it rose from 3.7% to 3.9%, not due to layoffs but due to more people entering the job market seeking work.


This is very positive data, but the most important data in the report was that average hourly earnings for workers increased 0.4% for the month and year over year the increase was 3.2% in wages, matching the post-recession high of earlier this year. With wages growing over 3% and inflation growing right around 2% workers have more residual income to either spend on goods and services or put into savings, or both.


Today’s data has created confusion amongst the “experts” as to the short and long-term future for rates and the economy. Will the increase in hiring and wages spur economic growth? Will it push back, or push off, an expected recession in late 2019 to early 2020 or not at all? Will the job markets create inflation that will cause the Fed to react with more rate increases? Or is the labor market surge, a final movement before international markets seep into domestic markets causing economic slowing to accelerate to the point that the economy shrinks into recession? The economic data the past several months has been inconsistent with the employment showing growing strength while growth has been losing strength.


What does it all mean for interest rates? The hundred-billion-dollar question, literally. Quick recap: good economic news means higher interest rates; bad economic news means lower interest rates. What we see from our economic data is a combination. Good news: more workers working earning more income allowing them to spend more and sustain economic growth. Bad, or less than good, news: Economic growth has been slowing, international markets are slowing and in turmoil due to the ongoing tensions due to tariffs and negotiations between major trade partners, home sales slowing down nationwide. Rates have been dropping consistently for six weeks and are well down from their seven-year high in October. Last month the Fed indicated instead of three rate hikes in 2019 it would probably initiate two rates hikes, and the common wisdom has become that the Fed may not raise rates at all in 2019. What it means for rates in the short-term is likely continued volatility in equity markets, i.e. stock markets, which typically results in investors putting their money in the “safe havens” of fixed rate assets, such as bonds and mortgages. More money invested in fixed rate assets leads to lower returns on those assets, in other words lower rates, or lack of rising rates.


Rates for Friday January 4, 2019: Interest rates and stock markets continue their intra- and inter-day surges and falls, with the trend being lower rates through the volatility. Should there be resolution to the tariff/trade disputes, an agreement to open the closed portions of the federal government and positive news for the 4th quarter GDP the turmoil will subside and rates will rebound higher. If the confusion continues and the GDP news shows continued decline in growth rates will stabilize at current or lower levels. Take advantage of the current rate market while you are able to do so. Rates are down again this Friday from last.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.125%      Down 0.125%

30 year high-balance conforming                     4.25%        Down 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


The Smith family is on its annual post-Christmas/pre-back-to-school trip to a desert, this year returning to our favorite p-C/p-b-t-s location of Scottsdale, Arizona where the temperatures have been very cool, the skies clear and the relaxing fantastic.


We return to our familial abode tomorrow and back to mostly normal schedules on Monday (exception being our college freshman who is wondering what to do for the two more weeks before she returns).


Looking forward to a wonderful 2019 and helping you, your family, friends, neighbors and co-workers with your mortgage needs!


Have a great week,


Dennis


Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/my-blog

12-7-18: I have tax liens; will that prevent me from purchasing a new home?

Question of the week:  I have tax liens; will that prevent me from purchasing a new home?


Answer:  Liz is an attorney and specializes in negotiating settlements with federal and state tax authorities, and a friend of mine. We were having a few weeks ago and this question came up as we often have clients that have state and/or federal tax liens and it was great to get some input on some options for tax liens.


Before we answer the question of whether tax liens will prevent you from obtaining a mortgage to purchase a new home, let’s answer the question: What is a tax lien?


A lien is the right to keep possession of someone’s property until a debt or obligation is paid. In the case of the government it is the right to take possession of someone’s property until a tax debt is paid—i.e. a tax lien.


If you have unpaid taxes and a lien has been filed against you the guidelines for all loans are that until the obligation is paid a loan will not be funded and closed.


Example: You are purchasing a new home for $575,000 and applying for a mortgage of $517,500 and are qualified to obtain loan approval. You have a lien for unpaid state taxes of $5000 from 2014 that is recorded in the county where you lived when the lien was filed. We submit your loan and the underwriter approves the application with a condition that we must show proof that the state tax lien from 2014 is satisfied and show evidence of where the funds for satisfying lien came from before the loan will be able to close. In many instances we coordinate satisfying the lien with the title company so you can pay the amount owed, initial amount plus penalties and interest, as part of the total funds needed for closing. Title will then guarantee to the lender, and you, the lien is paid and record the deeds needed for closing.


There are some instances with FHA mortgages where if you have established a payment plan to satisfy a lien recorded against you and are making payments on a constant and consistent basis. These situations are approved on a case-by-case basis, so if you are in such a situation do not assume you are automatically able to be approved. Before you write an offer and open escrow we would want to run your situation and any evidence through an underwriter for an opinion as to whether the lender would approve the loan with your payment agreement.


For unpaid taxes, or other debts, to become liens or judgments the obligation has to be outstanding for a fairly significant period of time. If you are aware of an unpaid obligation, especially taxes, it is strongly recommended you contact the public agency to which the obligation is owed and establish the amount owed and if necessary a payment plan. Many tax debtors are fearful of contacting the public tax authority thinking they may attach bank accounts or employment income to repay the back taxes due. This is not the case, these measures happen if a lien is filed and there has been no communication from you for a long period of time. Generally, for most private citizens for what the tax authorities would consider small amounts owed, the agency is willing to wait until you are forced to pay the tax obligation because you are purchasing a home or some other event.


Should you have an outstanding tax obligation it is strongly recommended you contact the agency to which the taxes are owed and negotiate a settlement amount and if you are unable to pay the full amount do at that time to set up a payment plan to pay off the taxes and retire the debt. In almost all cases, if you set up a payment plan and make the payments on time for the amount owed the agency will not file a lien against you. Depending on the loan type for which you are applying some lenders will approve and fund a loan if you show you are making consistent and timely payments on your obligation—counting the monthly payment amount as part of qualifying.


If you are having your pay garnished to collect a judgment or other obligation the garnishment is not considered a payment plan since it was not voluntary. Before a mortgage can be approved and funded the total obligation must be paid and the garnishment removed.


Prior to this year when running credit reports public records would show on the report that would impact whether we would be able to obtain loan approval, or what steps we would need to take to obtain loan approval: Federal and state income tax liens, county property tax liens, judgments from lawsuits or court cases, unpaid child or spousal support and bankruptcy being the most common. Beginning earlier this year these types of public records were no longer reported on credit reports, with some exceptions if a case somehow fell through the cracks.


Because a lien or judgment is not on your credit report does not mean we will not find out about it. As part of the mortgage process we obtain title insurance, part of the title insurance process is your completing a Statement of Information that includes name, addresses and employment for the past ten years, spouse(s), etc. The title companies runs this information through their data bases to determine if there are any public records filed in your name and notify us if that are any.


When there is a public record filed it needs to be addressed before we can obtain final loan approval and fund your mortgage. Because this is now the only way any public records will be discovered it is highly recommend you inform us at the beginning of the transaction if you have any public records for taxes, support payments, bankruptcy etc so we can begin working on the issue at the beginning of the transaction instead of waiting to find out from title closer to our scheduled closing date.


We have had transactions that have fell apart because borrowers delayed in completing their Statement of Information until close to closing, a lien popped up with title and we were unable to solve the issue in a timely fashion to satisfy the seller.


If you know, or suspect, there may be a lien let us know up front, complete a Statement of Information right away for title to run it through databases and if there is something filed we will have to ability to determine our best options and proceed accordingly.


Ignoring tax or other public record obligations thinking they will go away is not a long term success strategy. We have helped many families over the years with serious debt delinquency get their debt paid and in a position to purchase a home. The longer you wait to begin the process of satisfying the debt and clearing your public record the longer before you are free and clear. Start the process today, you will have a tremendous mental weight lifted just by beginning the process.


As always, if you or someone you know has public records and feel they will prevent obtaining a mortgage please contact me to discuss your situation and potential solutions we can begin to work on so you can become a homeowner.


Have a question? Ask me!


Higher loan limits for 2019 were announced by the Federal Housing Finance Agency. Starting for loans funded after January 1st, 2019 the conforming loan limit for single family residences (including condos) will increase from $453,100 to $484,250; for “high-balance” areas (LA and Orange Counties for example) the limits for Fannie and Freddie mortgages increase from $679,650 to $726,525. Will the loan limit increases have a dramatic impact on the housing markets? Not so much, at any given time the rate difference between the conforming loan amount and the high-balance amount is from one-eighth to one-quarter of one percent (0.125% or 0.25%). There will be some advantage to those borrowing more than the prior limit and at or below the new limit for high-balance as qualifying for the high-balance mortgage is generally easier than for “jumbo” or non-conforming mortgages.


November employment report contains no news that impacts rates. First Fridays are a big event for economic data geeks such as myself and investors as the Department of Labor releases job reports for the prior month. Today’s reports are nothing too exciting. The economy created 155,000 new jobs last month, significantly less than the 237,000 in October and below the expectations of most investors; however the total jobs added is not insignificant and still reflect a healthy employment market. Enough jobs were added to keep the unemployment rate at a near 50 year low at 3.7%. Wages continue to grow, up 3.1% over the past year—a factor in whether the Fed will increase rates later this month.


Rates for Friday December 7, 2018: Last week’s WR&MU mentioned that Presidents Trump and Xi were meeting at the G20 summit to discuss the tariff disputes. Following the meeting they announced a 90 day moratorium on new tariffs and agreed to negotiate the recent tariffs enacted by both countries. The news was well met by investors and stocks and bonds improved. As the week has progressed many have noticed the decline in stock markets, due in large part to continued uncertainty as to the trade war truce. Rates have benefited from this  uncertainty as the funds pulled out of stocks have flowed into long-term fixed assets, i.e. mortgages. As a result rates drop for the second Friday in a row and are at their lowest in three months.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.50%      Down 0.125%

30 year high-balance conforming                   4.75%     Down 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


For the past year I have been listening to an incredibly detailed podcast about World War II. To give you an idea how detailed, the podcaster began the podcast in December 2011, this past week he finally got to Pearl Harbor—seven years to cover three to four years. As a history buff I love the detail, he spends about ten episodes just on Churchill, but now that I am caught up I will have to wait a week or more (he is great at putting together information and his commentary, not so great at sticking to a schedule) before his next podcast. I anticipate his completing the war in around 2026.


I bring this up because today is the anniversary of Pearl Harbor and I feel its importance in our nation has declined over the years—not surprisingly. When the Japanese planes approached Oahu and began their bombing and strafing many on the island, civilian and military, thought the planes were part of a drill—even as bombs exploded many thought there must have been some mistake made. Once reality hit the general attitude went from disbelief to anger very quickly. Sentiments quickly echoed across the country as the news was broadcast that Sunday.


In Gilmore, Iowa seventy-seven years ago a boy named Don had turned twelve that morning, and the radio told his parents and the community what had occurred in far off Hawaii earlier that day. I asked Don several years ago what was his memory of that birthday and Pearl Harbor. His response was, “I didn’t get a chance to ride the pony.” They lived on the farm and he had eleven brothers and sisters and before it was his turn to ride the family pony they were all called into the house.


Happy 89th birthday to Don McCormick, my father in-law.


On a final note, thank you to everyone who bore with my very long WR&MU last week and those who replied with positive comments!


Have a great week,


Dennis


Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com/My-Blog

11-30-18: What will be the cost of waiting, or is there one, to purchase your new home in mid to late 2019, or 2020, instead of now or the near future?

Question of the week:  What will be the cost of waiting, or is there one, to purchase your new home in mid to late 2019, or 2020, instead of now or the near future?


 Answer:  This installment of the Weekly Rate & Market update is a follow up to the WR&MU of November 16th when the question of the week was “What was the cost of waiting?”


I got very carried away writing the update this week and to follow is a lot of detailed economic information. My conclusion shown at the end is that there is little cost to waiting, but likely not a lot of benefit, if you can afford to purchase where you want to purchase today. If you are waiting for prices to drop significantly so you can afford to purchase in area you could afford a few years ago but cannot today, then your cost of waiting is the cost of homes in areas you can afford likely going up as will the home you currently cannot afford—essentially to see a decline in values of 15-20% is not very likely so you should change your expectations and neighborhoods to where you can buy. For those interested in my more detailed observations, bless you and read on!


The answer to this week’s question is speculation on my part based on several economic factors, trends and some educated guessing. Regarding the educated guessing part, I have degree in economics and political studies and have been a student of both for over 35 years. (Two famous jokes about economics at the end of the update for those interested. They were funny when I was in college, not sure they still are…)


To answer the question of the week, I am going to flip the standard format of the WR&MU by presenting economic news this week and how it relates to interest rates, then extrapolate out to what I see for 2019.


As you read the following keep in mind that there is upward pressure on rates when economies are doing well and there is inflation, there is downward pressure when economies are sluggish, slow growth or recession, and if there are extremely negative events such as threats of war, war, or economic collapse in other nations.


While economic data is usually the primary driver for interest rates, politics also has an influence. This weekend a political event will occur that could/should impact not only rates but our economy for the near and possibly long-term future. President Trump will be in Buenos Aires for the G20 summit and has a meeting scheduled with Chinese President Xi Jinping for the purpose of discussing the tariff war between the two largest economies in the world—by three to four-fold over the next nearest.


If the meeting goes poorly and there no movement to lower tariffs, or either or both sides are so upset they raise more tariffs, we will see higher rates due to higher inflation. With tariffs increasing prices of Chinese goods imported into the United States those goods will need to either be manufactured in the United States or imported from other nations. Either scenario will increase the prices of the goods, for those manufactured in the U.S. companies will need to hire workers in an economy that is at or near full employment, which will require higher wages, as well as purchase materials required to manufacture the increased supply of goods they will need to sell. Higher prices lead to higher rates.


The meeting will be considered “good” if there are mutual statements of starting talks to find common ground on the issues that led to the tariffs, mainly market dumping, counterfeiting of American brands and piracy of intellectual property. Any indication that both sides are looking to de-escalate will likely lead to lower rates as the expectation will be a relief on inflationary pressures and avoidance of further conflict.


This critical meeting between Trump and Xi can have a significant impact on our housing markets due to their potential impact on mortgage rates.


Another non-data event this week has had an impact on mortgage rates. Federal Reserve Chair Jerome Powell gave a speech to the Economic Club of New York. In the speech, he said that he believes rates are “near neutral,” and that prior business cycles have ended not due to inflation but rather because of asset prices. Regarding “near neutral,” this comment had investors buying bonds, and mortgages, putting downward pressure on rates as they read the comment to mean that the Fed may not increase rates four times between now and the end of 2019. Instead of the Fed rate increasing one percent over the next thirteen months, perhaps only three-quarters of a percent, or one-half of a percent. The comment about asset prices ending cycles instead of inflation brings forth another interpretation is that the Fed may shift from using inflation as their primary basis for rate increases and somehow may be looking at over all prices in different markets such as stocks and housing. If these interpretations are correct, and the Fed does strongly signal fewer rate increases in the near future the impact can be a sparking sales in the housing markets as rates remain near current levels or perhaps dip in the coming months/year.


Real and potential statements are not the only news impacting rates, and therefore housing markets, this week. We also had some real data, starting with consumer confidence for November. Consumer confidence impacts rates as consumer spending is 65-70% of our economy, happy and confident consumers are expected to spend more, leading to economic growth, leading to inflationary pressures, which lead to higher rates. The consumer confidence index dropped in November for the first time in five months, however the decline is not overly surprising since the October index was the highest in 18 years. The primary factor in the November decline was primarily due to feelings by respondents that they would see little to no income growth in 2019.


Speaking of consumers, this week we receive data on their spending and income in October. Consumer spending in October saw a big increase, 0.6%, from September, a good sign for retailers heading into the Christmas shopping season and a good sign for the Gross Domestic Product growth number for the 4th quarter, and for the year. Strong GDP growth is a strong indicator of inflation, which, as we have said repeatedly, leads to higher rates. Consumers increased spending in October, and earned more as incomes rose 0.5% from September, the highest monthly increase since January. Stronger earnings are also inflationary as they a) provide more money in households for spending and b) increase costs for employers who must raise their prices to accommodate the higher costs.


Released the same day as the reports on income and spending was the rate of inflation as calculated using the “PCE gauge,” which is the Federal Reserve’s preferred inflation index (it excludes food and energy and thus is labelled the “core inflation rate”). Despite higher spending and incomes, the annualized rate of inflation for October was 2%, right around the Fed’s target rate of inflation. The news is interest rate friendly and supports the Fed Chair’s statement about rates being “near neutral.”


Before we answer the question about if there will be a continued cost to waiting to purchase a new home we must look at the most recent housing data for our Southern California markets. The quick synopsis is that local markets are in a period of transition according to data from the California Association of Realtors.  State wide the median price in October for single family homes was down 1.2% from September, but up 4.7% from last October at $572,000. More locally, in LA and Orange Counties the median movement month to month and year to year somewhat mirror the activity statewide. The median price in LA County in October was $614,500, 3.2% lower than September and 5.9% higher than 2017; Orange County saw the median price from September drop 1.8% to $810,000 but was still 3.1% higher than in 2017.


Total sales volume, i.e. units sold, were up statewide month over month, 3.8%, and down 7.9% year over year. Like with prices, units sold locally were also up monthly and down annually. In LA County, there was surge in sales in October, climbing 29% from September, however the total sales volume for the month was down 5.9% from last year. In Orange County, sales also increased from September but a much more modest 3.9%, and also decreased from 2017 with a drop of 11.3%.


Month to month the trend is more sales at lower prices, plus increasing inventory on the market and longer periods of homes on the market before being sold. One other pattern is a growth in the number of cancelled or expired listings that are not renewed.


Back to our question, what does all this mean about housing markets and if there will be a cost to waiting to purchase a new home.


The data is somewhat murky for both the economy and the housing markets—murky usually means transition. Is the transition in the benefit of those looking to purchase homes? If there is a buyer’s market, how much of benefit will there be and for long?


The economic transition seems to point to a recession late in 2019, which means the slow down starts in early to mid-2019. This is not an uncommon thesis, as others reading the economic data are also indicating a stronger probability for a recession in the next twelve months. If this occurs the biggest question will be the depth and length. In my opinion, the depth will be fairly shallow and the length fairly short. Keep in mind a recession is defined as two consecutive quarters of negative economic growth, that would cover six months or more.


If there is a recession the impact on housing markets would depend on the cause of the recession, is it a decline in asset values as Fed Chair Powell stated? Is it inflation? The cause will be a primary factor in impact on housing markets.


If the cause is primarily driven by asset prices being too high, then as prices decline, or remain somewhat stable with incomes and other prices increasing, then rates will be dropping into and during any price corrections or stabilization making homes more affordable than they are today.


If the cause is primarily driven by inflation then even if housing prices drop the affordability will not necessarily increase as rates will be increasing to slow inflation. We can see an economy with rising energy, food, clothing, houseware costs but dropping, or stable, costs for large ticket items such as housing and automobiles. If this is the case rates will be climbing resulting in the month costs of housing, i.e. mortgage rates, climbing. If this is the case then the length and depth of a housing correction will likely be longer and perhaps a bit deeper than if there is an asset based cause for a correction.


When looking at housing markets we must acknowledge the uniqueness of California as a whole and Southern California in particular. Besides the weather, which will always be a draw, the lack of available land to build more homes in the any county that touches the ocean is a huge factor. Yes, there are some areas still in the region for new homes to be built, however overall the vast majority is fully developed. In many areas, new housing is going vertical with high rises and not horizontal with single family residences with yards. This inability to add significant supply will sustain a certain level for housing markets locally.


What about the housing crash ten years ago, space availability was not much different, so why did home prices drop so much? Great question to look at. The foundation for the market was built largely on panic buying and people more concerned with making money on a property purchase instead of a buying a family home. Homes were purchased with no verification of income, funds to purchase and in many cases no hard appraisals. Mortgage products were available that enable buyers to purchase way beyond their capabilities, and as prices rose many were looking to sell their homes quickly for a profit and buy their next home. When prices started to drop many found themselves in homes with loan balances higher than property values due to no down payment purchases, rather than pay it many walked away and foreclosures rose putting more downward pressure on the market. Eventually prices did stabilize as buyers who had been priced out of the market were able to purchase due to lower prices and rates.


Finally, the market collapse a decade ago was not a result of a recession caused by inflation, or high interest rates, but rather because of poor lending standards and mortgage products that created an unnatural inflation in housing prices. When investors started looking into the mortgages being sold on the market that were based on little to no verification of ability to repay on homes that had climbed in value at unheard of rates, they stopped buying those mortgages. The result was a domino effect that pulled the nation, and the globe, into recession.


One very large impact that compounded the decline in values was the lack of qualified buyers to purchase homes as they hit the market—lower demand with higher supply continued the price declines. Many families that might have qualified to purchase a new home were prevented from doing so for several years because of the foreclosure or short-sale on their credit records. This group was a significant number that otherwise would have absorbed inventory on the market.


Since 2010 buyers of homes have overwhelmingly been purchasing homes in which to raise families and not to make money. They have been qualified for their mortgages by proving income and funds for purchasing. Most buyers have been putting more than the minimum required down payment, so they have “skin in the game” and will be less likely to walk away or panic sell if/when market prices dip.


The run up in real estate values over the past several years was created by qualified buyers competing with other qualified buyers to purchase homes. The mixed market we now see, with housing values starting to decline, sales down one month and up the next, is based on affordability due to the price increases exacerbated by the increase in rates since the start of the year. The pool of buyers has not shrunk, and will not shrink because of any market transition, what has changed is the price for which they can qualify and/or their desire to purchase in a market they see as transitioning so they are waiting for prices and rates to drop.


All of this said, and I apologize for my long-winded path to this point but I wanted to be somewhat thorough, I do not feel there is a large cost to waiting, but I also do not feel there is a large benefit to be gained by waiting to purchase a new home.


Many sellers, or would be sellers, are holding properties off the market as they desire a higher price for their home than the market will support. For the past few years new listings have come on the market at the highest price in the neighborhood, or just beyond, and buyers have been over-bidding the list price to obtain the home. More recently homes are selling at or just below list prices, causing potential seller to hold off until prices increase again.


Note, “again.” Because of the lack of ability to build more housing near the coasts (let’s define “near” 25 to 30 miles from the ocean from San Diego to Santa Monica) there is limited ability to expand supply, any increase in demand will push up housing prices. Natural attrition is due to death, divorce, and relocation will dictate supply, population growth and aging as more people enter the age of homeownership will dictate demand. Demand will not be able to be sated with new housing, hence existing housing will be what is available for buyers to bid on. Over time Southern California coastal residential housing goes up. How soon and how much changes depending on what time frame, over longer periods of time  however prices climb.


Looking into 2019 housing prices will dip in some areas, drop in others and stay somewhat constant in other areas. Rates should remain near current levels, possibly declining towards the middle to end of year if/when economy slows down, but since they are already so low (historically discounting the false rates created by the government and Fed starting in 2008) there will not be a significant drop as we saw following the last recession. What I do see happening is families slowly moving their geographical areas of desirability to neighborhoods they can afford. The home they can purchase to purchase for $500,000 is no longer available in the neighborhood they were hoping to purchase in one, two or three years ago; that $500,000 home is now selling for $550,000 to $600,000. Where homes were selling for perhaps $425,000 – $450,000 two or three years ago are likely the $500,000 homes today. The decision will be, do we buy a home in an area we did not want to purchase in before or do we wait and hope real estate prices drop 15-20% to $500,000 to buy where we initially wanted to, or do we continue to rent with rents still increasing?


I believe the cost of waiting will be that if you stick to your desired area to purchase and hope for prices to decline significantly you will continue to rent until some major change in your financial situation to purchase a home in that area. The cost of waiting into the future will be lost opportunity in neighborhoods of lesser value that you can afford as families start to purchase in those areas, slowly increase their values and changing the neighborhoods with higher ownership density.


If you are able to purchase a home in your desired area, I do not see any significant cost in waiting, but not a lot of benefit to waiting either. Yes, prices may dip some more into the new year, yes rates may dip some more into the new year; however when will you know that the dips have stopped? When will you know that the time is perfect to purchase with rates and prices, and what will be on the market at that time?


My advice has always been, when buying a home, if you like and can afford it buy it. You will be there for a long time, any changes in price over the early years of ownership will be more than made up for in the long run due to where you are buying—California. Your ultimate cost of waiting may be hoping the house you really like still being on the market when you feel the price is right.


Sellers on the market now want to sell, make an offer!


Disclaimer on this very long-winded update:


The WR&MU on October 21, 2016 had a total miss on my part for predicting economic recession, in fact the exact opposite happened as I did not put a lot of thought into Trump winning the election and the resulting economic growth. That will provide a filter for any predictions I make, as well as others—it is all an educated guess and different guesses result on how each guesser is trained to read the tea leaves.


Have a question? Ask me!


Rates for Friday November 30, 2018: The comments by Fed Chairman Powell resulted in a nice rally for bonds and as a result the 30 year conforming rate is lower than the previous Friday for the first time in five weeks. Will it hold? Per comments above a lot depends on the meeting between Presidents Trump and Xi this weekend.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                               4.625%       Down 0.125%

30 year high-balance conforming                       4.875%      Down 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


We have three seasons in Southern California that cycle annually: Dry, Fire, Mud. When it is dry we have more fires, when it rains we get mud in many areas but especially the fire zones and the rain creates more undergrowth that gets very dry leading into the next fire season causing more and bigger fires that are then turned to mud slides….yet our state and local governments continue to allow more and more housing to be rebuilt where there are histories of fires, floods and mudslides. See Einstein’s definition of insanity.


Since it has been quite a while since we have had a drenching like yesterday, I hope your roofs, windows and other parts of your homes held tight. While we have had no water penetration the same cannot be said of the other scourge for most of the region: ants finding ways into our homes as their colonies get flooded out. The battle is on! We seem to have won the first one but know there are more to come. All that said, I don’t mind the ants a few times a year as opposed to snakes or very large arachnoids!


Enjoy the official start of the holiday season as parades and other activities begin!


Have a great week,


Dennis


Economic Jokes:


Every question asked of any economist has the same answer, resulting in no definitive answer: “On the one hand blah blah blah; one the other hand blaw, blaw, blaw.”


A company is looking to hire an analyst. There are three finalists, a physicist, a mathematician and an economist.


The physicist walks into the interview and on the white board is a question; What is the answer and why: (12-4)3 + (4(13/4)+7) – 21 = ?


After explaining his process as he is writing down several equations using vectors, calculus, etc he writes down 23, circles it and puts down the marker and stares at the interviewer. The interviewer says, “Thank you, please erase your work and send in the mathematician.”


The mathematician enters, sees the equations and mumbles to herself as she solves the problem using basic math, circles the answer of 23. She caps the marker, looks at the interviewer and says, “It is basic math and the answer is 23.”


The interviewer says, “Thank you, please erase your work and send in the economist.”


The economist walks into the room and sees the question and reads aloud, “What is the answer and why.  This is a job for an analyst position correct?”


“Yes.”


“Are you the one I will be reporting to?”


“Yes.”


“Are you the one giving me the information to analyze and I presume it will then be passed along to your superiors?”


“Yes.”


The economist looks around the room. Walks to the door and locks it. Pulls a chair up very close to the interviewer, leans in and whispers, “What is the answer and why….what do you want the answer to be?”


The economist got the job.


Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com

11-23-18: What are the options for those who lost homes, or had them severally damaged, in the California wildfires?

Last week I ended the question of the week section (what was the cost of waiting) stating I would answer the natural follow-up question, what will be the cost of waiting, or is there one, for families waiting to purchase until later in 2019 or even 2020. Because of the wildfires in California that have destroyed thousands of homes I have chosen to address a very critical issue for those homeowners, knowing that we have clients, families, friends who are either directly impacted, or have family and /or friends who are impacted with lost or severely damaged homes. Next week I will look at what I feel may be the cost of waiting to purchase a new home.


Question of the week:  What are the options for those who lost homes, or had them severally damaged, in the California wildfires?


 Answer:  Earlies this week I was speaking with a friend whose son and daughter in-law lost their home in Paradise, California in the Camp fire. In our conversation, I went through several different options his son and daughter in-law should consider regarding their family’s future.


The very first thing that should happen is the affected family needs to contact the lender and home insurer and let them know that your home was lost in the fire. You need to ask the lender for payment abatement or suspension while you work your options and ability to make payment. Chances are high many people in the affected areas that lost their homes have also lost the ability to generate income depending on whether their place of employment was lost to the fire, their ability to get to work or other factors. Stay in communication with the lender regarding the monthly payments. Ask if the call is being recorded and if so how you can refer to it later if needed. Keep records of every phone conversation, who you spoke to, what time, what was the conversation about, did the lender make any statements to you regarding the issue. Always request an email from the lender summarizing the conversation and confirming what may have been agreed to, if no email received call back quickly and repeatedly until you do receive the written communication.


With property tax payments due by December 10th a similar conversation should be had with the local county assessor. If the lender has been collecting tax payments confirm with the lender if they will be paying the taxes—at this point they probably already have.


Once the mortgage payment has been figured out time to move onto your insurance company.


Since you have a mortgage your home was insured. The first question you need answered is, how much will our insurance cover? The required coverage for lenders is either the entire loan amount owed, or the replacement cost of the dwelling.


The location of your home, the cost of construction in the area, and the cost of the home will determine whether your insurance policy will cover the cost to rebuild your home or your loan amount; for most developed properties in California the policy will cover replacement costs and not the loan amount. Because dirt is expensive in California the price is impacted, but because dirt does not burn it is not required to be insured.


The lender requirement of replacement cost will be determined by the appraisal which contains on a section where the appraiser calculates “replacement cost new.” This is the amount that must be covered by an insurance policy. For instance, I have a client who is refinancing a mortgage for $550,000 for a property appraised at $800,000; the replacement cost for the structure is $245,000, this is the amount of coverage we must show on the policy to close the transaction.


In Paradise the numbers are smaller, but the policy is generally the same. If the market value of the property is $250,000 the cost to replace may be $145,000 and the outstanding mortgage balance around $200,000.


This difference between mortgage amount and policy coverage is very important to those whose homes have been destroyed or severely damaged when considering, what do we do now?


It is important to note that the lender is a “loss payee” on the homeowner’s policy, meaning that any insurance check is made payable to the homeowner and the lender, both must agree what to do with the money before both parties endorse the payment.


Let’s take the case above, property value before the fire was about $250,000 with an outstanding balance of $200,000 and the insurance policy covers rebuilding the home for $145,000.


The first option is to work with the lender and insurance company to determine the mechanics of what happens if you choose to rebuild your home. Does your policy cover either mortgage payments until you can move back into your rebuilt home? Does it cover housing costs if you need to rent? What is the process regarding contractors, is than approved list you must use, or if you choose a contractor is approval required? How much time do you have to rebuild your home?


Before deciding to rebuild there are several factors to consider. Because there are thousands of homes in the region that have to be rebuilt, what will the actual cost to rebuild be given a limited supply of contractors versus the large demand for their services. What about the cost of building materials? How long will it take before a contractor will be able to take on your rebuilding job? What about designs, engineering, permits? Will there be a building moratorium for political purposes as state, county and local authorities determine if building requirements will be changed that impact costs of construction?


If all those questions are answered to your satisfaction next consider the future of the town and region. What if only one in two, one in five, one in ten, homeowners decide to rebuild? What will be the value of your home? Will it be significantly less than the loan amount? What will the neighborhood and town be like? What about schools and stores? The town will be significantly different, but how and will it be a  place where you and your family will want to live?


Once you have this information then you ask the question, what if we decide not to rebuild our home? The answer is that you will likely need to assign the amount covered by the policy over to the lender who will apply it to your mortgage balance. Since the amount of the insurance pay-out is less than the mortgage balance you will still have, in this case, about $55,000. What next? You can ask the mortgage to be recast, meaning if you still have about 25 years left on the loan the lender will amortize the $55,000 for 25 years at your current rate to determine your new payment. If your rate is 4.00% the payment would be $290 per month. You can have the county re-assess your property to lower your tax liability and determine the minimum insurance cost required by the lender.


Once you have the cost to retain what will be a vacant parcel of land you can decide if you want to retain the property for any future development. Or if you want to contact the lender and inform them you have no intention of keeping the property and would like to deed the property to the lender. This will result in a foreclosure on your credit record, which will impact your ability to obtain a traditional mortgage for several years, but you will not be making payments on a property that may or may not be of significant value in the future.


For many families, walking away will be the best answer for their family, selecting what they see not as the best option, but the least worst option. The more people who make this decision the more negative the impact on families who decide they want to try to rebuild as property values, already negative impacted by the devastation to the town, will drop further. As well, property taxes will drop significantly negatively impacting city and county services.


Other factors impacting any decision are will there be assistance that may come from government agencies? Will it be sufficient for you to rebuild or to re-locate? Can you continue at your job and therefore need to stay in the area? What will be your cost of housing with all the other families in the area needing housing as well?


There may be other options I have not yet considered; my primary advice is to not rush into any decisions. Speak to different people you trust and have no stake in the outcome of whatever decision you make. A very big challenge will be to make your decision with as little emotion as possible.  Consider the possible long-term consequences of any decisions you make. Decisions should be made on what likely can happen, not necessarily what you would like to happen. Consider the impact of the decisions your neighbors and others in your town may be making and how those decisions will impact you.


Finally, be selfish. Your decisions need to be what is best for you and your family. No one else is going to make your housing payment, you will be the ones residing in wherever you choose to make your home, either where it was before or in a new location. Your financial future is going to be impacted, which will in turn impact the quality of life for your family for year to come so be as clinical as you can through the process.


CAUTIONARY NOTE Unfortunately disasters bring out scam artists and thieves. People posing as contractors with real or fake credentials will be contacting families to collect deposits to build homes and never be seen again. Real, or fake, attorneys or others will be offering consulting services and collect fees without providing any services. Be very careful before signing any contracts, or entering into agreements. Double, triple check backgrounds and services provided. Affected families will be looking for any good news and charlatans tend to be excellent actors able to prey on those in a weakened state. Be careful.


If I can be of any help with questions or what-ifs please do not hesitate to contact me.


To help the Red Cross help those in need click here: Red Cross Donations


Have a question? Ask me!


Rates for Friday November 23, 2018:  A slow week this week with the Thanksgiving holiday with little news impacting rates. A bit of softening in rates from last Friday but not enough for any change week over week. Rates are a bit steady and this should continue next week as well depending on how well the U.S. Treasury auctions go next week as the government sells over $110 billion in bonds. If the auctions go well rates should remain steady, if they do not go well rates will bump up a bit.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                               4.75%       Flat

30 year high-balance conforming                       5.00%      Flat


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.

We were without our oldest for the first time ever on Thanksgiving, she made the bus ride from Boston to Portland, Maine to spend a few days with family friends. Yesterday morning the temperature difference with wind chill was about 65 degrees, glad she has winter clothes. Absence makes the heart grow fonder and we missed her presence and my apple pie did not turn out well as hers do.


With friends and family at our table we had a wonderful day and evening and I hope you did as well.


Have a great week,


Dennis


Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com
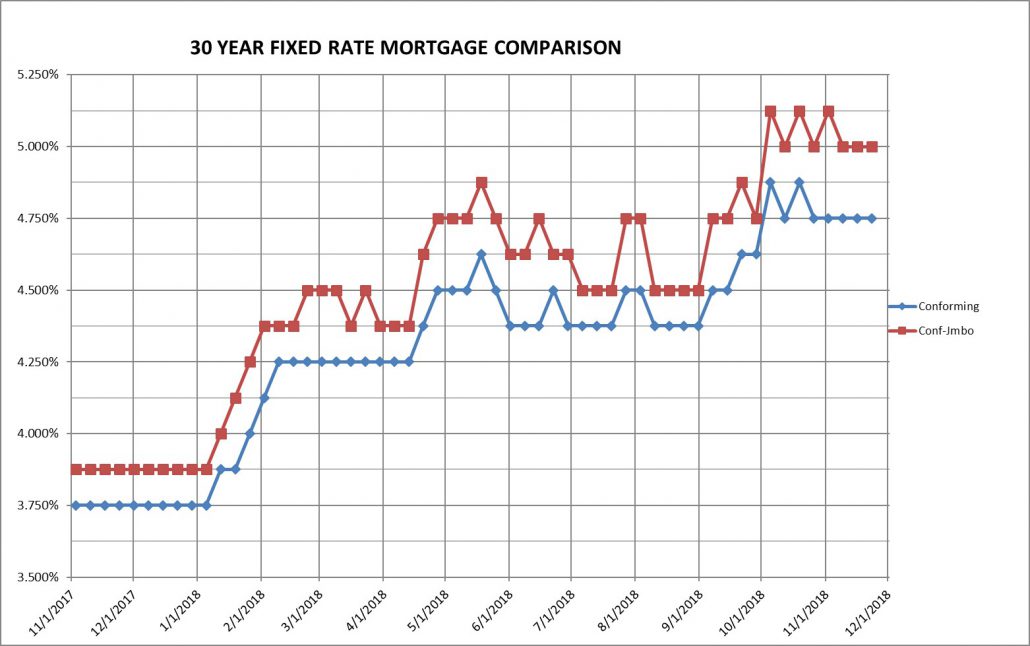
11-16-18 What was the cost of waiting?

Question of the week:  What was the cost of waiting?


 Answer:  Over the past few years we had a lot of clients who were waiting to buy a new home because they felt the market would correct at some point and they could purchase the home they wanted for less money. About once a year for the past few years our question of the week has been, “what is the cost of waiting.”


On March 2, 2018, this was the question of the week and in my answer the worst case scenario I presented, with highest cost increase and highest interest rate, has come to pass.


Instead of creating my own sales prices for the answer to this week’s question, I will use the median home price for Los Angeles County as published by the California Association of Realtors.


What was the cost of waiting to purchase a home from September 2017 to September 2018?


In September 2017, the median priced home in the county was $606,110, in September 2018 the median price rose to $634,680, and increase of 4.7%. During this same time the interest rate for a 30 year fixed rate loan for borrower with a 740 FICO score rose from 3.75% to 4.75% for the loan amounts needed to purchase the median priced home with 20% down.


With the prices and rates climbing it follows that the mortgage payment also increases. With the 20% down payment on the median price the loan amount in September 2017 was $484,890, in 2018 the loan amount rose to $507,940. As a result, the monthly payment for the median home in 2017 was $2245, this year that payment is $2650 per month, an increase of $405 per month, or about 18%.


Long-time readers of the WR&MU know the mortgage industry used debt-to-income (DTI) ratios to qualify income for mortgage applicants. The DTI is calculated by adding up the applied for housing payment (mortgage principal and interest, property taxes, homeowner’s insurance, homeowners’ association if applicable, aka PITI) plus credit obligations (credit cards, auto and student loans, alimony and parental support payments, etc). Once the obligations are added together that number is divided by your gross income and the result is your debt-to-income ratio. Example: your new house payment is $3000 per month, you have $1000 per month in revolving debt and car loans for a total of $4000 per month. Your salary is $10,000 per month. Divide the $4000 in obligations and house payment by your $10,000 per month salary and your DTI is 40%.


The catchall rule of thumb for most homebuyers is that the house payment, PITI, should be around 35% of your gross income. Why 35%? Because when we add in your other credit obligations we do not want to exceed 45% of your gross income for most loan programs and many households have about 10% of their income going to other debt obligations.


Using the 35% rule of thumb, how much more income did you need to qualify for the median home in September 2018 from September 2017?


Including estimates for taxes and insurance the PITI for the median home in 2017 with 20%, a 30-year fixed rate of 3.75% was $2998 per month. Divide the PITI by 35% and we see that you needed income of about $8550 per month ($102,600 per year) to qualify for the median September 2017 home.


The September 2018 median priced home in LA County, also with 20% down but with a rate of 4.75% for a 30-year fixed rate, had PITI of $3438 per month. Still using 35% as the factor for calculating qualifying income you needed income of about $9825 per month ($117,900) in September 2018 to purchase the median price home.


Summing up, the cost of waiting that past year resulting in needing about 5% more funds for down payment, a 18% increase in your mortgage payment and you would need to earn 15% more to qualify.


The last number is the most critical, in general you need to earn 15% more in 2018 than you did in 2017 to purchase the same home.


Most people are not getting 15% raises from year to year. So how do the numbers look based not on a hypothetical but a reality?


Bill is single and approaching retirement—he plans on retiring between 2023 and 2025. He pays almost $2000 per month in rent and recently came into a financial windfall of about $200,000. We first met in March of 2017 and proceeded to have several conversations regarding his ability to qualify, and more importantly what he felt comfortable paying, for a new home. Involved in the decision process were his tax preparer, financial advisor and real estate agent. The parameters were to keep Bill’s total housing payment, PITI, at $3000 per month or lower and including closing costs not to spend more than about $120,000 to purchase his new home. This put us in a price range of about $550,000 for a new home, with a 4% interest rate our limitation was on the amount of cash to close the transaction not the monthly payment.


Bill actively entered the market looking at homes and condos that fell within his cash to spend and monthly payment parameters. You may recall that rates fell from the Spring of 2017 into the Summer and Fall, which was good news for Bill as he by using his cash to close as his limiting factor the same price homes became cheaper as the monthly payments went lower with interest rates.


Unfortunately, Bill could not find the right home for him, or by the time he made the decision to write an offer on a home another buyer had already entered escrow.


Because of the market as time went on the neighborhoods in which he was looking had rising prices, so to purchase the same house he needed more and more down payment to meet the 20% down we had budgeted.


Today, even with higher rates his ceiling of $120,000 to spend still is a sales price of around $550,000, however because of the rising prices in the market the 3-bedroom homes in that price range are now 2-bedroom homes in the same neighborhood, or perhaps even a neighborhood that is the next level lower in terms of price, location, etc.


Because of his hesitation throughout 2017 and into 2018, Bill has to either change his parameters to purchase the home he wants, or change locations where the average prices are lower, which creates a challenge for his commute to work, visiting family and where he would like to live in retirement.


We are now looking at condominiums for Bill as the prices are usually lower in the same market and we can purchase something within his cash spending restrictions as well as stay within his monthly payment restriction even with the HOA dues. In the meantime his rent has increased 5% and the landlord is considering selling the property to take advantage of current real estate prices.


Waiting has cost Bill not in cash to close or monthly payment but in size of home, location of home and/or type of home he can purchase today as opposed to one year ago.


All of which leads to a follow up question: What will be the cost of waiting, or is there one, to purchase your new home in 2019, or 2020, instead of now or the near future? A question I will explore in next week’s WR&MU.


Have a question? Ask me!


Consumer prices jumped last month. The prices consumers pay for goods and services rose 0.3% in October and year over year the general inflation index climbed 2.5%, the highest it has been in the past year, according to Consume Price Index data released this week. Leading the charge upwards in prices were gas, rent and used vehicles. This data would put upward pressure on rates, however the data used to calculate inflation by the Federal Reserve is the “core” rate of inflation—which strips out volatile gas and food prices. The core rate for October came in with a 0.2% monthly increase and the annual rate dipped to 2.1% from the prior month’s rate of 2.2%. This is a bit confusing with the two different calculations, consumers are seeing a cost of living increase of 2.5% from last year, but if they didn’t buy and gas or clothes they only saw an increase of 2.1%. Because the core rate was within expectations and the Fed’s target inflation rate mortgage rates were not impacted by the news.


Consumers are the most important part of our economy. Personal spending and consumption accounts for 65-70% or our economy, because of this retail sales data is an important indicator of the economy’s strength. The retail sales data for October were released this week and included revisions to the prior two month’s data. In the revisions retail sales in August and September went from slightly positive to slightly negative, the first back-to-back negative months since 2015. For October, the data showed the biggest increase since last fall with an increase of 0.8% for the month. As with the CPI data, the spending increase was led by gasoline prices, and helped with a surge in new auto purchases. Taking out gas and car sales and the increase in retail sales drops to a much more modest 0.3%, so good news for auto dealers who saw an increase in sales, not as good news for retailers who saw their customers spend on gas and cars instead of sweaters and meals out. Overall the news is neutral for mortgage rates, the revisions downward for August and September will likely result in a revision downward for 3rd quarter GDP growth from the initial estimate of 3.5%, which is good for rates, and the increase in total sales being led by volatile gas prices and one-off new car purchases is discounted by investors.


Rates for Friday November 16, 2018:  Rates should be a bit lower today than they are, but it appears lenders are hanging on a bit to increases in the markets (higher prices equal lower rates) due to the weekend before Thanksgiving and potential volatility in the short week. Overall rates see some upward pressure easing this week due to stocks selling off and a comment from a member of the Fed board that decides rates indicating that moving forward the Fed will be very cautious—putting some question into whether there will be three rate increases as scheduled in 2019.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.75%       Flat

30 year high-balance conforming                    5.00%      Flat


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


Unfortunately, it often takes the misfortunes of others to appreciate the fortunes we have. Such is the case for most of us this week as we gather with family and friends for Thanksgiving. Coming together in gratitude for what we have in our lives as we observe the incredible upheaval thousands, tens of thousands, of families have had in our Southern California region via the media, both traditional and social.


Those impacted by the wildfires in Southern and Northern California are extremely grateful for one of America’s most important organizations, the Red Cross, who show up at every disaster with all sorts of assistance from arranging shelter, food, water, clothing, even dolls and toys for children. This comes at a cost, which is almost all from charitable donations.


Here is where the readers of the Weekly Rate & Market Update can help those who no longer have a home this Thanksgiving, or are displaced, due to the fires, by clicking this link and making a donation of any size: Red Cross Donations


We will have guests at our table from near, my father in-law, and far as two families from Chicago, Leslie’s cousins as well as a family spending their vacation week in Southern California whose daughter has gone to camp for several years with our daughters. I am anticipating some talk about the Cubs and Bears.


My family and I are very thankful for the support we have had over the decades from our clients, business and referral partners. As well the incredible family at Stratis Financial who work diligently to ensure our clients’ files processed, approved and funded with the utmost on professionalism and efficiency.


Have a wonderful Thanksgiving with family and friends wherever the holiday may take you.


With gratitude,


Dennis


Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com

10-26-18 Why can’t you use my bonus income to qualify me for my new home?

Question of the week:  Why can’t you use my bonus income to qualify me for my new home?


 Answer:  Income must be of a constant and continuing nature.


What constitutes “constant and continuing?” Generally, at least a two year history of receiving the income fulfills the requirement. There are some exceptions which I will cover below, but the question of the week specifically addresses bonus income, and much of this will apply to overtime and commission income as well.


Bonus income typically fluctuates from year to year depending on the matrix upon which the bonus is based. Because of the fluctuation there must be a guideline for the lender to consider the income for qualification purposes for your mortgage application. The industry standard is that if you have received a certain type of income for two years are more then we have reached the threshold of constancy. To reach the continuing nature policy we generally need a statement from your employer that the bonus will in all probability continue; this guideline is usually met with a letter from the employer or with a Verification of Employment (VOE) that we send your employer to complete. The VOE has sections for your employer to complete stating the length of employment, income for each of the past two years plus year to date broken down into base, bonus, overtime and commission. As well there is a place to indicate whether the continued payment of bonus, overtime and commission is likely to continue in the future.


Whether your bonus is paid annually, quarterly, monthly or per pay period does not matter for qualifying, we will convert the amount received into a monthly amount based on the amount received for the past two years, and if applicable year to date. The rule of thumb for bonus income, as well as overtime and commissions, is to use at least a two year average, unless the most recent year is lower than the prior year in which case the lower amount is taken.


Example: You have been with your company for five years and have received bonuses every quarter for the past three years and the bonus is paid on the first paycheck after the end of the quarter. In 2016 your bonuses totaled $12,000, in 2017 $12,600 and on your October 15th pay period your total bonuses year to date including September totaled $9700. The total amount received in bonuses is $34,300 over the past 33 months (two full years plus nine months in 2018), so we divide the total amount received by the time period over which it was received and get $1039.39, this is the amount of bonus income we will use for your qualifying for your mortgage—provided your employer verifies that you are likely to continue to receive bonuses in the future.


Example 2: Same employment scenario as above, however in 2016 you received $12,000 bonus, in 2017 you received $10,000 bonus and through September you have received $9000 in bonus income as reflected on your recent paycheck. It is evident you received $1000 per month in 2016 and so far in 2018. However, in 2017 your bonus was $833.33 per month—this is the bonus income that most lenders will use for income qualifying as it follows the standard guidelines from Fannie Mae and Freddie Mac. Even with a letter from your employer regarding 4th quarter bonus the lender will take the worst case scenario when calculating income.


All this covers how we do calculate and count your bonus income, back to our question, why is your bonus income not allowed? Reading through the above it is likely because of any or all of the following:


  • You have not received your bonus for at least two years
  • Your bonus has been inconsistent, i.e. you received bonus income in 2016 but not 2017
  • Your employer will acknowledge that your bonus is likely to continue, which we saw not infrequently during the recession with employers very hesitant to put in writing bonuses are guaranteed or likely to continue creating a legal document an employee may use against the employer should bonuses be canceled.


Any non-wage employment income is generally treated in a similar manner, most prevalent being overtime, commission and self-employment income.


As mentioned above there are some exceptions to the two year income rule:


New job—If you are starting a new job, depending on the circumstances, we can generally count your income with a short, or perhaps no, history of employment at the new job. Typically, showing at least thirty days of income is needed. If you are transferring from working for Dennis Sprockets to Smith Widgets and in somewhat the same type of work, we can use your new income—but not overtime or bonus unless expressly addressed and quantified in an employment contract and if you received similar amounts in your prior job. New professionals can also have “young” income used for qualifying with proof of education in the field and an employment contract. If transferring geographically and a new job with a new company we can usually use your new employment income before you start on your job with an employment contract and separate letter from a senior executive at the company.


Spousal support—If you have a divorce decree or separation agreement that is recorded that includes your receiving alimony or child support we can use that income once you can prove you have received six monthly payments in a timely fashion. Note the income must be received as one payment every six months and not six months’ worth of payments upfront. As well the agreement must indicate the income will be received for at least three years after the date of your mortgage application; for instance, if you are receiving $800 per month for each of your two children until they are 18 and your son is 16 then we will only accept $800 for qualifying for your youngest child.


Retirement income—If you receive a pension or social security income you do not need to show a two-year history. Provide your award letter stating the amount of income you are to receive and we will use the current income for social security; for a pension, we must show that the pension income will continue for at least three years.


Asset accounts—Most individuals and couples have their financial assets in a retirement account and/or taxable investment and bank accounts. Depending on several factors these accounts could be used for qualifying income. Retirement accounts can be used for income if you are taking regular withdrawals from the account. Depending on your age and the type of retirement account you may be having to take mandatory distributions on an annual basis, this can be used for income. Or if you are taking regular distributions we can use those amounts as income as well. If you have funds in non-retirement accounts there are some cases where we can perform a calculation called “asset depletion” so we can achieve qualifying income.


Rent—If you are purchasing a new home and renting out your existing home there are guidelines we can follow to use the rental income from your current residence as qualifying income to offset the mortgage, tax and insurance payments.


Bonuses, commissions, retirement, wages, there are many different sources of income; whether yours is eligible for use as qualifying income can depend on different factors. If you, or someone you know, if looking to purchase or refinance property please contact me to ensure you are fully qualified for the transaction you want to make.


Have a question? Ask me!


Don’t bury the lead. A couple of big pieces of economic news, since weekly update is primarily about mortgages and real estate we will start with the major news on home sales. This week the California Association of Realtors released its housing report for September. Based on the data I am of the opinion the real estate markets have become a buyer’s market. Los Angeles County saw the median home price increase 4.5% from August and 4.7% from 2017 to a value of $634,680. While the median price increased there was a dramatic drop in total sales. Sales volume for the month was down 18.3% from the prior month and 22% from last year. Neighboring Orange County saw both the median price and total sales volume drop in September. The county median price of $825,000 was down 1.6% for the month and 3.3% for the year, total volume was down 20.3% from August and 21.8% from September 2017. The data that supports my contention of our regional market being a buyer’s market is the increase in the number of active listings on the market and the time a home is on the market before it is sold and enters escrow. Basic premise, more supply leads to lower prices. Supply is growing and demand is not due to several factors, primarily higher interest rates.


Impacts sales and refinances. The softening market not only impacts sellers as they see values slowly erode, but also can have an impact on homeowners looking to refinance to lower payments, consolidate equity lines or obtain equity for various reasons. How? With a softer market there is more downward pressure on appraisals and therefore values needed for refinancing, or the rate and cost of the refinance due to potentially higher loan to value based on potentially lower appraised values.


The national economy is not following housing. This morning the initial estimate for the Gross Domestic Product was released and it showed growth in the quarter of 3.5%, slower than the 4.2% GDP growth in the second quarter. The expectation is that 2018 will end with total economic growth of 3% or greater, the first year with such growth since 2005. The report was, as you can expect, sprinkled with good news most notably the decline in inflation from 2% in the second quarter to 1.6% in the third quarter. That is good for consumers, but is it good for the economy? With some weakness in business spending and investment, slowing inflation and the equity markets dropping in recent weeks the signals are there for economic growth slowing, or reversing in 2019. It is quite possible, probable?, that a mild recession will begin in the third or fourth quarter of 2019. Overall the GDP news was market neutral as the growth figures met expectations.


Rates for Friday October 26, 2018: With stocks falling this week investors have been moving their funds to bonds and mortgages resulting in rates falling from last Friday. We remain in a volatile market and caution is strongly advised when thinking about floating your rate.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.75%     Down 0.125%

30 year high-balance conforming                       5.00%     Down 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


Few things are better than a short trip that feels like a very long trip. That was the experience Leslie, our daughter and I had last week when we flew out to Boston to see our college freshman. Leslie and I walked about 13 miles on Saturday, mostly up the Charles River while the internationally famous Head of the Charles rowing regatta was going on, watched a performance by the marching band, where ironically our daughter is the tallest in the flute section as she was in high school, then we all enjoyed a fantastic and leisurely lunch/dinner at an Italian restaurant, topped off with the ubiquitous visit to Mike’s for some pastries. Another long walk to LL Bean to get our girl squared away with duck boots for the coming winter and it was back to our hotel for a few hours of catching up and just being together. A packed day, with plenty of needed hugs, mostly for me, and just seeing how happy she is with her friends, college and new city and mom and dad have come home at ease.


Now we are looking forward to our next time seeing her when she is home for four weeks at Christmas!


Have a Happy Halloween and don’t get too spooked by the gremlins and goblins showing up on your doorstep…I’ve noticed they leave you alone if you bribe them with some sugary treats!


Have a great week,


Dennis


Past Weekly Rate & Market Updates can be found on my blog page at my website www.DennisCSmith.com

10-12-18: We just received our property tax bill…

Question of the week:  We just received our property tax bill…


 Answer:  Okay, okay this is not a question; it is the start of a question. There are several phrases to make it a question I will quickly go through this week:


…why is it lower than you estimated when we purchased our home earlier this year?


…why is it higher than last year since we are under Proposition 13?


…how much should we pay?


…why is it lower than you estimated when we purchased our home earlier this year?


If your property tax bill is significantly less than my estimates when we funded the loan to purchase your home then you will very likely receive a supplemental tax bill, if you have not received one already and the two bills added together, the tax bill you have just received from the County where your property is located and the supplemental tax bill, should be close to the estimate we used when you purchased your home.


In California the fiscal year is from July 1st to June 30th. The tax bill property owners have received in the past week from their County Assessor has an option of paying half the bill by December 10th covering first half taxes from July 1st to December 31st and the other half by April 10th covering the second half taxes from January 1st to June 30th. The tax bill mailed in September or October is based on the prior tax bill as adjusted for Prop 13, or if there was a transfer the value on January 1st.


When you purchase a property the tax base for the property is adjusted based on your purchase price. Depending on when you purchased the property the new value may not be adjusted by the County Assessor before the tax rolls are set for the coming fiscal year. If this is the case the tax bill you have received reflects the prior assessed value plus and adjustments for Prop 13 (see below) or additional payments for taxes or bonds put in place by voters or local government. This is the primary reason your tax bill is probably lower than you anticipated, and why you will receive, or have received, a supplemental tax bill.


The supplemental tax bill covers the difference between the taxes on the tax bill and the taxes you should be paying from the date of the close of escrow on  your property purchase to the end of the fiscal year, June 30th. Depending on the seller’s assessed value and your purchase price the supplemental bill can be very large, very small, or even “negative,” in which case you will receive a refund from the County.


Supplemental tax bills are only mailed a few times a year, so it may be some time after you closed your purchase before you receive your supplemental bill. Please note, if you have an impound account and your lender is collecting and paying your property taxes that your supplemental bill is not sent the supplemental tax bill, the payment is entirely your responsibility.


Confused? Let’s say you purchased a home for $650,000 and closed escrow on February 7th. Using our rule of thumb of your property taxes being 1.25% of the purchase price your annual taxes the first year of ownership should be $8,125 per year ($4062.50 for the first and second half tax bills). Your seller purchased the property in 2000 for $375,000 and their assessed value has risen through the years and their tax bill the year they sold the property was $5500. You just received your first property tax bill from your County Assessor and it shows you owe $5610 conveniently payable in two payments of $2805 each.


There is a difference in annual taxes between what you should be paying and what you are being billed of $2625. However this will not be the amount of your supplemental tax bill as that is the annual property tax differential and you only owned the property since February 7th, not July 1st of the prior year. There are 143 days between February 7th and June 30th, and that is the period which the higher assessed value should be applied for property taxes. Therefore your supplemental tax bill will be the annual property tax differential divided by 360 days multiplied by the number of days you owned the property between the sale date and end of the tax year:


$2625/360 = $7.29 per day x 143 days = $1042.71 as your supplemental bill.


Note that depending on your closing date you may receive more than one supplemental bill.


It can get pretty confusing, however most County Assessor websites have links where you can input your address, sales price and closing date and it will calculate your estimated supplemental tax bill.


…why is it higher than last year since we are under Proposition 13? Prop 13 was passed at the ballot box by California voters on June 6, 1978. There were three major items in the measure that immediately impacted property owners in 1978. First, it decreased assessed values by having all properties in California re-assessed to their assessed values in 1976. Second, it capped the assessed value of real property taxes by to the state at 1% of the ad valorem value of the property, i.e. the transaction value. Third, it limited increases to assessed values to an inflation index but not to exceed two percent (2.00%) per year.


It is the third factor that confuses many new or experienced property owners when they receive their property tax bill that the total is higher than what they paid the year before. Since property values are increasing your assessed value is increasing as well, but not more than two percent above the assessed value from the prior year.


Also surprised are those property owners who do not follow the news or politics. Their surprises come in the form of special assessments put on tax bills by either voters or elected officials in the form of bonds or taxes. For instance for our home in Long Beach we have nine such assessments that add 29% to our base tax rate of one-percent. Three of the assessments are local bonds for the Metro Water District, Long Beach Community College District and the Long Beach Unified School District; the other six are county measures and bonds for parks, flood control, sanitation, etcetera. Every city and county has different special assessments on their property tax bills that are added to the one-percent maximum taxable assessment from the state.


…how much should we pay?  The first question, “how much should we pay?” is a follow up to my Weekly Rate & Market Update from December 22, 2017 after the new tax law was passed that limited SALT (State And Local Tax) deductions to $10,000 per year. In the WR&MU the question was given the reduction in ability to deduct California state income tax and property taxes to a cap of $10,000, did it make sense for California property owners to pay both the first (due by December 10th) and second (due by April 10th) half taxes in 2017, which would result in most property owners who did this paying three half year tax year bills in 2017 (2nd half of 2016-17 in April 2017, 1st half of 2017-18 in December 2017 and 2nd half of 2017-18 in December 2017) thereby maximizing their property tax deductions. The advice from my CPA tax preparer friends Lew Finkelstein and Paul Scholz was, “depends” as some clients would not benefit from the additional half-year of taxes deduction if they were under the Alternative Minimum Tax (AMT) zone for 2017. For most people however it did make sense to pre-pay the April 10th payment and get the deduction.


What about this year? Before I answer here is the disclaimer: I am not a tax professional or accountant, before you make any decision as to how much you should pay in property taxes this year consult your tax preparer.


If you did pay the second half of your property taxes in 2017 instead of in April of this year, your property tax payment due by December 10th will be your first property tax payment of the year. Should you also pay the second half bill due by April 10, 2019? Again, it depends. If you pay just the first half payment, will your total of property taxes paid plus state income taxes be less than or more than $10,000? If your total is less than $10,000 you may want to go ahead and pay both first and second half property taxes in December to maximize your deduction; if your total is more than $10,000 you may want to pay the second half taxes next year in April when due—which means in 2019 you will again be over the $10,000 limit but at least you will not have a double tax payment in December when you may need the extra cash for the holidays.


Confused? Let’s say your annual tax bill is $6,000, you owe $3000 by December 10th and another $3000 by April 10th. You paid the full property tax bill in December of last year, so this year you have paid no property taxes. As a household your state income taxes for 2018 are approximately $8000 for the year. You have to pay your first half tax bill of $3000, so you will have paid a total of $11,000 in SALT (State And Local Taxes, i.e. income and property taxes) and can only deduct $10,000 on your federal taxes, so you have lost $1000 in deductions you used to get. If you pay the full $6000 then you will pay a total of $14,000 in SALT, can only deduct $10,000 so lose $4000 in deductions you used to get.


If you just pay the first half, in April you will have to pay $3000 for the second half taxes, in December you will have to pay the first half taxes for 2019-20, assuming it increases the maximum amount (2%, see above) that payment will be $3060 for a total of $6060 paid in property taxes in 2019. If your state income tax bill is the same, $8000, then you will have paid $14,060 in SALT and be able to deduct only $10,000 so you have $4060 you miss in deductions.  Provided there are no changes to the tax bill that increases SALT deductions.


The question you want to answer is do you want to have deductions left on the table this year or next year if the laws do not change? Personally, I will only pay the first half taxes this year and see if there is some political deal to revise the SALT deductions for 2019—I doubt there will be but we never know since there will be a new Congress starting in January.


Repeating my disclosure: I am not a tax professional. Before making any decisions regarding our taxes please consult with your tax preparer.


If you own property I strongly recommend you have two professionals assist you: a family law attorney to help you establish an estate plan with a trust and a professional tax preparer to ensure you are maximizing your tax opportunities as well as able to provide advice when needed.


If you have any questions on property taxes please do not hesitate to contact me and I will assist you the best I can.


If you, or someone you know, do not currently pay property taxes I am very willing and able to speak with you about how you can purchase property and become a homeowner!


Have a question? Ask me!


Prices are still under control. Strong increases in prices are still anticipated by many economists and analysts, as they have been for the bulk of the year, but have yet to manifest in the market place as inflation still remains under 3%. After dropping 0.1% in August, the Producer Price Index rose 0.2% in September and year over year wholesale prices are up 2.6%, the increase was in goods and services as food and gasoline prices both dropped nationally in September. On the consumer side the Consumer Price Index increased 0.1% in September, less than anticipated and slower than August’s increase of 0.2%. Year over year consumer prices are up 2.3%, a drop from August’s 2.7% annualized increase in prices. The most significant push on higher prices in September were higher costs for renters and home owners. Good news in the report was the after inflation wages for workers rose 0.3% in September and year over year are up 0.5%. The report is the basis for 2019 CPI adjustments for the government and it has been reported that social security benefits will increase 2.8% next year. Over all the price news is neutral for mortgage rates.


Rates for Friday October 12, 2018: A see-saw week for mortgage rates this week as investors ran to and fro with their money reacting to Fed-speak and speculation the Fed will increase rate by one-half of one percent (0.5%) in December instead of the anticipated one-quarter of one percent (0.25%) and have four rate increases next year instead of three. As well the drop in stock prices this week caused many investors to put some of their proceeds from selling their equity holdings into bonds—though it appears most of the money went into cash. We have a volatile rate environment, now is not the time to float your rate or try to time a dip, lock your rate when you can. All that said, rates are down slightly after last week’s spike late in the week.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.75%    Down 0.125%

30 year high-balance conforming                    5.00%     Down 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


Is it me or does it seem like Hurricane Michael had little of the pre- and post-landfall coverage that Florence received last month? Michael was the strongest hurricane to hit the United States mainland in over fifty years and the power of the storm is very evident in the pictures we are now seeing. Whole groves of trees snapped in half, houses not only flattened but blown completely away. The devastation looks more like a tornado than a hurricane, but with a significantly larger impact area. Several times a year it seems I post this link in the WR&MU, here it is again, if you are able please make a donation of any size to the American Red Cross who does incredible work assisting those impacted by disasters.


Have a great week,


Dennis

10-5-18: How does the Federal Reserve impact mortgage rates?

Question of the week:  How does the Federal Reserve impact mortgage rates?


 Answer:  Indirectly.


Long time readers of the WR&MU know I mention the Federal Reserve, aka the Fed, a lot in updates, usually in the section covering news of the week that impacts mortgage rates. Whenever the Fed changes rates I usually get inquiries from different sectors of my life as to what it means for mortgage rates. This week the Fed raised its Federal Funds Rate by 0.25% and at two different meetings subsequent to the rate increase I had conversations regarding what it means for mortgages.


Before we cover the impact that the Fed has on mortgage rates let’s cover what rates the Fed does impact directly. There are two interest rates that are directly associated with the Federal Reserve and the Fed does not directly control either. The Federal Funds Rate is the rate at which member banks charge each other for over-night loans so they can cover their required minimum reserves, the Federal Discount Rate is the rate at which the Fed loans money over-night to member banks so they can cover their reserves.

What reserves? Depending on its size a bank in the United States must retain either 10% of their total deposits (banks with more than $122.3 million in deposits) or 3% of their deposits (banks with $16 to $122.3 million in deposits) in their banks. If a bank slips below this requirement due to making loans that total more than the either 90% or 97% that can be out in loans, the bank must borrow money to add to its reserves to meet the requirement. The bank can either go to the Fed’s discount window and borrow the needed funds, or it can borrow the funds from another bank that has reserves above the reserve requirement. Depending on whether it goes to the discount window or another bank will be determined by the rate each is charging.


How are those rates set? The Federal Reserve sets the rate it charges at the discount window, and this changes daily based on the market, demand and objectives of the Fed as to what it wants to do with its assets—loan them out to member banks or retain them for its own reserves. The rate that gets all the publicity is the Fed funds rate, the rate banks charge each other to lend money over-night.


This week the Fed was in the news and it was reported that the Open Market Committee of the Federal Reserve (aka the FOMC) raised the Fed funds rate by 0.25% (one-quarter of one percent). So to the casual observer with some knowledge of the Fed the presumption is that the Fed is telling its members that it must increase the rate it charges other banks to borrow money over-night by 0.25%. Somewhat accurate, but not entirely. What the FOMC announces when it “increases” rates is the target rate it would like to see banks charging each other, but the actual rate is determined by supply and demand each night and what lending banks are willing to charge and what member banks are willing to pay.


Confused? Example: Fred’s Bank at the close of the day has $150 million in deposits, but only $15 million in reserves on hand, it is short $1 million to meet the reserve requirement. Fred’s Bank’s reserve requirement manager goes on-line and sees the Fed is willing to lend the million dollars over-night at a rate of 2.25% (the Fed discount rate), the manager then checks the member bank website and sees that Jane’s Bank, which also has $150 million in deposits but $19 million in reserves, or $4 million above the requirement, is willing to lend one million dollars over-night for 2.23% under the Federal Funds agreement between member banks. The manager at Fred’s Bank can save 0.02% borrowing from Jane’s bank and initiates the transaction. In reality the amount borrowed over-night is in the billions, tens of billions so the savings for small differences such as 0.02% become pretty big.


The only rate set by the Fed is the discount rate it charges for over-night loans, but it influences the funds rate by making a strong suggestion to member banks as to what rate it would like see them use for making over-night loans. The two are usually very close, but again determined by the market.


Back to our question, how does the Fed impact mortgage rates?


As you can see there is no consumer rate that the Fed manages or dictates. However, but by impacting the rate at which banks can borrow money it is also impacting the rate at which banks will loan money to consumers. If a bank can make enough loans so that it is constantly below the reserve requirement, borrow money from the Fed at 2.25% to cover the required reserves and then lend the money it is borrowing at 2.25% to clients at say 5.25% it is making 3% on the money it is borrowing.


The 5.25% in my example is what the current prime rate is after the Fed rate increase last week. This impacts homeowners with Home Equity Lines of Credit directly, and the increase in the prime rate was a direct result of the action by the Fed’s Open Market Committee to raise its target for the funds rate.


However, long term mortgage rates, the 30-year fixed rate the majority of borrowers obtain, is not impacted by the FOMC decision. Directly.


Indirectly, the Fed’s move impacted mortgage rates months ago. And the current actions, and statements, by the Fed are impacting future mortgage rates. How?


Mortgage rates are determined by the open market. Investors, and think hundreds of billions of dollars daily, have many choices to make that balance their desire for high returns for their funds and minimizing risk that those funds will decline in value due to the wrong investment decision. Investors are also gamblers. They are constantly research the economy, markets, industries and hundreds of other factors with the sole objective of trying to predict what will happen tomorrow, next week, next month and next year. Based on their information they make the decision to invest in equities, aka stocks, which means you own part of a company; or fixed rate assets that pay a specified rate of return for a specified period like bonds, or mortgages.


The most basic piece of information to determine whether to invest in equities or bonds is information that shows how the general economy is doing. If the economy is doing really well, or looks like it will be doing really well, money will go into stocks, causing stock prices to increase, and money will go out of bonds and rates will go up. Why? If the economy is doing well companies will earn more money and therefore be worth more in the future, investors are buying today, low, and looking to sell in the future, high. They leave fixed rate assets like bonds because as the economy improves rates will increase so the rates they are fixing today by buying a bond will be worth less money in the future after rates increase. Conversely, if it appears the economy is slowing down, or contracting, investors will sell equities as companies will be earning less or be losing money in the future, and buy fixed rate invests instead locking in higher rates today with the presumption rates will decline as the economy declines; the higher rates they lock into today will be worth more money in the future when rates are lower.


Example: Investor reads the economic tea leaves and sees a growing economy. The option is to purchase a fixed rate investment paying guaranteed 4% for the next five years, or purchase a shares in a mutual fund that focusses on growth. Based on the economy growing, rates will increase so in one or two years the same fixed rate investment may be 5% or higher, or 25% more than the current return, but the money would be locked in at 4%, missing out on the opportunity for the higher rate of return. The mutual fund with companies that experience growth in strong economies is expected to return 6-7% over the next one or two years. If the investor is correct the money will be invested in the mutual fund, and then in a year or two the decision will be made with that money to either sell the mutual fund and re-invest in fixed assets now paying over 5% or leave the money in the fund. Because the 4% fixed rate is not enough to attract investors to invest the rate will increase until investors are attracted.


Move ahead two years and the economic growth is losing, or has lost, steam. Rates have gone up to encourage investors, which has also been a factor in slowing economic growth. The investor has made an average of 6.5% by investing in the growth fund but sees the economy has slowed. Looking at the markets there is a fixed rate bond that is guaranteed to pay 6.25% for the next five years. Knowing a bad market will cause rates to decline, and also slow the growth of companies, the investor sells the growth fund holdings and purchases the fixed rate bond. As the economy does slow down the investor is collecting a higher rate of return on the fixed asset than newer bonds coming to market are paying, as well as a lot more than the growth fund that is now losing value.


The Fed indirectly impacts mortgage rates as it provides a look into the future for investors as to which way interest rates are headed, often by broadcasting in advance its future intentions with rates. The rate increase last week had no impact on mortgage rates because the Fed told the world in 2017 its intention to increase rates through 2018, how often and by how much. We know that the Fed will increase its target for the funds rate by December 31st by another 0.25%, if it does then there will be no impact on mortgage rates as investors have already priced this increase into bonds and mortgages. If however, the target is increased by 0.50% instead of 0.25% mortgage rates will jump as the rate increase was higher than expected and investors will have been caught off-guard and will sell off holdings they purchased anticipating only a 0.25% increase.


What impacts mortgage rates is the expectation for what rates will be in the future. What rates will be in the future is determined by economic activity. This is why I include a brief economic report every week in the WR&MU, so readers can get an idea of the strength, or weakness, of the economy and from that get a good idea if rates will be going up, going down, or holding steady.


Even with economic activity it is still somewhat of a guessing game as at any time rates can bounce up or fall down based on national or international events. The rule of thumb for mortgage rates is bad news means low rates and good news means high rates.


I hope this was not too much deep in the weeds in describing the Fed’s impact on your mortgage rate, but it is hard to make a simple explanation on a somewhat complex issue.


Have a question? Ask me!


First Friday means jobs. On the First Friday of every month the Labor Department releases the labor statistics for the prior month. Today’s release contained a huge headline number that will cause a stir and details that need further examination. The important data is that non-farm payrolls increased by 134,000 for the month, well below the expectations of 168,000 and below the average of over 200,000 new jobs for month for the first nine months of the year. It is unknown if the lower than expected number of new hires was impacted by Hurricane Florence, or if it is signifying a slow-down in hiring that will continue. Employers are having a hard time finding workers, as indicated by the headline unemployment rate dropping 0.2% from August to 3.7%, the lowest unemployment rate since December 1969. Wages grew 0.3% for the month and are up 2.8% from last August. The news is not positive for rates. With unemployment dropping employers will need to continue to increase wages to fill vacancies, which will in turn require prices to increase to cover the higher labor costs. This can start a wage and price inflation spiral that can be difficult to control. This leads to expectations for higher rates, which puts very strong upward pressure on interest rates.


Rates for Friday October 5, 2018: Several months ago, I wrote about the Fed selling off its accumulation of mortgages and U.S. Treasury bonds it purchased over the years following the recession. At the same time these assets are hitting the market the U.S. Treasury is also selling short and long term debt to finance the operations of the government. With increased supply on the market, which drives down prices and rates up, plus economic data indicating there is a strong possibility of higher inflation, and therefore higher rates, it is not surprise that the U.S. Treasury 10 year bond yield is at its highest since July 2011 and that 30-year fixed mortgage rates today hit their highest levels since April 2011. There is some over-reaction from investors this week to the employment data, however when they make adjustments to their behavior, any decrease in rates will be much more modest than the increase we have seen since the end of August. Now is the time to lock in your mortgage rates.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.875%    Up 0.25%

30 year high-balance conforming                    5.125%    Up 0.125%

Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


Thanks to my wonderful wife Leslie, PR consultant extraordinaire, and her terrific team, my website is fully functional and includes past Weekly Rate & Market Updates through 2016. The posts from 2016 and 2017 will see some changes, hopefully over the weekend, as I tighten up the titles. The posts from this year are listed by date and also show the Question of the Week to help visitors find topics they are interested in learning more about. There is still some cleaning up and beautifying to go but I am excited that archives of past updates are now available.


To visit the website, go to www.DennisCSmith.com or directly to the page with the WR&MU history go to www.DennisCSmith.com/MyBlog .


Thank you to everyone who got back to me on last week’s topic regarding the Propositions on the California ballot in November, it was the most feedback I have had on a Question of the Week in some time. If you missed it click here.


Have a great week,


Dennis

9-28-18: Are there any Propositions on the November ballot that are real estate related?

Question of the week:  Are there any Propositions on the November ballot that are real estate related?


 Answer:  With the election just over month away, and your absentee ballot available in ten days, and the onslaught of television ads just starting, now is a good time to review some of the propositions on your ballot.


A brief bio break before I get into the ballot measures. I have a Bachelor of Arts in Economics and Political Studies from Pitzer College (1984) and have continued to be a student of both disciplines. My philosophy is that economics is the foundation of most personal, organizational and political decisions—if you cannot afford it you cannot do it, and if  you do the long-term consequences will generally not be positive. With that out of the way let’s look at the real estate related propositions on your November ballot.


There are four ballot measures that in some way involve real estate in California, Props 1, 2, 5 and 10. Here is a brief description of each and my position (if you are so inclined to care).


Proposition 1: Affordable Housing Bond If passed this measure authorizes the state to borrow $4 billion in bonds for affordable housing. The funds would be broken into different areas of expenditure with the largest amount being for the building and renovating of rental units. Other funds would be used to provide home loan assistance to Veterans, housing construction in densely populated areas, down payment assistance programs for low and moderate income potential homebuyers and housing development for agricultural workers.


Understanding that more affordable housing is needed in the state I do not feel adding $4 billion in bond payments to our budget and cycling the money through state and local bureaucracies is the way to provide more affordable housing. Supply and demand create prices, some of these funds are targeted in a manner to increase demand, which increases prices, and other funds are targeted to rather ambiguous objectives that appear to expand the power of the government in the market place. I feel that local ordinances and applying tax benefits to developers and property owners would be a more efficient way to create more affordable housing. Dumping government funds into a market has never been shown as a way to lower market prices. I will be voting No on Prop 1. I expect this measure to pass given the lack of a unified opposition and the funds coming into the “Yes” side of the ballot.


Proposition 2: Mental Health Housing If passed this measure authorizes the state to re-allocate funds currently directed to county mental health services across the state to fund supportive housing for those suffering mental illness. With a directive and the funding the state can make strides in providing long-term solutions to mental illness sufferers and provide blueprint for counties to help with their homeless problems. Across levels of government funds have been allocated for the homeless with no impact on the problem—it seems to be getting worse. By creating housing for the mentally ill that includes on site social services and medical services this proposition is the best solution I have seen proposed so far at any level to start to make a dent in the issue. I will be voting Yes on Prop 2. I expect this measure to pass given its purpose and how much the issue has been one of top concern to most of the state’s residents.


Proposition 5: Residential Property Tax Portability If passed this measure would expand the current property tax transfer rules of Props 60 and 90. Under current rules if homeowner over 55 sells their current residence and purchases a new residence of lower value the homeowner can transfer their current tax base to their new home. The portability of the current tax base is limited as only a few counties in the state allow those otherwise eligible to transfer their current tax base into their county (i.e. homeowner selling Orange County could not transfer tax to new home in Shasta County). As well the current laws allow only a one-time transfer.


If Prop 5 is passed the one-time transfer limit is eliminated and the purchase price of your new home does not eliminate your ability to transfer your tax base to lower your taxes if your new home costs more than the home you sold—your tax base will go up but not to market value. As well if you purchase a home for lower value than the home you sold your tax base will be lower than your current tax base. Here are two examples to hopefully clarify how the measure will work if passed.


Buying more expensive home:  A couple that qualifies for the property tax transfer owns a home in Los Angeles County they purchased many years ago for $110,000. Today the taxable value is $200,000 and their base tax is $2200 per year ($200,000 x 1.1% state property tax rate). They sell their home for $600,000 and purchase a new home in San Luis Obispo County for $700,000. Their new property tax base is calculated by subtracting the sales price from their prior home from the sales price of the new home and adding the result to the tax base from their prior home:


New home price minus prior home sales price: $700,000 – $600,000 = $100,000

Price differential plus prior home tax base: $100,000 + $200,000 = $300,000


The new tax base is $300,000, for annual property tax base of $3300 ($300,000 x 1.1%). Without Prop 5 the tax base would be $7700 per year (market value $700,000 x 1.1%), the homeowners are saving $4400 per year.


Buying less expensive home: This gets a little more complicated as the new tax base is reduced by a percentage based on the difference between the old property value and the new property value. Same couple sells same home for $600,000 with $200,000 tax base. They purchase a new home in San Luis Obispo County for $450,000.


New home price divided by prior home sales price: $450,000 ÷ $600,000 = 75%

Old tax base times price differential percentage: $200,000 x 75% = $150,000


The new tax base is $150,000 for annual taxes of $1650 per year, a savings of $550 per year over what they are currently paying.


I think the best tax law in America is California’s Prop 13. We pay some of the highest income and sales taxes in the country, but homeowners have the best property tax protection from the state of any state in the country. Prop 5 makes the Prop 13 even more generous to homeowners over the age of 55. Because of the over-generosity of Prop 5 I will vote No. If Prop 5 were to mirror Prop 60 and only eliminate the inability to transfer tax bases over any county lines in the state and enable more than one transfer, particularly in cases of divorce or spouse who have passed away, I would vote for Prop 5. As it is written with homeowners purchasing a new home and being able to lower their tax base to me is not equitable to the counties, state or other tax payers and is not needed. And most importantly, if Prop 5 does pass I see it as a strong rallying issue for those who want to eliminate Prop 13 or severely alter it so that higher property taxes result in the future. I expect this measure to fail.


Word has it that the California Association of Realtors is already working on a revision to Prop 5 for the 2020 ballot should the measure fail this year. I hope they do as I would like to see the current Prop 60 benefits available to be transferred across county lines. Were I to be asked to craft a revised proposition I would make the changes I suggest changing the calculation on purchase a new home for a higher price to increase the tax base from formula in Prop 5, eliminate ability to lower tax base by purchasing a new lower priced home, eliminated unlimited ability to transfer the tax base but enable additional transfers due to divorce and/or spousal death, and finally I would raise the age of eligibility to 60 from 55.


Proposition 10: Local Rent Control Initiative If passed this measure will roll back a 1995 law that limited the use of rent control in California (Costa-Hawkins) and enable greater ability for local government to pass, and/or expand, rent control in their jurisdictions. Costa-Hawkins disallowed cities from enacting rent control on properties first occupied in 1995 and single family dwellings (including condos and townhomes). If passed Prop 10 would enable rent control on all rental units, including single family dwellings—and room rentals inside a single family dwelling.


Any rent control imposed by government on landlords benefits a very narrow group of residents: those already renting. Wherever rent control has been enacted rental prices are higher than similar geographically nearby markets. Rental units are scarce in rent control communities as tenants do not move to preserve their low housing cost. Because of the scarcity of available units with a rent control unit does come on the market the landlord is able to get premium rent for the unit since there is little competition. Over time as each generation of rent controlled tenants vacate units the rents in the market climb disproportionate to the surrounding markets.


According to a spokesman from the California Business Roundtable there are currently 12,000 rental units across the state approved for construction. Every project is on hold until after the November election. Should Prop 10 pass the projects will not start building as the investors/builders do not want their investments to be restricted from market returns by local governments enacting rent control. I will vote No on Prop 10. I expect this measure to fail.


There have been many great benefits to Californians as a result of the ballot initiative process, ad many great detriments as well. It is our duty to study the issues, and candidates, presented and understand both sides before casting our ballots. I hope the above comments on the propositions involving real estate provide you with a decent perspective and spur you on to study these and the other propositions more thoroughly.


Have a question? Ask me!


A busy week for mortgage rate impacting news. First, and most expected, the Fed increased it Fed Funds Rate by 0.25%, as expected. The immediate result was the prime rate, and therefore rates on Home Equity Lines of Credit, also increase 0.25%. Prime rate is now at 5.25%, up one percent from one year ago. The Fed announcement also indicated it is sticking to schedule of one more increase in rates this year and three next year. The news is mortgage rate neutral since the rate increase was expected and the Fed did not announce they anticipate more increases than previously announced.


Second quarter Gross Domestic Product went through its third and final evaluation and there was no revision made to the prior revision putting the growth for the quarter at 4.2% annualized. With no change to the growth number there was no impact on mortgages.


Last Friday of the month gives us important data on consumers as personal income, consumer consumption and inflation data are released. Good news on all fronts for mortgage rates as personal income matched last month’s increase of 0.3% and the core inflation rate dropped from 0.4% in August to flat this month—meaning those higher wages will go further. Consumer increased spending by 0.3%, lower growth than previous months but still the sixth month in a row of positive spending growth and the eleventh of the past twelve months and 3.8% overall gain in spending from last year. Overall the news should be somewhat negative for rates as it shows economic strength is continuing and should continue through the third and fourth quarters absent some catastrophic event.


Rates for Friday September 28, 2018: Intra-week rates had a bounce up and then down and the result is the conforming rate is flat from last Friday and the high-balance rate is down slightly for the week. Many analysists are hinting at a possible decline, very small decline, in rates in the next week or so; however, this analysist is not convinced of the underlying factors that would make a such a prediction a strong one.


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.625%    Flat

30 year high-balance conforming                      4.75%     Down 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


I have a pretty strong background in politics and economics, which perhaps comes through in my WR&MU. My mom grew up in a very politically connected household in Sacramento. Her father was an attorney and lobbyist and her mother was socially active in political circles. My mother continued the family behavior. When my sister, brother and I were growing up we did so with campaign pins and bumper stickers, meet-and-greets with candidates and seeing our mom very briefly on the television from the 1968 Republican National Convention in Miami.


Growing up my goal was to become and attorney like my grandfather and both uncles and I majored in economics and political studies in college. My study habits my last few semesters were not great so I put law school on hold to get some discipline. I started earning money, found the mortgage industry and law school was permanently in the rearview mirror. However, my interest in the two disciplines that comprised my major has never left me and I continue to study and read history, economics and political books, articles and journals. For those wondering, the basis of my personal philosophy is that economics is the overwhelming factor that influences politics and therefore history, be it within a family (microeconomics) or nation (macroeconomics). As I often say, take care of the economics and most other issues sort themselves out.


Whatever your interest I hope you are able to spend personal time daily, weekly, monthly to indulge in your interest and continue to expand your scope of knowledge and understanding.


Have a great week,


Dennis

9-21-18: Should we refinance and use proceeds to payoff debt?

Question of the week:  Should we refinance and use proceeds to payoff debt?


 Answer:  Not if you can payoff your debt without tapping into your equity.


With rates still low many families are looking at their accumulated consumer debt and wondering if they should refinance, or get a home equity loan, to payoff their debt and lower their monthly credit payments. Being able to get a rate for a cash-out refinance possibly somewhere around 5% for a 30 year fixed rate mortgage seems better than paying high, possibly as high as 20%, on credit cards. But is it a good idea?


On paper, the math seems really good, but a deeper look shows it probably is not for most families.


Take a scenario where you have a home worth $550,000 and you have a balance of $365,000 on your current mortgage with a rate of 3.75% and your payment is $1850 with about 25 years left on the loan. You do not intend to move anytime in the future as your kids are in, or just about in, middle school.


For various reasons, some emergency, some just consumer spending, you have accumulated about $35,000 in revolving debt (credit cards) with minimum payments totaling about $700 per month, have a few collections from past medical expenses for another $2000, a car payment of $560 with a balance of $20,000 and you need to replace your roof which will cost about $20,000. You have about $10,000 in savings and are making maximum contributions to your retirement accounts. You have been trying to pay down your credit cards but have not seem to be able to make a dent in the total balances and are at the stage where you make minimum payments and pay off most of what you charge each month.


Recapping, you have about $57,000 in debt costing you $1260 per month in minimum payments, this includes collection accounts with no payments being made, and you need about $20,000 for a roof. Should you either refinance and add $77,000 to your mortgage or get a home equity line for close to that amount, to payoff all your debt, fix the roof and start over with only a mortgage payment? To do so would require about $442,000 for a mortgage balance, or your current mortgage with a home equity line.


We would want to keep your new loan amount at or below 80% loan to value, which would be a new mortgage for $440,000, a bit short of what you require but you would be able to pay that off quickly with your new financial obligation shift.


Taking a look at a new mortgage of $440,000 for a cash-out refinance at 80% loan to value you would be looking at a rate of about 5% depending on credit score and other factors. This would make your new mortgage payment about $2350 per month, or $500 more per month than what you are spending now on your credit obligations plus replacing your roof. With the new loan and $500 per month higher payment you are getting rid of $1260 in monthly payments for a net savings of $760 per month.


Sounds pretty good, payoff debt, get a new roof and save $1260 per month. But is this something you should do?


Scenarios I run by clients before initiating the application for such a debt-relief refinance are as follows:


Reconsider including your vehicle loan in any debt consolidation scenario. Auto loans are generally lower rates than credit cards, and in the past several years with decent credit rates below mortgage rates. They are also fully amortized, meaning with every payment you are paying down the loan balance until it reaches zero. In the above scenario, you have about three years left on the loan and you are paid off. If you include it in a mortgage refinance you will be paying for the car as part of a thirty year mortgage. Taking the loan out the new mortgage balance would be $420,000, your payment on the mortgage would drop to about $2245. You would now have a mortgage payment that is just over $400 per month higher than your current mortgage, you are paying off debt with payments of about $700 month for net savings of $200 plus have funds to replace your roof.


Consider a home equity line of credit (HELOC) instead of refinancing your mortgage. The rate will be higher, and adjustable with it going up the next few years, however you will have the opportunity to save on monthly payments, or not depending on how you handle the repayment of the HELOC. If you go this route, you obtain a HELOC for $50,000 (following advice above and leaving vehicle loan out of the consolidation plan) at a rate of Prime plus one-half of one percent. Prime is at 5.00% today giving you a rate of 5.5% on the HELOC. The minimum payment for most equity lines is interest only, in this case that would be about $230 per month which looks like a big savings over what you are paying now—and that is the debt trap. If you pay interest only you are in worse position than you are now. Yes, your monthly cash flow is better but you are making no reduction in the balance. If you get a HELOC my very strong recommendation is you continue making the same total of payments you were making before, except instead of paying minimum payments on credit cards you are paying down your HELOC balance. Currently you are paying $700 on the cards, so pay $700 on the HELOC, this will decrease the balance $470 per month at the current rate. If the rate never changes and you make $700 per month payments you will have the HELOC paid off in about seven years. However, the rate will very likely be going up at least one percent in the next year, and perhaps more in the future. When calculating long term HELOC rates I usually use an average Prime rate of about 8% to be safe, at this average rate and a payment of $700 per month your time frame to payoff the loan for your credit card debt and roof repair is about eight years.


Equity lines often have balloons. One factor to consider with the equity line is the repayment terms. Many are “open” for ten years, meaning you can reuse them as the balance is paid down/off, and during this period they require only interest only. After ten years HELOCs are either fully amortized for the remaining term, or are due with a balloon payment. Because of the change in terms later in the loan it is important to have a payoff plan on the HELOC when you obtain it so you are not in a position in the future where you need to potentially refinance again in the future.


Create a realistic plan to payoff you consumer debt yourself and just borrow to pay for the new roof. Make a very realistic budget of your net income and expenses, including debt payments. See what adjustments you can make to your lifestyle and how much those adjustments will save you per month. Take the savings and dedicate them to paying off your credit cards. Many years ago, before Dave Ramsey became a multi-millionaire by counseling families on paying off debt I would help clients with debt payoff plans that pretty much matches Ramsey’s plan. I called my plan Stop, Drop and Roll. Stop using credit. Drop your credit card balances one at a time, starting with the lowest balance. Roll the payments into the next lowest card when one is paid off. It takes commitment to the payments and whatever austerity measures you put in place but if followed will enable you to payoff your consumer debt without refinancing your mortgage and adding tens of thousands of dollars and years to your existing mortgage.

I am in the debt business, a mortgage after all is a debt—the largest debt for almost every homeowner. If you are feeling overwhelmed with your debt please contact me and I can help you, at no obligation or cost, work through options for paying down/off your credit obligations.


Have a question? Ask me!


August home sales are a bit of a mixed bag. While the total number of sales are down in the state from last year prices continue to rise and days on the market are stretching out in most areas as inventory on the market has grown for the past five months. Looking at the data it looks like the market is trending towards equilibrium between buyers and sellers after we have experienced several years of a sellers’ market. Statewide total sales in August were down 1.8% from July and off 6.6% from August 2018. The statewide median price, $596,410, is up 0.8% for the month and 5.5% from last year. Sales and prices locally are in line with the statewide direction on prices and units sold. In LA County, the median price in August was $607,490, up 1.7% from July and 6.4% from last August, the total number of sales were up 5.5% for the month but down 8.9% from last year. Orange County’s median price in August of $838,500 was 1.1% jump from July and 6.3% increase from 2018 with total sales showing 2.9% drop month to month from July and a 9.7% fall from 2018.


Rates for Friday September 21, 2018: Rates are up from last Friday as investors put money into the equity markets (i.e. stocks) and hedge against next week’s Federal Reserve Open Market Committee meeting—these are the folks that set the Fed rates that impact consumer rates, such as the prime rate that determines equity line rates. The Fed will bump their funds rate by 0.25%, that is expected and priced into the markets. Hedging is occurring because of what the FOMC members say about the future of short term rates, how many future increases, how soon, how high? While they will not directly answer these questions those who can read the Fed tea leaves will discern much from the minutes of their meeting. The consensus appears to be that the Fed will raise rates faster and higher than previously thought. Lock your rate when you can!


FIXED RATE MORTGAGES AT COST OF 1.25 POINTS LOCKED FOR 45 DAYS:

30 year conforming                                            4.625%    Up 0.125%

30 year high-balance conforming                      4.875%     Up 0.125%


Please note that these are base rates and adjustments may be added for condominiums, refinances, credit scores, loan to value, no impound account and period rate is locked. Rates are based on 20% down with 740 FICO score for purchase mortgages.


Long time readers of the WR&MU know I can be a bit of a data geek…well more than a bit. So I found it interesting that the link to the Waffle House index last week had one of the highest click rates I can recall from readers. For those in Southern California the nearest Waffle House is in Goodyear, Arizona, 337 miles away from the Smith abode in Long Beach. There have been plenty of trips home in the family van from Scottsdale that have begun with breakfast at Waffle House, but have not been to the one in Goodyear as I recall. I do love me some waffles!


Looks like a perfect fall weekend, which commences tomorrow (fall and the weekend) in Southern California with great weather, playoff implication baseball plus college and pros going at it on the gridirons. Enjoy your weekend and the first days of fall!


Have a great week,


Dennis